Health
LIC 3 New Insurance Plans 2026: Cancer Cover, Guaranteed Pension and Life Insurance Benefits Explained
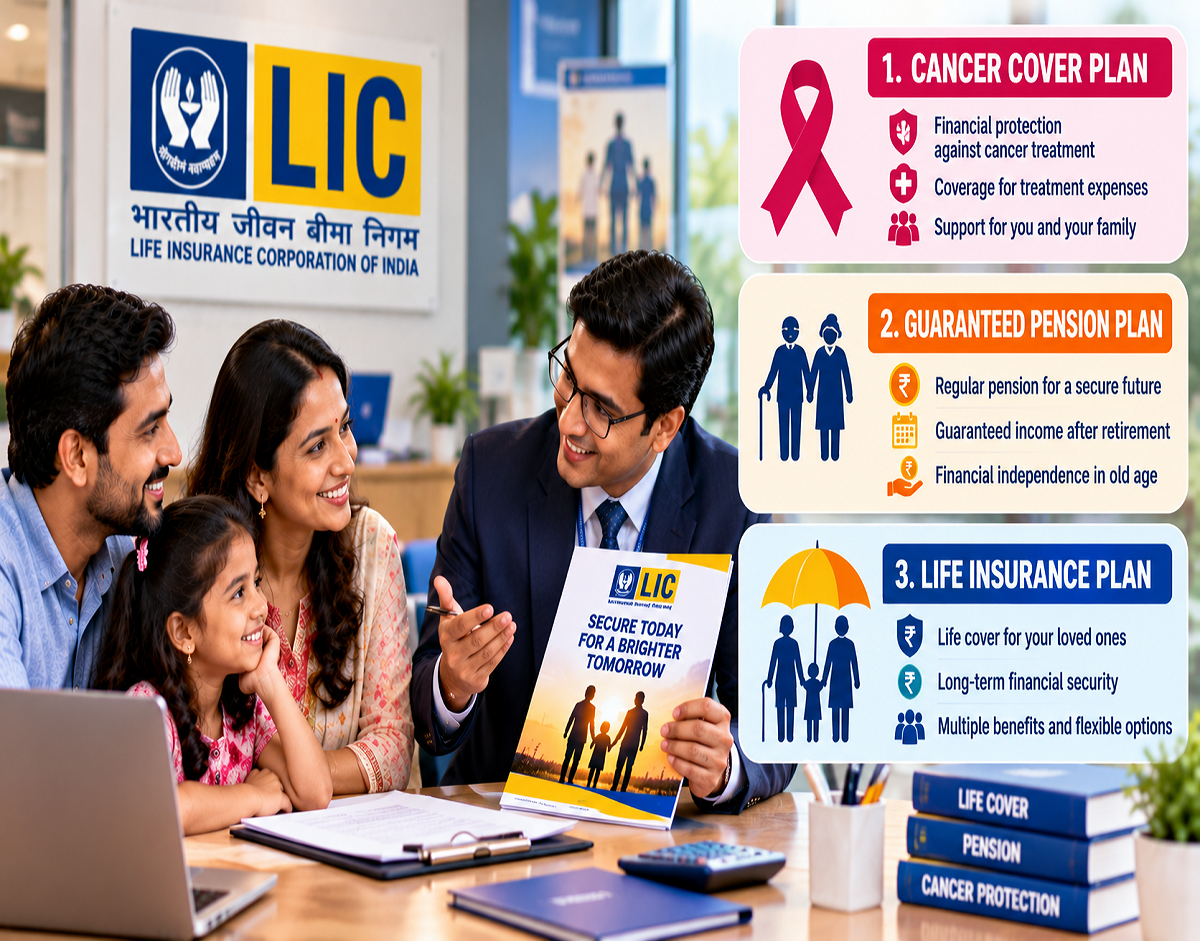
LIC New Insurance Plans 2026: Life Insurance Corporation of India (LIC) is reportedly preparing to introduce three insurance products focusing on cancer protection, retirement income and long-term savings. According to an October 14, 2026 report, the proposed plans are intended to address different financial needs, including serious illness expenses, regular pension payments and life insurance protection. However, the report does not identify the official product names, plan numbers or confirmed launch date, making it important for customers to distinguish expected features from officially announced benefits.
LIC New Insurance Plans 2026: What Is the Latest Update?
LIC is one of India's largest life insurance providers, offering products covering financial protection, savings and retirement planning.
As healthcare expenses rise and retirement planning becomes increasingly important, customers are looking for insurance solutions that address specific financial risks.
The October 2026 report suggests that LIC is preparing three products covering different categories of insurance and financial planning.
These reportedly include a cancer-focused protection policy, an annuity or pension product, and a savings-oriented life insurance plan.
The proposed offerings could appeal to people looking for financial support during serious illness, predictable income after retirement or long-term protection for their families.
However, the supplied information does not establish whether all three products have received the necessary approvals or whether they will become available simultaneously.
Customers should wait for official LIC product announcements before making purchasing decisions.
LIC Cancer Insurance Plan: What Benefits Are Expected?
One of the products mentioned in the report focuses on financial protection against cancer.
Cancer treatment can involve substantial expenses, including diagnostic tests, hospitalization, medicines and follow-up care.
A dedicated cancer insurance policy may provide a specified benefit when an insured person is diagnosed with a covered stage of the disease.
According to the report, the proposed product could offer benefits for early-stage and advanced-stage cancer.
However, the amount payable would depend on the final policy wording, diagnosis criteria and applicable exclusions.
Early-Stage Cancer Coverage
Some cancer-specific insurance products provide a defined benefit when an eligible early-stage cancer diagnosis meets the conditions stated in the policy.
The payment may be calculated as a specified percentage of the sum insured.
However, not every early-stage diagnosis necessarily qualifies for payment.
Medical definitions, waiting periods and exclusions are important factors.
Major-Stage Cancer Coverage
Policies covering major-stage cancer may provide a larger benefit when the diagnosis satisfies the relevant medical criteria.
The report refers to a possible lump-sum payout intended to help policyholders manage financial pressure during treatment.
However, the exact payout percentage, maximum benefit and claim requirements have not been confirmed for the proposed LIC product.
Customers should not assume that every cancer diagnosis will result in payment of the entire sum assured.
Will LIC Offer Premium Waiver and Regular Income Benefits?
The October 2026 report also refers to possible premium waiver and income support features.
A premium waiver benefit may allow eligible policyholders to stop paying future premiums after a qualifying insured event while maintaining certain policy benefits.
Similarly, an income benefit may provide scheduled payments for a specified period after a covered diagnosis.
These features can help families manage household expenses when illness affects their ability to work.
However, the availability and duration of these benefits depend on the policy contract.
The report does not provide an official benefit schedule confirming the amount, duration or eligibility conditions for either feature.
Customers should therefore treat these details as reported expectations rather than guaranteed provisions.
LIC Pension Plan 2026: Immediate and Deferred Annuity Options
The second category highlighted in the report involves retirement income.
Annuity products are designed to provide periodic payments according to the selected contract.
The report suggests that LIC may offer options involving immediate and deferred annuities.
What Is an Immediate Annuity?
An immediate annuity generally begins making payments shortly after the customer purchases the annuity, according to the chosen payout frequency.
For example, a retiree may invest a lump sum in an annuity product and select monthly, quarterly, half-yearly or annual income payments if those options are available.
The actual amount depends on the purchase price, age, annuity option and applicable rate.
What Is a Deferred Annuity?
A deferred annuity begins payments after a specified waiting or deferment period.
This arrangement may suit individuals who want to plan retirement income in advance.
However, the structure can vary significantly between products.
Some annuity contracts provide fixed payments, while others offer different benefit arrangements for spouses or nominees.
The report does not confirm which specific annuity options will be included in the proposed LIC product.
Will the New LIC Pension Provide Guaranteed Lifetime Income?
Certain annuity products provide contractually defined income payments for life.
This can help retirees plan regular expenses without depending directly on daily stock market movements.
However, the income amount depends on the selected annuity option and contractual terms.
A lifetime annuity should not automatically be interpreted as a guarantee that the investor will recover the full purchase price.
For example, some annuity options may provide higher periodic payments without returning the purchase price after death.
Other options may offer a return-of-purchase-price feature but provide a different income amount.
Customers should also consider inflation.
A fixed pension may remain unchanged while household expenses increase over time.
Therefore, the suitability of an annuity depends on the retiree's financial circumstances and other sources of income.
LIC Savings and Life Insurance Plan: What Could It Offer?
The third product category mentioned in the report combines savings and life insurance protection.
Traditional savings-oriented life insurance policies may provide a maturity benefit if the policyholder survives the term.
They may also offer a death benefit to eligible nominees if the insured person dies during the policy period.
Some participating insurance products include bonuses, while others provide guaranteed additions or other specified benefits.
However, these features cannot be assumed to apply to every LIC savings plan.
The October 2026 report refers to a combination of life cover, bonuses and maturity benefits.
Without an official product brochure, it is not possible to confirm the exact death benefit formula, bonus structure or maturity amount.
LIC 3 New Plans 2026: Expected Features Compared
| Proposed Product Category | Main Purpose | Reported or Possible Features |
|---|---|---|
| Cancer Protection Plan | Financial Support During Covered Cancer Diagnosis | Stage-Based Benefits, Possible Premium Waiver and Income Support |
| Pension or Annuity Plan | Retirement Income | Immediate or Deferred Annuity Options |
| Savings and Life Insurance Plan | Protection and Long-Term Savings | Death Benefit, Maturity Benefit and Possible Bonus Components |
These descriptions are based on the supplied report and general product structures.
They are not confirmed specifications for newly launched LIC policies.
Will LIC Offer Monthly Premium Payment Options?
The report suggests that customers may be able to choose from monthly, quarterly, half-yearly and annual premium payment arrangements.
However, premium frequency varies by insurance product.
For example, a regular-premium savings policy may allow periodic payments.
An immediate annuity, by contrast, may require a single purchase price rather than monthly premiums.
Therefore, the reported payment options should not be assumed to apply to all three products.
Customers should verify the premium structure separately for each policy.
Who Will Be Eligible for LIC's New Plans?
Eligibility generally depends on the type of insurance product.
Cancer insurance policies may specify entry age limits, medical conditions, waiting periods and other underwriting requirements.
Annuity products may have different minimum and maximum purchase ages.
Savings-oriented life insurance plans may impose conditions relating to age, premium amount, sum assured and policy term.
The supplied report describes the proposed eligibility conditions as flexible but does not provide exact age limits.
It also does not confirm minimum premiums or sums assured.
These details will need to be checked when official product documents become available.
Are LIC Maturity Benefits and Pension Payments Tax-Free?
Tax treatment is another important consideration.
The report refers to tax-free maturity benefits for savings-oriented insurance policies.
However, life insurance proceeds qualify for tax exemption only when the relevant statutory conditions are satisfied.
Section 10(10D) of the Income Tax Act provides exemptions for eligible life insurance receipts, subject to applicable restrictions.
Certain policies may not qualify because of premium-related conditions or other provisions.
Annuity or pension payments are generally subject to taxation according to the recipient's applicable income tax rules.
Similarly, cancer insurance benefits may have different tax implications depending on the nature of the payment and relevant law.
Customers should not assume that every payment from an LIC product is automatically tax-free.
How Can Customers Apply for LIC's New Insurance Plans?
The report suggests that the proposed products may be distributed through LIC's official website and authorized agents.
However, an application process cannot be confirmed until the relevant products are officially introduced.
Interested customers can monitor LIC's official website at licindia.in for product announcements.
Before purchasing a policy, applicants should review the official brochure, premium illustration and terms and conditions.
They should also check exclusions, waiting periods, surrender provisions and claim procedures where applicable.
Avoid paying registration fees to unknown individuals claiming to offer early access to unreleased LIC products.
What Should Customers Check Before Choosing a Policy?
The three proposed insurance categories serve different purposes.
Cancer protection is intended to address a specified health-related financial risk.
An annuity is designed to provide retirement income.
A savings-oriented life insurance policy combines financial protection with certain savings benefits.
Customers should first identify their primary objective.
Someone seeking protection against hospitalization expenses may need to compare comprehensive health insurance with disease-specific cover.
A retiree looking for predictable income may want to evaluate annuity options, including whether payments continue to a spouse.
A person purchasing life insurance should consider whether the death benefit is sufficient for their family's needs.
The most suitable policy depends on the customer's financial situation, existing coverage and long-term goals.
LIC New Insurance Plans 2026: Has the Launch Date Been Confirmed?
The October 14 report describes three proposed LIC products but does not specify their official names, plan numbers or a confirmed launch date.
It also does not provide a verified premium table or complete benefit schedule.
Therefore, the reported features should not be presented as final contractual benefits.
Customers should wait for LIC's official announcement to confirm availability, eligibility and product conditions.
Conclusion
LIC's reported plans for cancer protection, retirement income and savings-oriented life insurance reflect three important financial priorities for Indian households.
A cancer-specific policy could help address defined illness-related financial risks, while annuity products may support retirement income planning.
Savings-oriented insurance may provide another option for combining protection and long-term financial goals.
However, the exact benefits, premiums, eligibility rules and launch details remain unconfirmed in the supplied report.
Customers should compare official product documents carefully before investing.
Disclaimer: This article is based on the October 14, 2026 report provided. The three proposed LIC products have not been independently verified through official product announcements. Features discussed are subject to confirmation, and insurance benefits, exclusions and tax treatment will depend on the final policy contracts and applicable law.