Business
SCSS Calculator 2026: Invest ₹15 Lakh and Earn ₹10,250 Monthly? Check Interest and 5-Year Returns
Senior Citizens Savings Scheme 2026: Retirement planning becomes easier when you have a reliable source of income to manage household expenses, medical bills and everyday financial needs. For senior citizens who prefer government-backed savings options, the Senior Citizens Savings Scheme (SCSS) can be worth considering.
The scheme offers a fixed rate of interest for an eligible investment, with interest payments made every quarter. According to the rate mentioned in the October 15, 2026 report, SCSS currently offers 8.2% annual interest.
But how much can you earn by depositing ₹15 lakh? Can this investment generate ₹10,250 every month? And how much money will you receive over the scheme's five-year term?
Here is a detailed calculation explaining the interest income, maturity amount, eligibility conditions and other important rules.
What Is the Senior Citizens Savings Scheme?
The Senior Citizens Savings Scheme is a government-backed small savings scheme designed primarily for individuals aged 60 years and above.
Its main objective is to provide eligible retirees with a predictable source of interest income while preserving their deposited principal under the scheme's terms.
Unlike market-linked investments, SCSS does not depend on stock market movements to determine the interest payable on an existing deposit.
The interest rate applicable when an account is opened generally remains fixed for that deposit's original tenure.
This makes the scheme attractive to retirees who prioritise regular income and capital protection over potentially higher but uncertain returns.
SCSS accounts can be opened through designated post offices and authorised banks.
SCSS Interest Rate 2026: How Much Will ₹15 Lakh Earn?
According to the supplied report, the SCSS interest rate is 8.2% per annum.
Suppose a senior citizen deposits ₹15,00,000 in the scheme.
The annual interest calculation would be:
₹15,00,000 × 8.2% = ₹1,23,000
This means the investment would generate ₹1.23 lakh in gross interest over one full year at the stated rate.
Because SCSS pays interest quarterly, the annual amount is divided into four instalments.
The quarterly interest would therefore be:
₹1,23,000 ÷ 4 = ₹30,750
For monthly household budgeting, the quarterly payment can be divided into three equal portions.
That produces an average monthly equivalent of ₹10,250.
However, this is only a budgeting calculation. The scheme does not actually credit interest every month.
SCSS ₹15 Lakh Investment Calculator: Complete Breakdown
| Investment Details | Amount |
|---|---|
| Initial investment | ₹15,00,000 |
| Annual interest rate | 8.2% |
| Annual interest income | ₹1,23,000 |
| Quarterly interest payment | ₹30,750 |
| Average monthly equivalent | ₹10,250 |
| Total interest over 5 years | ₹6,15,000 |
| Principal returned at maturity | ₹15,00,000 |
| Total principal and interest over 5 years | ₹21,15,000 |
Calculations assume the stated 8.2% annual interest rate applies throughout the original five-year term, with no premature closure and no reinvestment of interest. Figures are before applicable taxes.
Does SCSS Pay ₹10,250 Every Month?
This is one of the most important points for retirees to understand.
Although a ₹15 lakh investment at 8.2% generates interest equivalent to ₹10,250 per month, SCSS does not make monthly interest payments.
Instead, the interest is payable every quarter according to the scheme's prescribed payment schedule.
For an investment of ₹15 lakh, the quarterly payment works out to ₹30,750.
A retiree can use this amount to manage expenses across the following three months.
For example, someone receiving ₹30,750 could allocate ₹10,250 toward each month's budget.
This approach can help create a monthly spending plan even though the actual payment arrives once every three months.
Investors should account for the timing of interest credits when planning essential expenses.
How Much Interest Will You Earn in Five Years?
The normal tenure of an SCSS account is five years.
Assuming an investment of ₹15 lakh earns 8.2% annually throughout the original term, the total interest can be calculated as follows.
Total 5-year interest
₹6,15,000
Principal + interest
₹21,15,000
Year-wise cumulative SCSS interest
Illustrative gross interest on a ₹15 lakh deposit at 8.2% annually.
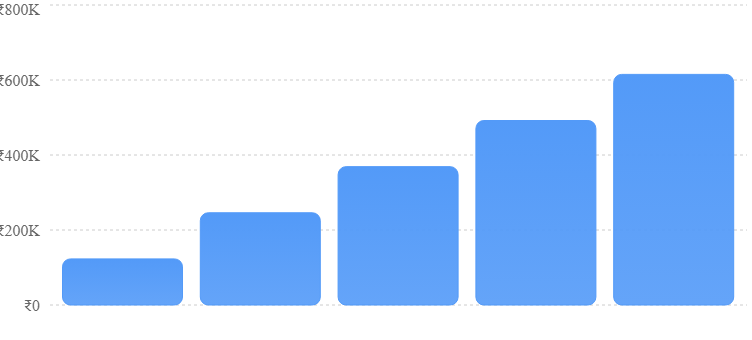
Over five years, the investor would receive ₹6.15 lakh in gross interest through quarterly payments.
At maturity, the original ₹15 lakh principal would also become payable.
This brings the total amount received over the entire five-year period to ₹21.15 lakh, including the interest already paid.
It is important to understand that ₹21.15 lakh is not a single maturity payout. The interest is distributed during the investment period, while the principal is returned at maturity.
Who Can Open an SCSS Account?
The Senior Citizens Savings Scheme is intended mainly for retired individuals and older savers.
The general eligibility conditions include:
- Individuals aged 60 years or above can open an account.
- Certain retired civilian employees aged 55 to below 60 may qualify, subject to retirement-benefit and investment-timing conditions.
- Eligible retired defence personnel may qualify from the age of 50, subject to scheme requirements.
- Accounts can be opened individually or jointly with a spouse, subject to the applicable rules.
Those applying under special retirement provisions should check the relevant documentation and eligibility requirements.
What Is the Maximum Investment Limit in SCSS?
Under the rules described in the report, the maximum aggregate deposit permitted for an individual across SCSS accounts is ₹30 lakh.
Therefore, a ₹15 lakh investment falls within the permitted ceiling.
At the stated 8.2% interest rate, an eligible investment of ₹30 lakh would generate:
| Investment | Annual Interest | Quarterly Interest | Monthly Equivalent |
|---|---|---|---|
| ₹5 lakh | ₹41,000 | ₹10,250 | ₹3,416.67 |
| ₹10 lakh | ₹82,000 | ₹20,500 | ₹6,833.33 |
| ₹15 lakh | ₹1,23,000 | ₹30,750 | ₹10,250 |
| ₹20 lakh | ₹1,64,000 | ₹41,000 | ₹13,666.67 |
| ₹30 lakh | ₹2,46,000 | ₹61,500 | ₹20,500 |
These are gross interest calculations based on an annual rate of 8.2%.
Can You Extend SCSS After Five Years?
SCSS has an initial maturity period of five years.
Eligible account holders can generally extend the account for a further three-year period under the applicable scheme rules.
However, the interest rate applicable during an extension may differ from the original deposit rate.
Investors should not assume that an 8.2% rate will automatically continue into an extended term.
Before requesting an extension, account holders should review the prevailing interest rate and the extension conditions.
Is SCSS Interest Tax-Free?
No. Interest earned through SCSS is generally taxable according to the investor's applicable income tax provisions.
The scheme may also be subject to tax deducted at source (TDS) when the relevant conditions and thresholds are met.
Eligible investments may qualify for deductions under Section 80C under the old income tax regime, subject to the overall statutory limit and applicable conditions.
However, the principal investment and interest income must be considered separately for tax purposes.
A retiree earning ₹1.23 lakh in annual SCSS interest should calculate their after-tax income based on their overall taxable income, deductions and chosen tax regime.
Therefore, the ₹10,250 monthly equivalent shown in the calculation represents gross interest before tax, not necessarily the final amount available for spending.
Is SCSS Better Than a Bank Fixed Deposit?
SCSS and bank fixed deposits are both commonly considered by people seeking predictable income.
However, they differ in several ways.
SCSS is a government-backed small savings scheme with specific eligibility conditions, a prescribed tenure and quarterly interest payments.
Bank fixed deposits may offer a wider selection of tenures, interest payment options and withdrawal arrangements, depending on the bank and product.
SCSS is specifically designed for eligible senior citizens, while ordinary bank fixed deposits are available to a broader range of customers.
The better choice depends on the investor's age, liquidity needs, applicable interest rates and tax situation.
Final Word
A ₹15 lakh investment in the Senior Citizens Savings Scheme at an annual interest rate of 8.2% can generate ₹1,23,000 in gross yearly interest.
This works out to ₹30,750 every quarter, equivalent to an average of ₹10,250 per month for budgeting purposes.
Over the normal five-year term, the total gross interest would amount to ₹6.15 lakh, while the original ₹15 lakh principal would be returned at maturity.
That means the combined principal and interest received over the investment period would total ₹21.15 lakh before taxes.
For eligible retirees seeking regular income and a government-backed savings option, SCSS may be worth evaluating alongside other retirement investments.
Disclaimer: These calculations use the 8.2% rate stated in the supplied October 15, 2026 report. Interest rates for new deposits are subject to government notifications. Actual interest payment dates, taxes and eligibility conditions should be verified with an authorised bank or post office before investing.