Business
₹20 Lakh Home Loan EMI 2026: Check Canara Bank Interest Rates and 10-Year Repayment Calculation
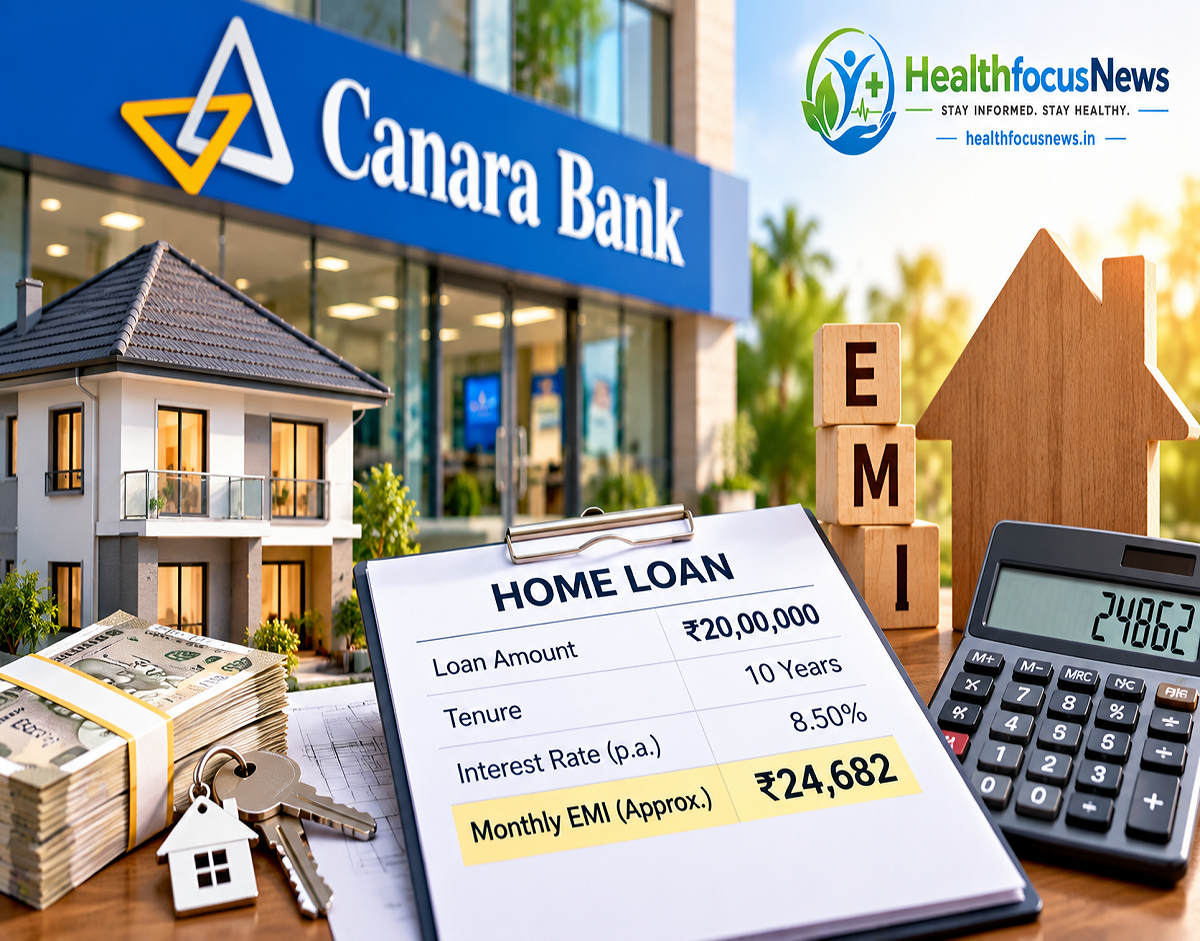
Home Loan EMI Calculator 2026: Planning to purchase a house with a ₹20 lakh home loan? Before applying, it is important to understand how much you may need to pay every month and how interest rates can affect the overall cost of borrowing.
Public sector banks, including Canara Bank, offer housing loans to eligible salaried individuals, self-employed professionals and business owners. However, the interest rate offered to each applicant may differ depending on their credit profile, income, loan terms and the bank's lending policies.
According to an October 16, 2026 report, Canara Bank's quoted home loan interest rates ranged from 7.20% to 10.00% per annum.
For a ₹20 lakh home loan with a repayment period of 10 years, the monthly EMI could range from approximately ₹23,428 to ₹26,430 under these interest-rate assumptions.
This difference may appear small on a monthly basis, but over 120 instalments, it can significantly affect the total interest paid.
Here is a detailed explanation of Canara Bank's reported home loan rates, monthly EMI calculations, total repayment amounts and factors that borrowers should examine before taking a housing loan.
Canara Bank Home Loan Interest Rates in 2026
Canara Bank is one of India's major public sector banks and provides home loans for eligible borrowers.
The supplied report states that its housing loan interest rates range between 7.20% and 10.00% annually.
These figures represent the reported rate range, not a guaranteed offer for every borrower.
The interest rate ultimately sanctioned by the bank may depend on several factors, including credit history, repayment capacity, employment category and the specific housing loan product.
Borrowers should also check whether the applicable loan rate is fixed or floating.
Floating-rate home loans may change when the relevant benchmark or lending rate is revised.
Therefore, the EMI calculated at the time of loan approval may not necessarily remain unchanged throughout the entire repayment period.
₹20 Lakh Home Loan EMI at 7.20% Interest for 10 Years
Suppose you borrow ₹20 lakh from Canara Bank at an annual interest rate of 7.20%.
If you choose a repayment tenure of 10 years, you will need to repay the loan over 120 monthly instalments.
Based on the standard reducing-balance EMI formula, the monthly instalment would be approximately ₹23,428.
The total repayment over 10 years would be around ₹28.11 lakh, including approximately ₹8.11 lakh in interest.
Minimum-Rate EMI Calculation
| Loan Details | Amount |
|---|---|
| Bank | Canara Bank |
| Principal Amount | ₹20,00,000 |
| Assumed Annual Interest Rate | 7.20% |
| Loan Tenure | 10 Years |
| Number of EMIs | 120 |
| Approximate Monthly EMI | ₹23,428 |
| Approximate Total Interest | ₹8.11 lakh |
| Approximate Total Repayment | ₹28.11 lakh |
This calculation assumes that the interest rate remains constant throughout the loan tenure.
It also excludes processing fees, insurance costs and other possible charges.
₹20 Lakh Home Loan EMI at 10% Interest for 10 Years
Now consider the same ₹20 lakh housing loan at an annual interest rate of 10.00%.
The repayment period remains 10 years.
At this higher interest rate, the monthly EMI would increase to approximately ₹26,430.
The total interest payable over the loan tenure would rise to around ₹11.72 lakh.
Consequently, the total repayment would be approximately ₹31.72 lakh.
Higher-Rate EMI Calculation
| Loan Details | Amount |
|---|---|
| Bank | Canara Bank |
| Principal Amount | ₹20,00,000 |
| Assumed Annual Interest Rate | 10.00% |
| Loan Tenure | 10 Years |
| Number of EMIs | 120 |
| Approximate Monthly EMI | ₹26,430 |
| Approximate Total Interest | ₹11.72 lakh |
| Approximate Total Repayment | ₹31.72 lakh |
This example shows how a higher lending rate increases both the monthly repayment burden and the overall interest cost.
How Much Difference Does the Interest Rate Make?
A comparison of the two scenarios reveals the financial impact of borrowing at different rates.
| Loan Comparison | At 7.20% | At 10.00% |
|---|---|---|
| Principal | ₹20 lakh | ₹20 lakh |
| Repayment Period | 10 Years | 10 Years |
| Monthly EMI | ₹23,428 | ₹26,430 |
| Total Interest | ₹8.11 lakh | ₹11.72 lakh |
| Total Repayment | ₹28.11 lakh | ₹31.72 lakh |
The difference in monthly EMI is approximately ₹3,002.
Over the full 10-year period, the higher interest rate could result in approximately ₹3.60 lakh of additional interest.
This makes it important for borrowers to compare interest rates before finalising a housing loan.
Even a relatively small reduction in the sanctioned interest rate can produce meaningful savings over time.
What Is the EMI Formula for a Home Loan?
Banks generally calculate home loan EMIs using a reducing-balance formula.
The standard formula is:
EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]
Here:
- P represents the principal loan amount.
- R represents the monthly interest rate.
- N represents the total number of monthly instalments.
For example, a 7.20% annual interest rate corresponds to a monthly rate of 0.60% for this calculation.
For a 10-year loan, the number of monthly instalments is 120.
Using these values, the approximate EMI for a ₹20 lakh loan is ₹23,428.
Borrowers can use this formula or a bank's official EMI calculator to estimate their monthly obligations before applying.
How Does the RBI Repo Rate Affect Home Loan EMIs?
The Reserve Bank of India's repo rate is an important benchmark for interest rates in the banking system.
The supplied report mentions a repo rate of 5.50% following the October 2026 monetary policy decision.
When the RBI raises the repo rate, borrowing costs for banks may increase, which can eventually influence the interest rates charged on loans.
For borrowers with floating-rate home loans linked to an external benchmark, changes in the relevant benchmark may affect their borrowing costs.
However, the exact impact depends on the loan agreement, reset frequency and applicable spread.
A bank may adjust the EMI, extend the repayment tenure or use another arrangement permitted under the loan terms.
Therefore, borrowers should check how their particular home loan responds to interest-rate changes.
Does a Longer Loan Tenure Reduce Your EMI?
Yes. Choosing a longer repayment period generally reduces the monthly EMI, provided the loan amount and interest rate remain unchanged.
However, a longer tenure also increases the total interest paid over the life of the loan.
For example, consider a ₹20 lakh loan at an assumed annual interest rate of 7.20%.
| Loan Tenure | Approximate Monthly EMI | Approximate Total Interest |
|---|---|---|
| 10 Years | ₹23,428 | ₹8.11 lakh |
| 15 Years | ₹18,200 | ₹12.76 lakh |
| 20 Years | ₹15,747 | ₹17.79 lakh |
| 25 Years | ₹14,391 | ₹23.17 lakh |
These calculations assume an unchanged interest rate throughout the repayment period.
A longer tenure may make the EMI more affordable, but the borrower ultimately pays considerably more interest.
The ideal repayment period should therefore balance monthly affordability with the total cost of borrowing.
What Determines Your Home Loan Interest Rate?
The interest rate offered by Canara Bank or another lender can vary from one applicant to another.
Several factors may influence the bank's decision.
Credit score: Borrowers with a strong repayment history and a healthy credit profile may qualify for more favourable loan terms.
Monthly income: Banks evaluate whether the applicant has sufficient income to meet the proposed EMI and other financial obligations.
Employment stability: Regular income and stable employment can influence the assessment of repayment capacity.
Existing loans: Personal loans, car loans and other EMIs may reduce the amount a borrower can comfortably repay.
Property details: The property's value, legal documentation and eligibility for financing can affect loan approval.
Loan-to-value ratio: The proportion of the property price financed through the loan is another important consideration.
Applicants should understand that the lowest advertised rate is generally subject to eligibility and bank approval.
How Can Borrowers Reduce Home Loan Interest Costs?
There are several ways to manage the overall cost of a housing loan.
One approach is to maintain a strong credit profile before applying. Paying existing loan instalments and credit card bills on time may improve a borrower's creditworthiness.
Another option is to compare housing loan offers from different banks instead of accepting the first available rate.
Borrowers can also consider making a larger down payment, provided doing so does not exhaust their emergency savings.
For existing home loan customers, part-prepayments may help reduce the outstanding principal and future interest burden.
However, the effect of prepayment depends on the loan structure, remaining tenure and applicable terms.
Borrowers should check whether any charges apply and whether reducing the EMI or shortening the tenure better suits their financial situation.
What Additional Charges Should You Check?
The interest rate and EMI are not the only costs associated with a home loan.
Depending on the lender and loan product, borrowers may encounter processing fees, valuation charges, legal verification costs and other expenses.
Property purchases may also involve stamp duty, registration charges and additional costs that are separate from the home loan itself.
These expenses should be included in the overall home-buying budget.
A borrower who can afford a ₹23,428 monthly EMI may still need substantial savings for the initial down payment and transaction-related expenses.
Frequently Asked Questions
What is the EMI for a ₹20 lakh home loan for 10 years?
At an assumed annual interest rate of 7.20%, the monthly EMI is approximately ₹23,428. At 10.00%, it increases to approximately ₹26,430.
What is the reported Canara Bank home loan interest rate?
The supplied October 2026 report quotes a range of 7.20% to 10.00% annually. Actual current rates and eligibility conditions should be confirmed with the bank.
How much total interest will I pay on a ₹20 lakh loan at 7.20%?
For a 10-year repayment period, the total interest is approximately ₹8.11 lakh, assuming the interest rate remains unchanged.
Can salaried and self-employed applicants apply for a Canara Bank home loan?
Yes, eligible salaried and self-employed applicants may apply, subject to the bank's income, credit and documentation requirements.
Will my EMI increase if the RBI raises interest rates?
It may increase if your loan has a floating interest rate and the relevant lending benchmark changes. The impact depends on your loan agreement and the bank's reset mechanism.
Final Thoughts
A ₹20 lakh home loan can involve significantly different repayment costs depending on the interest rate and loan tenure.
Based on the reported Canara Bank interest-rate range, a 10-year housing loan at 7.20% would require an EMI of approximately ₹23,428, while a 10.00% rate would increase the EMI to around ₹26,430.
The difference could add approximately ₹3.60 lakh to the total interest paid over 10 years.
Before taking a home loan, borrowers should compare interest rates, assess their monthly repayment capacity and review all applicable charges.
Choosing an affordable EMI is important, but understanding the total borrowing cost can help avoid unnecessary financial pressure in the future.
Disclaimer: This article is for general informational purposes. Interest rates are based on the supplied October 16, 2026 report and have not been independently verified against Canara Bank's current rate schedule. EMI figures are illustrative and assume constant interest rates, monthly reducing-balance calculations and no additional fees. Check the bank's official terms before applying for a loan.