Business
SIP Investment Plan 2026: Can Gen Z Build ₹1 Crore by Starting With Just ₹500 a Month? Check the Calculation
SIP Investment Tips for Gen Z: Building wealth does not always require a large salary or thousands of rupees in savings every month. For young investors, starting early and investing consistently can make a significant difference over the long term.
Even a monthly investment of ₹500 through a Systematic Investment Plan (SIP) can help create a meaningful savings corpus over several decades.
The key is to maintain regular contributions, increase the investment amount as income grows and allow compounding to work over time.
However, mutual fund investments are linked to market performance. Returns are not guaranteed, and the final amount depends on the selected fund, investment duration and market conditions.
Here is how Gen Z investors can begin their investment journey with ₹500 and potentially build a substantial long-term fund.
What Is an SIP and How Does It Work?
A Systematic Investment Plan is a method of investing a fixed amount in a mutual fund at regular intervals.
Instead of investing a large sum at once, an investor contributes a smaller amount every month, quarter or at another available frequency.
For example, someone who starts an SIP of ₹500 per month invests ₹6,000 in one year.
Over five years, the total contribution would be ₹30,000, excluding any investment gains or losses.
The invested money is used to purchase mutual fund units at the prevailing Net Asset Value (NAV).
Since the NAV changes with market conditions, the number of units purchased can vary from one instalment to another.
Over time, the value of the accumulated units may increase or decrease depending on the performance of the underlying investments.
Why Starting an SIP Early Can Benefit Gen Z
One of the biggest advantages younger investors have is time.
Someone who starts investing at age 20 may have 30 to 40 years before retirement.
A person who begins at age 35 has a shorter period to accumulate a similar corpus.
Starting early allows investment gains to remain invested for longer, creating the potential for compounding.
Compounding occurs when returns generated by an investment remain invested and may themselves generate further returns.
However, unlike a bank deposit with a specified interest rate, mutual fund returns are not fixed.
The compounding effect depends on the actual performance of the investment.
₹500 Monthly SIP Calculator: How Much Money Could You Build?
Suppose a young investor starts an SIP of ₹500 per month and continues investing without interruption.
For illustration, assume the investment generates an annualised return of 12%.
The following table shows the approximate future value for different investment periods.
| Investment Period | Total Investment | Estimated Corpus at 12% |
|---|---|---|
| 5 years | ₹30,000 | ₹41,000 |
| 10 years | ₹60,000 | ₹1.15 lakh |
| 15 years | ₹90,000 | ₹2.50 lakh |
| 20 years | ₹1.20 lakh | ₹4.95 lakh |
| 25 years | ₹1.50 lakh | ₹9.40 lakh |
| 30 years | ₹1.80 lakh | ₹17.47 lakh |
| 35 years | ₹2.10 lakh | ₹32.16 lakh |
| 40 years | ₹2.40 lakh | ₹58.82 lakh |
These figures are illustrative estimates using monthly compounding at an assumed 12% annual nominal rate, with contributions at the end of each month. Actual mutual fund returns will vary.
The calculation demonstrates how the investment horizon can influence the potential outcome.
However, a 12% return should not be interpreted as an assured annual return.
Can ₹500 Monthly SIP Really Grow Into ₹1 Crore?
A fixed monthly SIP of ₹500 is unlikely to reach ₹1 crore within a typical 25- or 30-year investment period under moderate return assumptions.
For example, at an assumed annualised return of 12%, a ₹500 monthly SIP could grow to approximately ₹17.47 lakh over 30 years.
The estimated corpus would increase to around ₹58.82 lakh over 40 years under the same assumption.
To pursue a ₹1 crore target over a shorter period, investors may need to increase their monthly contributions as their income rises.
This is where a step-up SIP strategy becomes useful.
What Is a Step-Up SIP?
A step-up SIP is an investment approach in which the investor increases the contribution amount periodically.
For example, someone may begin with ₹500 per month and raise the amount by 10% every year.
The monthly SIP would then increase gradually.
| Investment Year | Approximate Monthly SIP |
|---|---|
| Year 1 | ₹500 |
| Year 2 | ₹550 |
| Year 3 | ₹605 |
| Year 4 | ₹666 |
| Year 5 | ₹732 |
| Year 10 | ₹1,179 |
| Year 15 | ₹1,899 |
| Year 20 | ₹3,058 |
These figures assume a 10% annual increase, with amounts rounded to the nearest rupee.
The advantage is that investors can start with an affordable contribution and gradually increase it as their salary or earnings improve.
However, future contributions may become significantly larger, so the step-up percentage should remain realistic.
₹500 SIP With a 10% Annual Step-Up: Estimated Returns
Consider an investor who begins with ₹500 per month and increases the SIP contribution by 10% every year.
Assume an illustrative annualised investment return of 12%.
Under these assumptions, the potential corpus could be substantially higher than a fixed ₹500 monthly SIP.
Estimated SIP Corpus Over Time
Illustrative values in ₹ lakh, assuming 12% annual nominal return and a 10% annual SIP step-up.
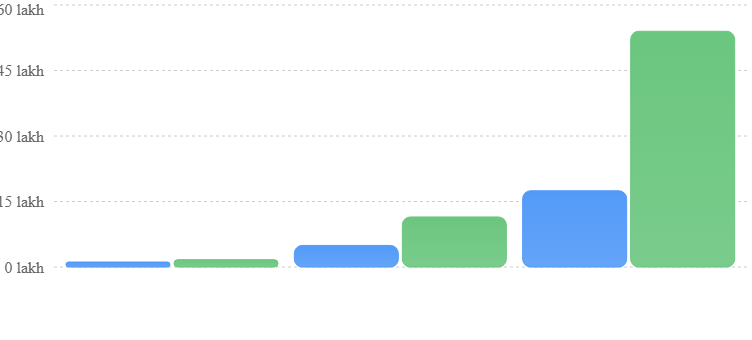
■ Fixed ₹500 SIP
■ 10% Annual Step-Up
Illustrative comparison only. Actual results depend on market returns and the timing of contributions.
Increasing contributions can have a major impact on long-term wealth creation because both the invested amount and the potential investment gains grow.
How Can Gen Z Start Investing With ₹500?
Beginning an SIP is relatively straightforward.
First, the investor should choose a mutual fund that matches their financial goals and ability to tolerate risk.
The investor must complete the required Know Your Customer (KYC) verification process.
After selecting an eligible mutual fund scheme, they can choose the SIP amount and investment frequency.
A payment mandate can then be established through an authorised investment platform, mutual fund company or registered intermediary.
Before investing, it is important to review the fund's risk level, expense ratio, investment objective and relevant scheme documents.
Not every mutual fund offers a ₹500 minimum SIP, so the applicable minimum contribution should also be checked.
Five Important Investment Habits for Young Investors
Starting early is useful, but successful long-term financial planning requires more than opening an SIP.
- Maintain an emergency fund: Keep money available for unexpected expenses rather than investing every rupee in market-linked products.
- Avoid unnecessary borrowing: High-interest debt can weaken the benefits of regular investing.
- Increase contributions gradually: Consider raising the SIP amount when income increases.
- Invest according to financial goals: Short-term requirements and long-term retirement savings may need different investment approaches.
- Review investments periodically: Check whether the chosen fund continues to match your goals without reacting to every market fluctuation.
Consistency can help investors develop better financial habits, but it cannot eliminate investment risk.
Is SIP Investment Safe for Beginners?
An SIP is an investment method, not a guarantee of safety.
The risk depends on the mutual fund selected.
Equity mutual funds generally involve greater market volatility because they invest primarily in shares.
Debt mutual funds have different risks, including interest-rate and credit risks.
Hybrid funds combine different asset classes, but their risk levels also vary.
Young investors should avoid assuming that every mutual fund will produce the same returns.
They should also understand that past performance does not guarantee future results.
Why Long-Term Investing Matters More Than Starting With a Large Amount
Many young people delay investing because they believe they need a high salary to begin.
However, starting with a manageable amount can help establish financial discipline.
A ₹500 SIP may not create enormous wealth immediately, but it introduces the habit of saving and investing regularly.
As earnings improve, increasing the contribution amount can help accelerate progress toward long-term financial goals.
The important factors are the amount invested, the investment duration, the returns achieved and the consistency of contributions.
SIP Investment 2026: Final Takeaway for Gen Z
A monthly SIP of ₹500 can be a practical starting point for young investors who want to build long-term savings.
At an illustrative 12% annual return, a fixed ₹500 monthly SIP could grow to approximately ₹17.47 lakh over 30 years.
Increasing contributions annually through a step-up SIP may produce a substantially larger corpus.
However, becoming a crorepati is not guaranteed simply by starting a ₹500 SIP. Reaching that milestone depends on investment duration, contribution increases and actual market performance.
For Gen Z, the most useful approach is to start with an affordable amount, understand the risks and increase investments as financial circumstances improve.
Disclaimer: Mutual fund investments are subject to market risks. All returns and calculations in this article are illustrative, not guaranteed. Investors should read the relevant scheme documents and consider professional financial advice before investing.