Business
School Fee Payment 2026: UPI, Debit Card or Credit Card? Compare Charges and Find the Cheapest Option
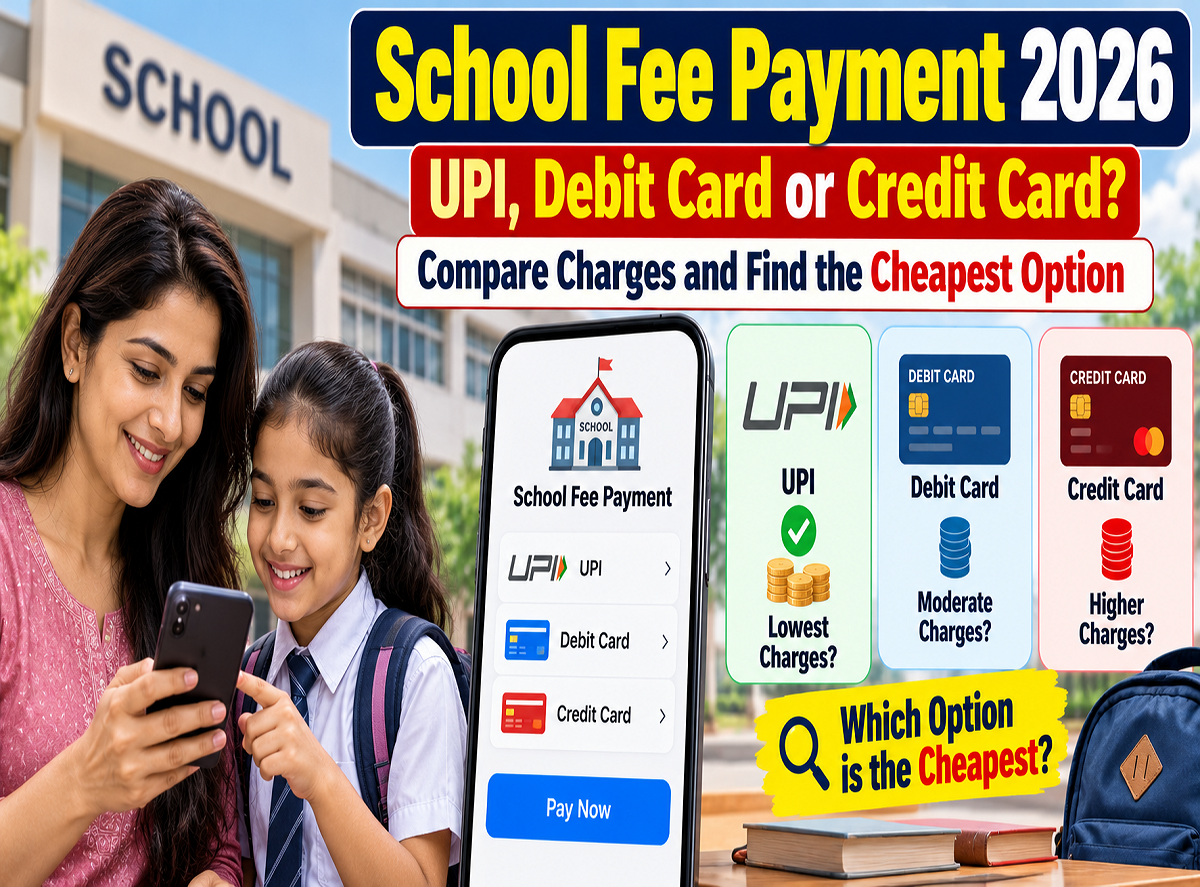
School Fees Payment Rules 2026: Paying school fees online has become increasingly convenient for parents across India. Most educational institutions now accept digital payments through UPI, debit cards, credit cards, and online payment gateways. However, choosing the wrong payment method could result in additional charges, especially when paying substantial amounts such as quarterly or annual school fees.
Recent discussions about merchant transaction charges have raised questions about whether parents should use UPI, debit cards, or credit cards to minimise payment costs.
A report published on October 22, 2026, highlights different charges associated with these payment methods, including Merchant Discount Rate (MDR) and convenience fees.
While UPI payments made directly from bank accounts are often the most economical option, the final cost depends on the school's payment arrangements, the payment gateway, and whether additional charges are passed on to parents.
Here is a detailed comparison to help families understand the potential costs before making their next school fee payment.
School Fee Payment: Why Do Some Online Transactions Cost Extra?
When parents pay school fees digitally, the transaction may involve a bank, payment gateway, card network, or other payment service provider.
These organisations facilitate the transfer of money from the payer to the educational institution.
Depending on the payment method, the service provider may charge the school or merchant a processing fee.
One commonly used term is Merchant Discount Rate (MDR).
MDR refers to the fee charged to a merchant for accepting certain digital payments.
However, MDR and convenience fees are not the same.
MDR is generally associated with the merchant's payment acceptance cost, while a convenience fee is an additional amount that a school or payment platform may separately charge the payer, subject to applicable rules and disclosures.
Therefore, even when a payment method involves an MDR, parents do not necessarily have to pay that amount themselves.
UPI School Fee Payment: Is It the Cheapest Option?
UPI has become one of India's most widely used digital payment systems because it allows users to transfer money directly between bank accounts.
Parents can often pay school fees by scanning an authorised QR code, entering the school's UPI ID, or selecting UPI on an official fee payment portal.
For standard bank-account-based UPI payments, the payer generally does not face a direct UPI transaction charge.
However, the supplied report refers to a new merchant fee structure said to have taken effect on October 15, 2026.
It describes the following charges:
- Merchant transactions up to ₹2,000: No MDR.
- Merchant transactions above ₹2,000: Reported MDR of 0.4%.
- Larger transactions: Reported MDR capped at ₹300.
These reported charges should not be interpreted as an automatic fee imposed on every parent making a bank-account-based UPI payment.
The applicability of any merchant fee depends on the official rules, payment instrument, transaction category, and service-provider arrangements.
Importantly, the reported October 2026 MDR structure has not been independently verified against an official NPCI notification for this article.
How Much Could a 0.4% Merchant Fee Amount To?
If a 0.4% fee were applicable to a particular merchant transaction and capped at ₹300, the calculation would look like this:
| School Fee Amount | Illustrative 0.4% Fee | Fee After ₹300 Cap |
|---|---|---|
| ₹2,000 | ₹8 | ₹0 under the reported exemption |
| ₹5,000 | ₹20 | ₹20 |
| ₹10,000 | ₹40 | ₹40 |
| ₹25,000 | ₹100 | ₹100 |
| ₹50,000 | ₹200 | ₹200 |
| ₹75,000 | ₹300 | ₹300 |
| ₹1,00,000 | ₹400 | ₹300 |
This table illustrates the fee structure described in the source report. It does not establish that these charges apply to ordinary bank-linked UPI payments or that parents must pay them.
For example, a 0.4% charge on ₹50,000 works out to ₹200.
However, if the merchant absorbs the processing cost, the parent may still pay only the original school fee amount.
This is why it is essential to check the final payable amount displayed by the school's official payment portal.
Debit Card School Fee Payment: What Charges Can Apply?
Debit cards are another commonly accepted method for paying school fees.
When parents use a debit card, the transaction amount is generally deducted directly from their linked bank account.
Unlike credit cards, debit cards do not normally create a separate borrowing obligation for the purchase.
However, card-based transactions can involve payment processing costs.
The source report refers to merchant charges of approximately 0.90% for certain debit card transactions.
The actual rate can differ depending on the applicable regulatory framework, card network, merchant category, and payment service provider.
RuPay debit cards also have specific zero-MDR arrangements under applicable government policy.
Nevertheless, a zero-MDR arrangement does not necessarily prevent a separate payment platform from displaying other permitted charges.
Parents should therefore review the final payment summary rather than assuming that every debit card transaction will be free of additional fees.
Credit Card School Fee Payment: Why Can It Be More Expensive?
Credit cards allow parents to pay school fees immediately and settle the amount later through their credit card bill.
This can be useful for managing short-term cash flow, especially when a large school fee payment falls due before the next salary credit.
However, credit card payments may involve higher processing or convenience fees.
According to the supplied report, some platforms charge approximately 2% to 2.5% extra for school fee payments made through credit cards.
For a ₹1 lakh school fee payment, this could mean an additional ₹2,000 to ₹2,500 before considering any applicable taxes on the fee.
The actual charge varies by school, payment platform, and card issuer.
Some credit cards may also exclude educational transactions from rewards or impose separate charges for specific payment categories.
Therefore, parents should verify both the school's convenience fee and their card issuer's terms before paying.
UPI vs Debit Card vs Credit Card: Full Cost Comparison
Consider a family that needs to pay ₹1,00,000 in school fees.
The following table illustrates how different payment methods could affect the final amount.
| Payment Method | Illustrative Additional Charge | Total Payment |
|---|---|---|
| Bank-Linked UPI With No Added Fee | ₹0 | ₹1,00,000 |
| UPI With Reported 0.4% Capped Merchant Fee Passed On | ₹300 | ₹1,00,300 |
| Debit Card With 0.90% Fee Passed On | ₹900 | ₹1,00,900 |
| Credit Card With 2% Convenience Fee | ₹2,000 | ₹1,02,000 |
| Credit Card With 2.5% Convenience Fee | ₹2,500 | ₹1,02,500 |
These are illustrative scenarios, not universal charges. Actual fees, applicable taxes, and payment restrictions may differ.
The comparison shows why parents should examine the total payable amount before completing a transaction.
A payment method that appears convenient may become more expensive if the platform adds a percentage-based charge.
Can Credit Card Rewards Offset the Convenience Fee?
Some parents prefer credit cards because they offer reward points, cashback, or other benefits.
However, rewards do not automatically make credit card school fee payments economical.
Suppose a parent pays ₹1 lakh in school fees and incurs a 2% convenience fee.
The additional cost would be ₹2,000.
If the credit card offers eligible cashback worth only ₹500, the parent would still face a net additional cost of ₹1,500, excluding any applicable taxes.
Moreover, many credit card issuers apply restrictions to education-related transactions.
Before using a credit card, parents should check whether school fee payments qualify for rewards and whether any transaction-specific charges apply.
What Happens If You Miss a Credit Card Payment?
Credit card payments can provide temporary flexibility, but they also create a repayment obligation.
If the cardholder does not pay the required bill amount by the due date, interest and other charges may apply according to the card issuer's terms.
Failure to clear the full outstanding balance can also affect the interest-free period for eligible transactions.
Repeated late payments may negatively affect a person's credit profile.
For this reason, using a credit card solely to postpone school fee payments may become expensive if repayment is uncertain.
Parents should consider credit cards only when they understand the full cost and can manage the repayment responsibly.
How to Avoid Extra Charges While Paying School Fees
Parents can take several practical steps to reduce unnecessary payment expenses.
Check the official school payment portal: Always review the amount shown on the final payment screen before authorising a transaction.
Compare available methods: A school may charge different fees for UPI, debit cards, credit cards, and net banking.
Look for direct bank transfer options: Some institutions permit payments through NEFT, RTGS, IMPS, or other approved bank transfer arrangements. Applicable charges should be checked separately.
Review convenience fees: If an additional amount appears, determine whether it is a payment gateway fee, platform charge, or another disclosed cost.
Verify credit card benefits: Check whether the transaction earns rewards and whether those benefits exceed the additional payment charges.
Keep the payment receipt: Save the transaction reference number and official school receipt to resolve any payment-related disputes.
Parents should also avoid transferring money to unverified QR codes or personal accounts claiming to collect school fees.
Which Payment Method Should Parents Choose?
For most families, the most economical payment method is the one that allows the school fee to be paid without additional charges.
A direct bank-linked UPI payment can be a convenient option when the school accepts it without a separate convenience fee.
Debit cards may also be cost-effective when the institution does not pass payment processing charges to parents.
Credit cards can provide repayment flexibility, but their convenience fees and potential interest costs should be carefully considered.
The best choice therefore depends on the total amount payable, rather than the payment method alone.
Final Word
UPI, debit cards, and credit cards all provide convenient ways to pay school fees, but their costs can differ significantly.
While bank-account-based UPI payments are generally a low-cost option for consumers, schools and payment platforms may have different arrangements for collecting fees.
Debit card transactions can involve merchant processing costs, while credit card payments may attract convenience fees that become substantial for large payments.
Before paying school fees, parents should compare the final payable amount across available options, check for any disclosed convenience charges, and choose the method that offers the lowest overall cost.
Disclaimer: This article is for general financial awareness. The October 2026 merchant fee figures mentioned in the source report have not been independently confirmed against official NPCI documentation. Illustrative calculations do not represent mandatory charges for all transactions. Actual costs depend on the school, payment service provider, card issuer, and applicable regulations.
Lead with the cheapest payment choiceRemove repeated fee disclaimers