Business
Post Office MIS Scheme 2026: Invest ₹15 Lakh and Earn ₹9,250 Every Month, Check Interest Rate and Rules
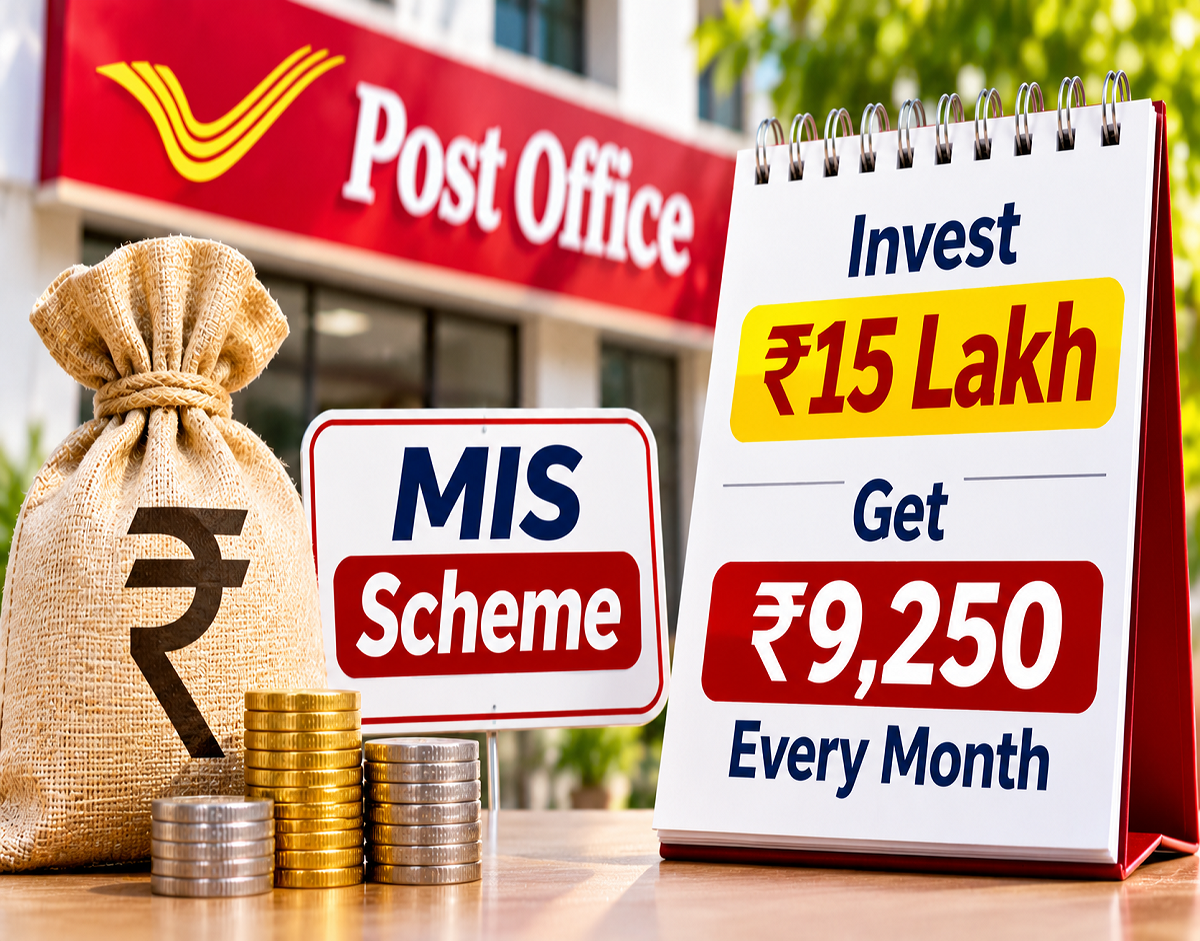
Post Office Monthly Income Scheme 2026: Are you looking for a reliable source of monthly income without exposing your savings to stock market fluctuations? The Post Office Monthly Income Scheme (POMIS) offers an alternative for individuals who prefer predictable interest payments and government-backed savings products.
Under the scheme's reported annual interest rate of 7.4%, a joint investment of ₹15 lakh can generate ₹9,250 every month. Over the five-year maturity period, investors can receive ₹5.55 lakh in total interest, while the original deposit is repayable at maturity, subject to the scheme's rules.
However, there is an important condition: a single investor cannot deposit ₹15 lakh in an MIS account. The maximum investment permitted in an individual account is ₹9 lakh, while a joint account can hold up to ₹15 lakh.
Before opening an account, investors should understand the deposit limits, monthly interest calculations, premature withdrawal penalties and tax implications.
Post Office Monthly Income Scheme 2026: Key Features
| Particulars | Details |
|---|---|
| Scheme Name | Post Office Monthly Income Scheme (POMIS) |
| Annual Interest Rate | 7.4% |
| Minimum Investment | ₹1,000 |
| Maximum Single Account Deposit | ₹9 lakh |
| Maximum Joint Account Deposit | ₹15 lakh |
| Account Maturity | 5 years |
| Interest Payment | Monthly |
| Maximum Joint Account Holders | 3 adults |
| Premature Closure | Permitted after one year, subject to deductions |
| Tax on Interest | Taxable according to applicable rules |
| Section 80C Benefit | Not available on MIS deposits |
How Much Monthly Income Will You Get From ₹15 Lakh?
The main attraction of the Post Office MIS is its regular monthly interest payout.
At an annual interest rate of 7.4%, the calculation for a ₹15 lakh joint deposit is straightforward.
MONTHLY INCOME ON ₹15 LAKH
₹9,250
At 7.4% annual interest, before applicable income tax
Annual Interest
₹1,11,000
Total Interest in 5 Years
₹5,55,000
Principal at Maturity
₹15,00,000
Total Cash Received Over 5 Years
₹20,55,000
The monthly interest is calculated as follows:
\[ \frac{₹15,00,000 \times 7.4\%}{12}=₹9,250 \]
This means eligible joint account holders can collectively receive ₹9,250 per month, provided the account carries the stated interest rate and remains active for the full term.
The ₹20.55 lakh figure represents the sum of all monthly interest payments and the principal returned at maturity. It is not a single lump-sum maturity payment.
Post Office MIS Calculator: Monthly Returns on Different Investments
The monthly payout depends on the amount deposited.
Calculate Your Monthly Income
7.4% p.a.
Investment amount
₹9,00,000
₹1,000₹15 lakh
Monthly interest
₹5,550
Five-year interest
₹3,33,000
Illustrative gross interest based on the stated 7.4% rate, without reinvestment. Actual monthly payouts may involve rounding.
For quick comparison, here are the approximate monthly returns on common deposit amounts.
| Investment | Monthly Interest | Annual Interest |
|---|---|---|
| ₹1 lakh | ₹617 | ₹7,400 |
| ₹3 lakh | ₹1,850 | ₹22,200 |
| ₹5 lakh | ₹3,083 | ₹37,000 |
| ₹7 lakh | ₹4,317 | ₹51,800 |
| ₹9 lakh | ₹5,550 | ₹66,600 |
| ₹12 lakh | ₹7,400 | ₹88,800 |
| ₹15 lakh | ₹9,250 | ₹1,11,000 |
Amounts above ₹9 lakh require an eligible joint account structure.
Can One Person Invest ₹15 Lakh in Post Office MIS?
No. The investment ceiling depends on the type of account.
A single account holder can deposit a maximum of ₹9 lakh under the scheme.
For a joint account, the maximum permitted deposit is ₹15 lakh. Up to three adults can hold a joint MIS account.
An important rule is that each joint account holder's share is considered equal when determining individual investment limits.
For example, a ₹15 lakh account held jointly by two adults represents a ₹7.5 lakh share for each person.
If three adults jointly hold the same account, the share attributable to each is ₹5 lakh.
An individual cannot bypass the overall investment limit by opening multiple MIS accounts at different post offices.
Five Important Rules Investors Should Know
1. The Investment Limit Applies Across Accounts
The ₹9 lakh individual holding limit must be considered across a person's MIS investments, including their proportionate share in joint accounts.
Opening additional accounts does not automatically increase the permitted individual exposure.
2. The Maturity Period Is Five Years
Post Office MIS accounts have a five-year maturity period.
Investors should select the scheme only after considering whether they can keep the principal invested for the required period.
3. Withdrawal Is Restricted During the First Year
The scheme does not normally allow premature closure before one year from the date of deposit.
This makes it unsuitable for money that may be required immediately for emergencies.
4. Early Closure Can Reduce Your Principal
If an account is closed after the first year but before completing three years, 2% of the principal is deducted.
For closure after three years but before five years, the deduction is 1%.
5. Monthly Interest Does Not Automatically Compound
The scheme is designed to distribute interest every month rather than accumulate it within the MIS account.
Unclaimed monthly interest does not earn additional interest under the scheme.
Post Office MIS Premature Withdrawal: How Much Could You Lose?
Investors should understand the financial consequences of closing an account before maturity.
For a ₹15 lakh deposit, the standard premature closure deductions would be:
| Closure Period | Deduction | Principal Returned |
|---|---|---|
| Before 1 year | Normally not permitted | — |
| After 1 year but before 3 years | 2% = ₹30,000 | ₹14,70,000 |
| After 3 years but before 5 years | 1% = ₹15,000 | ₹14,85,000 |
| At 5-year maturity | No premature closure deduction | ₹15,00,000 |
These figures relate to the principal. Monthly interest already paid and other applicable account rules must be considered separately.
Is Post Office MIS Interest Tax-Free?
No. Interest earned through the Post Office Monthly Income Scheme is generally taxable according to the investor's applicable income tax provisions.
The tax liability depends on the account holder's overall taxable income and tax regime.
The principal deposited under MIS does not qualify for the deduction under Section 80C of the Income-tax Act.
For example, an eligible joint account generating ₹1,11,000 in annual interest does not necessarily mean one person must report the entire amount as their own income. Tax treatment depends on beneficial ownership and applicable income tax rules.
Investors should consult a qualified tax professional when necessary.
Who Can Benefit From the Post Office Monthly Income Scheme?
The scheme may appeal to people who prefer regular income over market-linked investment growth.
Retired individuals, pensioners, conservative savers and households seeking supplementary monthly cash flow may find the payout structure useful.
For example, a retired couple with an eligible ₹15 lakh joint investment could receive ₹9,250 per month before taxes.
That amount may help meet recurring household expenses such as groceries, utility bills or other regular payments.
However, investors should remember that inflation can reduce the purchasing power of a fixed monthly income over time.
How to Open a Post Office MIS Account
Eligible investors can approach a post office offering the scheme and complete the required account-opening formalities.
Generally, the process involves selecting the appropriate account type, submitting the prescribed application, completing identity verification and depositing the investment amount through an accepted payment method.
Applicants should keep the required KYC documents and relevant account information ready.
The post office can confirm the currently accepted documents, payment methods and account-opening requirements.
For official scheme information, visit India Post or the National Savings Institute.
Post Office MIS vs Bank Fixed Deposit: What Is the Difference?
Both Post Office MIS and bank fixed deposits can provide predictable interest income, but their structures differ.
| Feature | Post Office MIS | Bank Fixed Deposit |
|---|---|---|
| Interest Payment | Monthly | Monthly, quarterly, cumulative or other options |
| Investment Term | 5 years | Depends on selected FD |
| Interest Rate | Scheme rate fixed at opening | Depends on bank and deposit |
| Investment Limit | ₹9 lakh single, ₹15 lakh joint | Depends on bank and product |
| Premature Withdrawal | Scheme-specific deductions | Bank-specific conditions |
| Main Objective | Regular monthly income | Income or capital accumulation |
The most suitable option depends on an investor's liquidity requirements, tax situation and financial goals.
Conclusion
The Post Office Monthly Income Scheme offers a structured way to receive monthly interest from a government-backed savings product.
At the reported annual rate of 7.4%, a ₹15 lakh joint investment generates ₹9,250 every month, equivalent to ₹1,11,000 annually.
Over five years, the total gross interest amounts to ₹5.55 lakh, while the original ₹15 lakh deposit is repayable at maturity under the applicable rules.
However, investors must remember that the ₹15 lakh limit applies to eligible joint accounts, while the maximum individual holding is ₹9 lakh.
Before investing, compare the available interest rate, tax implications, premature closure deductions and your need for emergency funds.
Disclaimer: This article is intended for general financial information and does not constitute personalised investment advice. Interest rates for new deposits may change following government notifications. Consult a qualified financial adviser before making investment decisions.