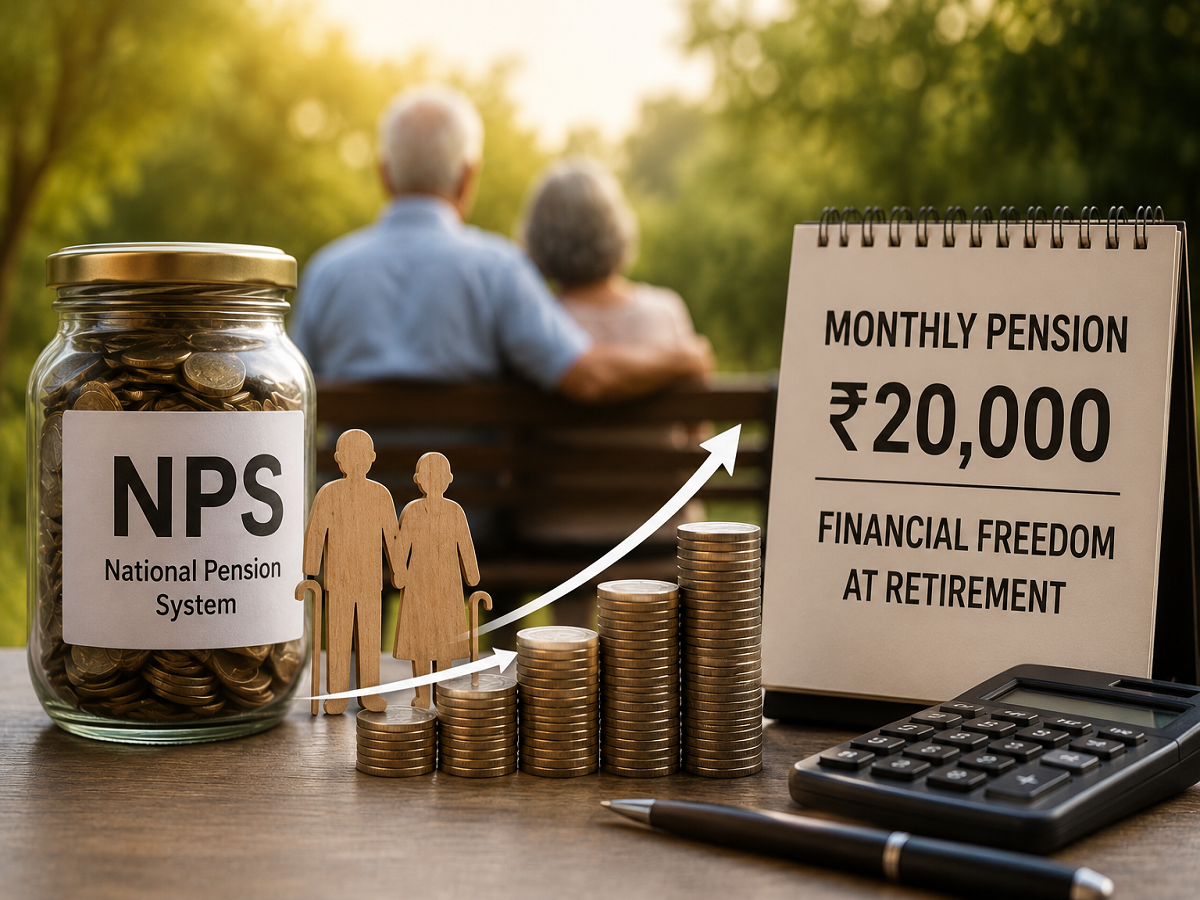
Building a regular source of income after retirement is one of the most important parts of long-term financial planning. The National Pension System (NPS) is widely used for this purpose, allowing subscribers to build a retirement corpus through long-term investments across different asset classes.
But how much money should you accumulate in NPS if your target is a pension of ₹20,000 every month after turning 60?
The answer is not the same for everyone. It depends largely on how much of the accumulated NPS corpus is used to purchase an annuity and how much is taken out as a lump sum at retirement.
Using an assumed annuity rate of 6% per annum, a ₹20,000 monthly pension would require an annuity corpus of approximately ₹40 lakh. However, if you also want to withdraw 60% of your retirement savings as a lump sum while generating the same pension from the remaining 40%, the total corpus requirement rises substantially.
Here's how the calculation works.
How Much Money Is Needed for a ₹20,000 Monthly Pension?
A pension of ₹20,000 per month means annual pension income of:
₹20,000 × 12 = ₹2.40 lakh per year
Assuming an annuity pays around 6% annually, the corpus required to generate ₹2.40 lakh a year would be approximately:
₹2.40 lakh ÷ 6% = ₹40 lakh
Therefore, around ₹40 lakh would need to be used to purchase the annuity under this illustrative calculation.
The final pension, however, depends on the actual annuity rate and annuity option available at retirement.
Scenario 1: Using the Entire ₹40 Lakh for Annuity
Consider a subscriber who wants to maximise pension income and does not need a lump-sum withdrawal at retirement.
If the entire retirement corpus is used to purchase an annuity, the calculation based on a 6% annual annuity rate would be:
Total retirement corpus: ₹40 lakh
Amount used for annuity: ₹40 lakh
Lump-sum withdrawal: Nil
Assumed annuity rate: 6% annually
Estimated pension: ₹20,000 per month
In this illustration, a ₹40 lakh corpus may be sufficient to produce the targeted ₹20,000 monthly pension because the entire amount is being directed towards the annuity.
However, the retiree would not receive a separate lump-sum amount under this example.
Scenario 2: Want ₹60 Lakh Cash Plus ₹20,000 Monthly Pension?
The calculation changes considerably when a subscriber wants both a lump-sum amount and regular pension income.
Suppose the investor wants to use only 40% of the total retirement corpus for annuity and withdraw the remaining 60% as a lump sum.
If ₹40 lakh must represent 40% of the total corpus, the required overall retirement fund would be:
Total NPS corpus: ₹1 crore
Its illustrative division would be:
40% for annuity: ₹40 lakh
60% lump-sum component: ₹60 lakh
Estimated monthly pension at 6% annuity: ₹20,000
This means that someone targeting both a sizeable lump sum and a ₹20,000 monthly pension would need a much larger retirement corpus than someone who puts the entire corpus into an annuity.
₹40 Lakh or ₹1 Crore: Which Target Applies to You?
The difference between the two targets comes down to how you plan to use your retirement savings.
If your only objective is to generate the maximum possible pension from the accumulated amount and you are willing to direct the entire ₹40 lakh towards an annuity, the smaller corpus may meet the ₹20,000 monthly pension target under the 6% assumption.
But if you want ₹60 lakh available as a lump sum while simultaneously using ₹40 lakh to generate pension income, your overall target becomes ₹1 crore.
This distinction is important when setting an NPS retirement goal.
How Much Should You Invest Every Month to Build ₹1 Crore?
Starting early can significantly reduce the monthly amount needed to reach a large retirement target.
Assuming an average annual return of 10% during the accumulation period, the source calculation estimates the following monthly investments for building a ₹1 crore corpus by age 60:
| Starting Age | Time Until 60 | Approx. Monthly Investment |
|---|---|---|
| 25 years | 35 years | ₹2,630 |
| 30 years | 30 years | ₹4,450 |
| 35 years | 25 years | ₹7,750 |
| 40 years | 20 years | ₹13,170 |
The difference is striking.
Someone beginning at 25 has 35 years for contributions and investment growth to work together. A person beginning at 40 has only 20 years and therefore needs to contribute substantially more every month to target the same ₹1 crore corpus.
What If Your Goal Is Only ₹40 Lakh?
If the objective is to build ₹40 lakh and eventually use the entire corpus for annuity in this illustration, the estimated monthly contribution is much lower.
Using the same assumed 10% annual return:
| Starting Age | Investment Period | Approx. Monthly Investment |
|---|---|---|
| 25 years | 35 years | ₹1,050 |
| 30 years | 30 years | ₹1,780 |
| 35 years | 25 years | ₹3,100 |
| 40 years | 20 years | ₹5,270 |
Again, starting earlier dramatically reduces the monthly contribution required.
Why Starting NPS Early Can Make a Big Difference
The biggest advantage available to a young retirement investor is time.
A person starting at 25 does not necessarily need a huge monthly contribution because the investment gets several decades to potentially compound.
Waiting another 10 or 15 years means losing a significant portion of that compounding period. As a result, the monthly investment needed to achieve the same target rises sharply.
For instance, according to the illustration, building ₹1 crore could require around ₹2,630 per month when starting at 25. Starting at 40 increases the estimated requirement to around ₹13,170 per month.
That is more than five times the monthly contribution for the same target.
NPS Offers a Mix of Different Asset Classes
NPS allows subscribers to build their retirement savings using a combination of investment categories, including equities, corporate debt and government securities.
Investors can choose between different asset-allocation approaches depending on the available NPS options and applicable rules.
This flexibility can help subscribers align their retirement portfolio with factors such as age, risk appetite and investment horizon.
However, NPS returns during the accumulation stage are market-linked. A 10% annual return, as used in the calculations above, is only an assumption and should not be considered guaranteed.
Tax Benefits Can Add to the Appeal of NPS
Tax treatment is another factor that has historically made NPS attractive for some investors.
The source article notes an additional deduction of up to ₹50,000 under Section 80CCD(1B), beyond the ₹1.5 lakh limit associated with Section 80C, subject to the tax rules applicable to the taxpayer.
However, tax benefits can depend on the tax regime selected and the prevailing income-tax provisions. Investors should therefore check the latest rules before making a contribution primarily for tax-saving purposes.
Your Actual Pension May Be Different
The ₹20,000 monthly pension calculation is based on an assumed annuity rate of 6%.
Actual annuity income at retirement can vary depending on several factors, including prevailing annuity rates, the annuity provider and the type of annuity option selected.
Similarly, the calculations for reaching ₹40 lakh or ₹1 crore assume an average 10% annual return during the NPS accumulation period. Since NPS investments are market-linked, actual returns can be higher or lower.
Therefore, these figures should be treated as planning illustrations rather than guaranteed outcomes.
The Earlier You Start, the Easier the Retirement Target Can Become
The most important takeaway from this calculation is not simply whether you need ₹40 lakh or ₹1 crore.
It is the impact that time can have on retirement planning.
If your goal is to receive around ₹20,000 every month after retirement, first decide how much money you want to keep available as a lump sum and how much you are comfortable allocating towards an annuity.
Once the required corpus is estimated, working backwards from age 60 can help determine how much you need to invest regularly.
Starting early may allow a comparatively modest monthly contribution to grow into a substantial retirement fund over several decades, while delaying retirement planning could require a much larger investment later.
Disclaimer: The calculations above are illustrative and use assumed annual returns of 10% during accumulation and a 6% annuity rate at retirement. NPS returns are market-linked, while actual pension income depends on prevailing annuity rates, the annuity option selected and applicable NPS rules. Tax treatment may also change. Investors should verify current regulations and consider professional financial advice before making investment decisions.