Technology
UPI Charges 2026: Customers Continue to Pay Zero Fees, P2P Transfers Free and Merchants Get Relief Up to ₹2,000
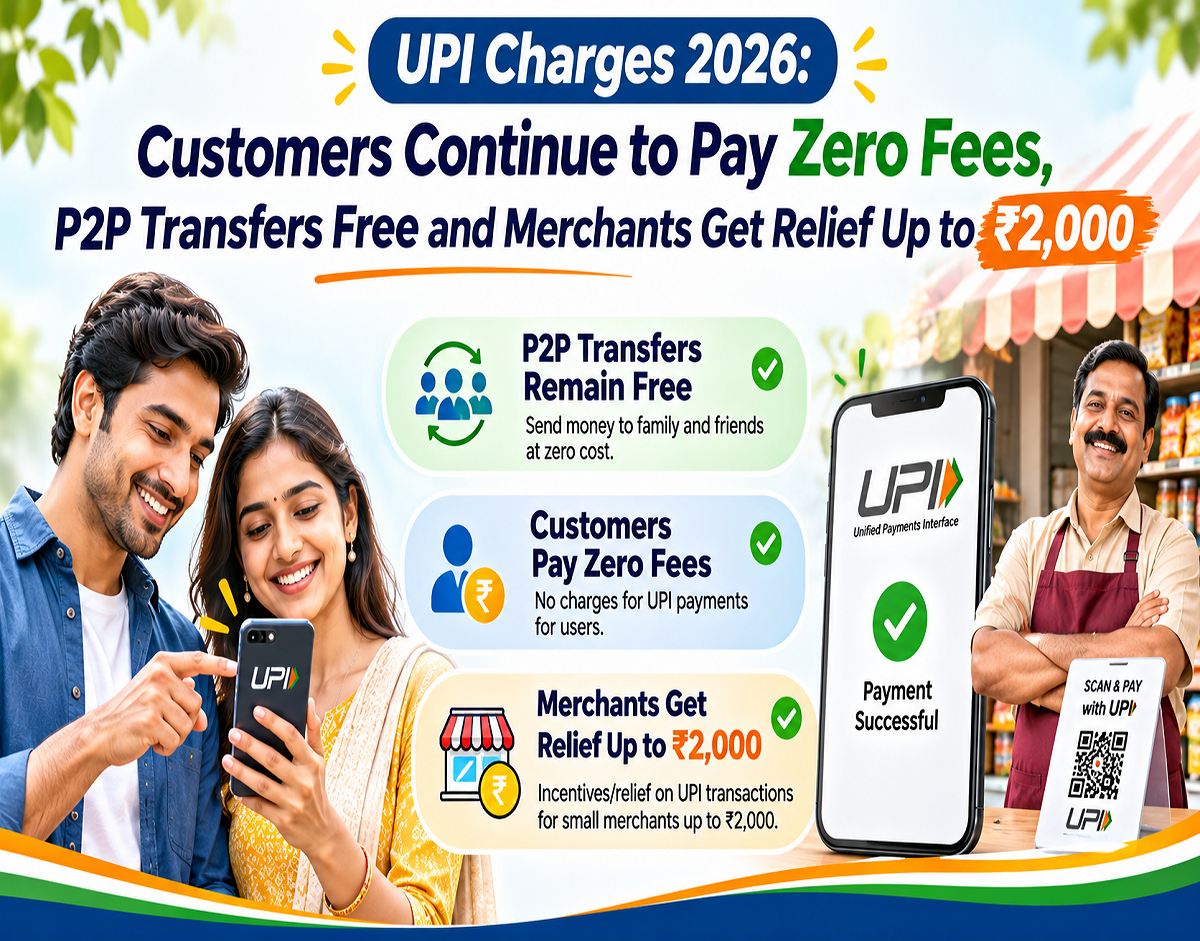
UPI Transaction Charges 2026: Digital payment users have received an important clarification regarding charges on Unified Payments Interface (UPI) transactions. According to the latest information, UPI transactions remain free for customers, person-to-person (P2P) transfers continue without transaction charges, and merchants do not have to pay merchant charges on eligible transactions up to ₹2,000.
The clarification is relevant to millions of people who use UPI applications for everyday payments, including shopping, mobile recharges, bill payments and money transfers.
However, it is important to distinguish between charges paid by customers and merchant discount rates (MDR) or other fees that may apply to particular merchant payment arrangements.
Are UPI Transactions Free for Customers?
The latest clarification states that UPI transactions remain free for customers.
This means ordinary users making standard UPI payments are not charged a transaction fee simply for sending money through their linked bank accounts.
Whether someone transfers money to a family member or pays a shopkeeper through a standard bank-account-based UPI transaction, the customer does not ordinarily pay a UPI transaction charge.
The clarification does not mean that every financial service offered through a payment application is free.
Some separate services, funding methods or financial products may have their own terms and charges.
P2P UPI Transactions Continue to Be Free
Person-to-person transactions are among the most widely used features of UPI.
A P2P transaction occurs when one individual transfers money directly to another individual.
Examples include sending money to a friend, transferring funds to a family member or sharing household expenses.
The latest statement confirms that P2P UPI transactions continue to be free.
This is an important distinction because discussions about merchant payment charges should not be confused with charges on ordinary personal transfers.
What Is the ₹2,000 Rule for Merchants?
The clarification also states that eligible merchant transactions up to ₹2,000 remain free for merchants.
This refers to the applicable merchant-side charging arrangement.
A merchant is a business or seller accepting digital payments for goods or services.
For example, if a customer makes an eligible UPI payment of ₹500 or ₹1,500 to a shop, the transaction falls within the ₹2,000 threshold mentioned in the statement.
However, the treatment of payments above ₹2,000 depends on the applicable rules and payment arrangement.
It would be incorrect to conclude that every merchant payment exceeding ₹2,000 automatically attracts a charge.
What Is Merchant Discount Rate?
Merchant Discount Rate, commonly called MDR, is a fee associated with certain digital payment acceptance arrangements.
It is generally paid by merchants or businesses to payment service providers, depending on the transaction type and applicable rules.
MDR should not be confused with a fee charged directly to a customer.
The latest UPI clarification specifically distinguishes between free customer transactions and the treatment of eligible merchant payments.
The actual merchant charging rules can vary according to the payment instrument and applicable regulatory framework.
UPI Charges 2026: Important Points
| Transaction category | Clarification |
|---|---|
| Standard UPI transactions by customers | Free for customers |
| Person-to-person UPI transfers | Free |
| Eligible merchant transactions up to ₹2,000 | Free for merchants |
| Merchant transactions above ₹2,000 | Depends on applicable payment rules and arrangements |
| Other payment services or instruments | Separate terms may apply |
Consumers and merchants should rely on official payment service information when assessing any specific charge.
Why Is This Clarification Important?
UPI has become a common method of digital payment across India.
It is used by customers, small retailers, street vendors and larger businesses.
Confusion about possible UPI charges can create uncertainty among both customers and merchants.
A clear distinction between customer fees and merchant-side charges helps users understand how digital payments work.
For consumers, the key point is that ordinary UPI transfers remain free.
For merchants, the charging treatment depends on the relevant transaction category and applicable rules.
How to Make Safe UPI Payments
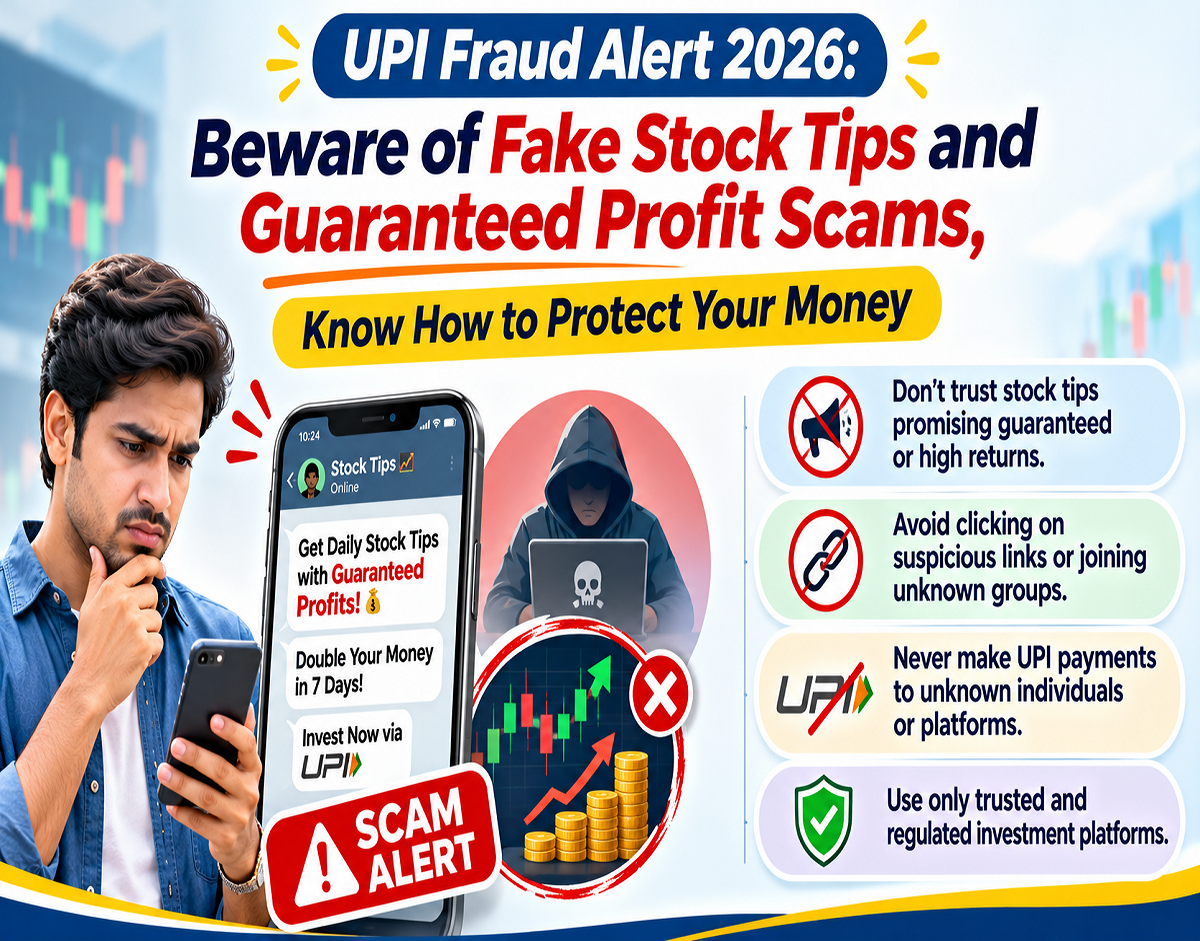
While UPI offers a convenient way to transfer money, users should remain alert to digital payment fraud.
Always verify the recipient's name before approving a transaction.
Never share your UPI PIN with anyone.
Remember that receiving money through a standard UPI transfer does not require entering your UPI PIN.
Be cautious of unknown callers asking you to scan QR codes or approve payment requests to receive refunds or prizes.
If you notice an unauthorised transaction, contact your bank or payment service provider immediately.
Financial cybercrime can also be reported through the national cybercrime helpline at 1930.
Conclusion
The latest clarification provides reassurance to UPI users that standard customer transactions and person-to-person transfers remain free.
Eligible merchant transactions up to ₹2,000 also remain free under the stated arrangement.
However, merchant payment rules should not be confused with customer charges, and payments above ₹2,000 should not automatically be assumed to attract fees.
Consumers and businesses should check official information for the conditions applicable to their particular payment methods.
Source Credit: Public clarification concerning UPI transaction charges and merchant payment arrangements, November 2026.
Official NPCI Website: https://www.npci.org.in/
Disclaimer: This article explains the supplied UPI charging clarification. Specific merchant fees may depend on the payment instrument, transaction category and applicable regulatory provisions. The statement does not establish that every payment-related service is free.