
Business
SIP Calculator: How Long Can a ₹5,000 Monthly Investment Take to Reach ₹1 Crore at 10%, 12% and 15%?
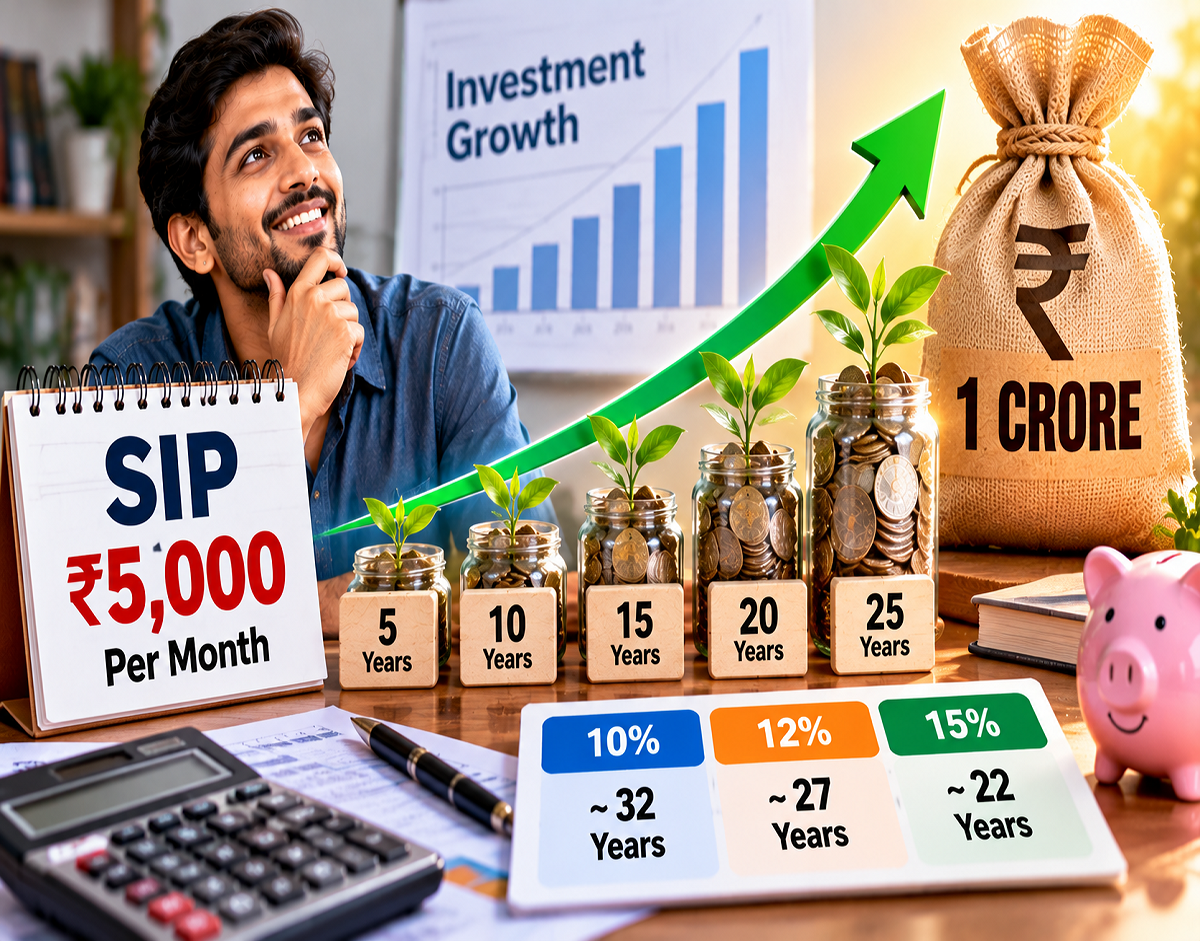
Building a ₹1 crore investment corpus may seem difficult when you can invest only a few thousand rupees every month. However, a long investment horizon combined with compounding can significantly change the outcome. Even a ₹5,000 monthly Systematic Investment Plan (SIP) could potentially grow to ₹1 crore over time, depending on the returns generated by the investment.
The key question is how long it could take.
Calculations based on assumed annual returns of 10%, 12% and 15% show a substantial difference in the time required to approach the ₹1 crore milestone. At an assumed 10% annual return, it could take nearly 29 years, while a 15% return could reduce the period to roughly 22 years.
These figures are illustrations rather than guaranteed outcomes because mutual fund returns are market-linked and can fluctuate considerably.
₹5,000 Monthly SIP: How Long Could It Take to Build ₹1 Crore?
If an investor consistently contributes ₹5,000 every month, the approximate calculation under different assumed return scenarios looks like this:
| Assumed Annual Return | Approx. Time to Reach ₹1 Crore | Total Amount Invested | Estimated Wealth From Growth |
|---|---|---|---|
| 10% | 28 years 11 months | ₹17.35 lakh | ₹82.65 lakh |
| 12% | 25 years 6 months | ₹15.30 lakh | ₹84.70 lakh |
| 15% | 21 years 11 months | ₹13.15 lakh | ₹86.85 lakh |
The calculation demonstrates why time can be one of the most important elements in long-term investing. A relatively modest monthly contribution can potentially accumulate into a much larger corpus when investment gains are allowed to compound for decades.
At 10% Return, ₹1 Crore Could Take Nearly 29 Years
Suppose an investor starts a monthly SIP of ₹5,000 and the investment generates an average annualised return of 10% over the entire investment period.
Based on the assumed calculation, reaching approximately ₹1 crore could take around 28 years and 11 months.
During this period, the investor would contribute about ₹17.35 lakh from their own pocket.
The remaining approximately ₹82.65 lakh would represent estimated investment growth generated over the period.
This illustrates how the contribution made by the investor can become only a fraction of the eventual corpus when compounding is allowed to work over a sufficiently long horizon.
What If the SIP Generates 12% Annualised Returns?
The picture changes considerably if the assumed annual return increases to 12%.
With the monthly SIP remaining unchanged at ₹5,000, the ₹1 crore target could potentially be reached in approximately 25 years and 6 months.
The investor's cumulative contribution during this period would be around ₹15.30 lakh, while an estimated ₹84.70 lakh could come from investment growth.
Compared with the 10% illustration, the higher assumed return shortens the investment period by more than three years.
However, investors should not assume that a mutual fund will consistently deliver 12% every year. Actual returns can be higher or lower and may include periods of significant market volatility.
At 15%, the Target Could Be Reached in Around 22 Years
A 15% annualised return produces an even more striking illustration.
If a ₹5,000 monthly SIP were to generate an average annual return of 15%, the ₹1 crore target could potentially be achieved in around 21 years and 11 months.
The investor's total contribution would be approximately ₹13.15 lakh, while the estimated investment growth could account for about ₹86.85 lakh of the final corpus.
The calculation looks attractive, but a 15% return should be treated purely as an assumption for illustration. Equity mutual funds do not offer guaranteed returns, and maintaining such a return over more than two decades cannot be assured in advance.
A 5-Percentage-Point Return Difference Can Change the Timeline Sharply
One of the most interesting observations comes from comparing the 10% and 15% scenarios.
The difference between the two assumed annual returns is only 5 percentage points, but the estimated time required to build ₹1 crore changes by roughly seven years.
At 10%, the calculation suggests almost 29 years. At 15%, the same ₹5,000 monthly contribution could theoretically reach the target in about 22 years.
This difference illustrates the effect of compounding: as the investment corpus grows, returns generated on earlier gains can themselves begin generating additional returns.
But investors should be careful not to interpret the example as a reason to chase funds promising or historically showing the highest returns. Higher return potential typically comes with higher investment risk.
Starting Early Can Make a Major Difference
For long-term goals, starting early can be just as important as investing a large amount.
Someone who begins investing in their 20s potentially has several decades available for compounding. A person who starts much later may need to invest substantially more each month to target the same corpus by a particular age.
Consistency can also matter. Interrupting SIPs repeatedly can reduce the amount of capital available to compound over the long term.
Market declines are also a normal part of equity investing. Investors should base decisions on their financial situation, investment horizon and risk tolerance rather than reacting solely to short-term market movements.
Step-Up SIP Could Help Reach the Goal Earlier
A ₹5,000 SIP does not necessarily have to remain at ₹5,000 throughout the investment period.
As income increases, investors can consider increasing their monthly contribution. This approach is commonly referred to as a step-up SIP.
For example, an investor might begin with ₹5,000 per month and gradually increase the SIP contribution each year as salary or business income rises.
A higher contribution means more money is invested and gets additional time to potentially compound. As a result, a step-up strategy could help an investor approach the target sooner than a fixed ₹5,000 SIP, although the actual outcome will continue to depend on market returns.
What Should Investors Check Before Starting an SIP?
Investors should first identify the financial goal for which they are investing and determine how much time they have to reach it. The SIP amount should also be affordable enough to continue through different market cycles without creating pressure on essential household expenses.
Past returns should not be the only factor used to select a mutual fund. Investors should understand the fund's investment strategy, risk profile, expense ratio, portfolio and suitability for their goals.
Periodic reviews can also help determine whether the SIP amount needs to be increased or whether the investment strategy remains aligned with the original objective.
₹1 Crore Is Possible in the Illustration, But Returns Are Not Guaranteed
The calculations demonstrate the potential power of long-term investing. Under the assumptions used, a ₹5,000 monthly SIP could potentially grow to around ₹1 crore in approximately 21 years 11 months to 28 years 11 months, depending on the return generated.
But the biggest qualification is that 10%, 12% and 15% are assumed rates, not promised returns.
Mutual funds are market-linked investments. Actual returns can fluctuate, and the time required to reach ₹1 crore could therefore be shorter or considerably longer than these examples suggest.
For investors, the broader lesson is not that a particular return is guaranteed, but that starting early, investing consistently and gradually increasing contributions as income grows can significantly improve the chances of building a substantial long-term corpus.



