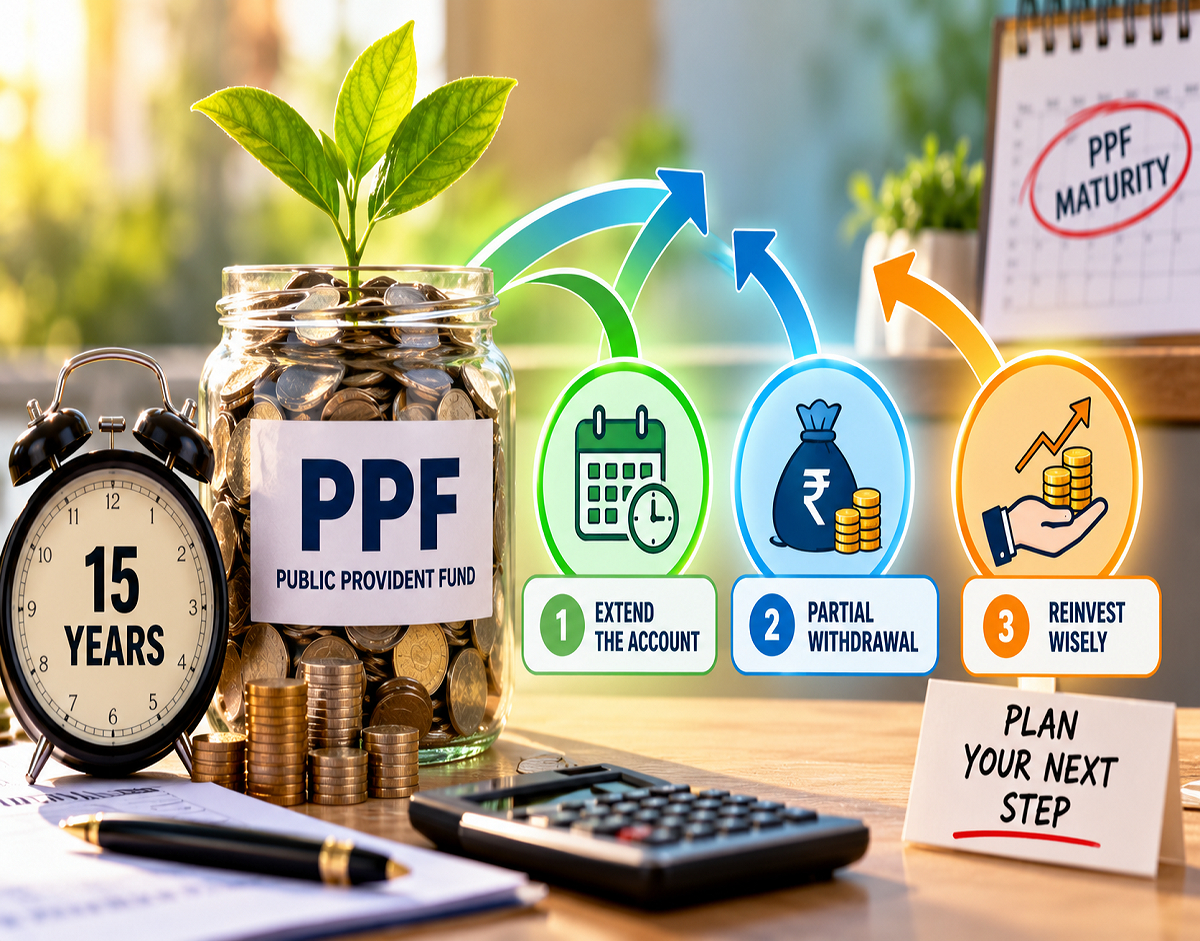
Public Provident Fund (PPF) is widely used for long-term savings because it combines government-backed security with tax benefits and compounded interest. But an important question arises when a PPF account completes its 15-year maturity period: should you withdraw the entire corpus, or can you continue earning interest?
The good news is that maturity does not necessarily mean you have to empty and close your PPF account immediately. Depending on your financial requirements, the rules allow different choices after maturity. You may withdraw the entire amount, keep the balance in the account without making further contributions, or extend the account in five-year blocks while continuing to invest.
PPF is currently offering an annual interest rate of 7.1%, with interest compounded annually. Since the government reviews small-savings interest rates periodically, however, the rate applicable in future periods may change.
Understanding the three post-maturity options can help you decide what to do with your accumulated PPF corpus.
Option 1: Withdraw the Entire PPF Corpus and Close the Account
Once the prescribed maturity period is completed, a PPF subscriber can apply to withdraw the accumulated balance, including principal and applicable interest.
This option may be useful when the money has been accumulated for a specific long-term financial goal.
For example, someone may need the corpus for a child's higher education or marriage, buying a house, retirement expenses or repaying a substantial debt. In such situations, withdrawing the maturity amount may help meet the planned financial requirement.
However, completing 15 years alone does not mean that you must immediately withdraw the money.
If there is no immediate requirement for the corpus, it may be worth considering the other continuation options before closing the account.
Option 2: Keep the Money in PPF Without Making Fresh Contributions
Another option is to leave the accumulated corpus in the PPF account after maturity without making any new contributions.
This can be useful for account holders who no longer want to commit fresh savings to PPF but also do not need the accumulated money immediately.
Under this option, the existing balance can continue earning interest at the PPF rate applicable from time to time. Therefore, if the applicable rate is 7.1%, the balance would earn interest according to that rate until the government revises it.
This approach gives the account holder additional flexibility without requiring fresh annual deposits.
Under the applicable rules for an account continued without further deposits, withdrawals are also permitted subject to the prescribed conditions. This can allow the account holder to retain the remaining corpus while accessing money when needed.
For someone seeking to preserve an existing PPF corpus without committing to additional annual contributions, this can be an important alternative to immediately closing the account.
Option 3: Extend PPF for Five Years and Keep Investing
Those who want to continue saving through PPF can opt to extend the account with fresh contributions.
The account can be extended in blocks of five years. During an extension with contributions, the subscriber can continue making deposits within the prescribed annual PPF limits.
Currently, the minimum annual contribution is ₹500, while the maximum amount that can be deposited in a financial year is ₹1.5 lakh, subject to applicable rules.
This option can be particularly relevant for people who want to continue building their long-term corpus through PPF after completing the original maturity period.
Don't Miss the Deadline for Extension With Contributions
One of the most important points for PPF account holders concerns the procedure for extending an account while continuing to make contributions.
According to the rules cited, an account holder who wants to continue the PPF account with fresh deposits must exercise this option within the prescribed period after maturity by submitting Form 4 to the concerned bank or post office.
The option is generally required to be exercised within one year from maturity for continuation with deposits.
This deadline matters because simply depositing fresh money into a matured PPF account without completing the required extension procedure can create problems.
The article states that deposits made without exercising the extension option within the prescribed period may not qualify for interest or the related tax benefits. Account holders should therefore complete the required formalities before making contributions to an extended account.
Why PPF Maturity Does Not Mean an Immediate Withdrawal Deadline
A common misconception is that completing 15 years means the entire PPF balance must immediately be withdrawn.
Instead, maturity gives the account holder additional choices.
If the accumulated corpus is required for an important financial goal, the account holder can withdraw it. If the money is not immediately needed and no further investment is planned, the balance can be retained under the applicable post-maturity rules.
Alternatively, subscribers who want to keep investing can choose a five-year extension with contributions after completing the required procedure.
Which PPF Option Could Suit Different Needs?
The right decision largely depends on what you need the money for.
If you have a major planned expense, withdrawing the corpus may make sense. If you want to preserve the accumulated savings but do not wish to make new contributions, continuing the account without fresh deposits may provide greater flexibility.
On the other hand, those who still have a long investment horizon and want to continue using PPF for long-term savings can consider extending the account in five-year blocks with contributions.
Remember That the 7.1% Rate Is Not Fixed Forever
While PPF currently offers 7.1% annual interest, subscribers should not assume this rate will remain unchanged throughout an extension period.
The government reviews interest rates on small-savings schemes periodically. Therefore, an extended PPF account earns the rate applicable for the relevant period rather than permanently locking in today's 7.1% rate.
PPF nevertheless continues to offer the advantages provided under its prevailing rules, including government backing and eligible tax treatment.
What to Do When Your PPF Completes 15 Years
The most important takeaway is that PPF maturity does not force you to withdraw your entire savings immediately.
You effectively have three broad choices: take out the maturity proceeds, retain the balance without further contributions, or extend the account in five-year blocks while continuing to invest.
If you choose extension with contributions, make sure the prescribed option is exercised within the required time and the necessary form is submitted to your bank or post office.
Before making a decision, consider your liquidity needs, future financial goals and whether you want to continue contributing to PPF. Also check the latest government rules, applicable interest rate and tax provisions, as these can change over time.
Disclaimer: This article is for general information only and should not be considered investment or tax advice. PPF interest rates, tax provisions, forms and procedural requirements are subject to government rules and amendments. Check the latest official guidelines before making a financial decision.