Business
Kisan Credit Card Offers Affordable Farm Loans: Eligibility, Interest Rate and Application Process
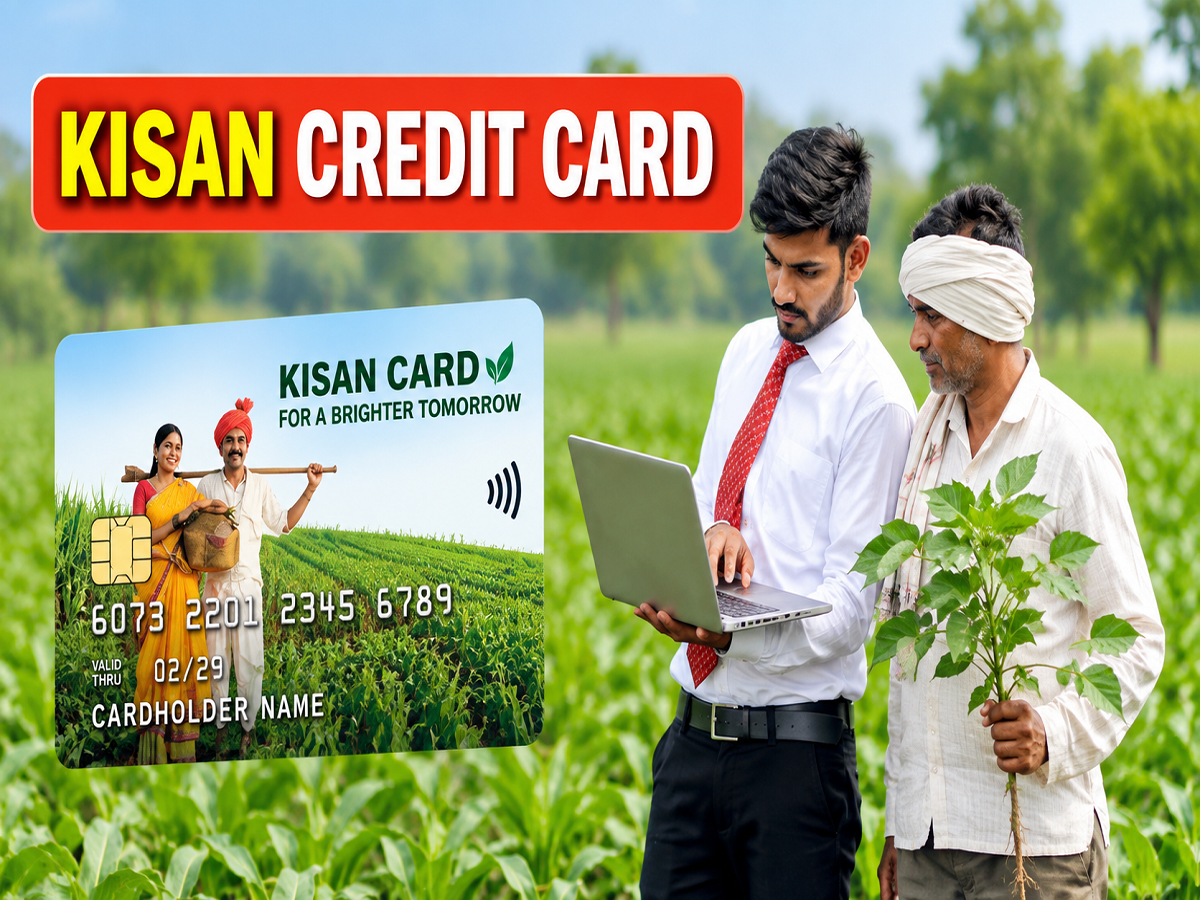
The Kisan Credit Card scheme helps farmers meet expenses related to crops, dairy farming, animal husbandry and fisheries without depending on expensive informal loans. Eligible applicants can obtain short-term credit from participating banks and use the sanctioned amount according to their approved agricultural requirements.
Under the applicable lending framework, eligible agricultural loans of up to ₹2 lakh may be sanctioned without collateral. The standard interest rate on qualifying short-term KCC loans is generally 7% per year. Farmers who repay the amount within the prescribed period may receive an additional 3% prompt-repayment benefit, effectively reducing the interest burden to 4% per year.
However, the sanctioned amount, collateral requirement and interest benefit depend on the borrower’s eligibility, purpose of the loan, repayment record and the bank’s assessment. Applicants should confirm the latest rules with their bank before applying.
How the KCC Interest Benefit Works
The concessional interest structure for eligible Kisan Credit Card loans can be understood in three stages:
- The initial interest rate on a qualifying short-term agricultural loan is generally 7% annually.
- An eligible farmer who repays the loan on time may receive a 3% prompt-repayment incentive.
- After this benefit, the effective interest rate can come down to 4% per year.
The reduced rate is not automatically available in every case. The borrower must meet the conditions prescribed for timely repayment and other applicable requirements. Delayed repayment could result in the loss of the concession, and the bank may charge interest according to its prevailing rules.
Major Benefits of the Kisan Credit Card
One of the scheme’s most important features is access to formal credit at a comparatively affordable rate. The KCC facility can help farmers manage recurring expenses such as seeds, fertilisers, pesticides, animal feed, equipment repairs and other operational needs.
Eligible borrowers may receive the following benefits:
- Collateral-free agricultural credit of up to ₹2 lakh, subject to banking rules and approval
- A possible effective annual interest rate of 4% on qualifying loans repaid within the specified period
- Repayment schedules aligned, where applicable, with the crop and harvesting cycle
- Credit support for farming, dairy, poultry, fisheries and animal husbandry
- Access to eligible insurance coverage under applicable schemes and conditions
- A reusable credit facility within the sanctioned limit, subject to the bank’s terms
Reports sometimes mention higher loan limits in specific categories or under revised policies. However, a higher KCC limit should not be interpreted as automatically collateral-free. Security requirements may vary according to the amount, activity, borrower profile and lender’s guidelines.
Who Can Apply for a Kisan Credit Card?
The KCC scheme is not limited to farmers who own agricultural land. Different categories of people involved in agriculture and allied activities may apply, provided they satisfy the bank’s eligibility criteria.
Potential applicants include:
- Farmers who own cultivable agricultural land
- Tenant farmers cultivating land owned by another person
- Sharecroppers and oral lessees, subject to acceptable documentation
- Members of eligible joint liability or self-help groups
- Dairy farmers and livestock rearers
- People engaged in poultry farming
- Fishers and individuals involved in fisheries-related activities
The applicant is generally expected to be between 18 and 75 years of age. According to the supplied scheme information, borrowers above 60 may need to include an eligible co-applicant. Since individual banks may apply additional conditions, applicants should verify the age and co-borrower requirements with the selected lender.
Documents Required for a KCC Application
The exact document list can vary depending on the applicant’s category, activity and bank. A borrower may generally be asked to provide:
- Aadhaar card, PAN card, voter ID or driving licence as identity proof
- Aadhaar, ration card, electricity bill or another accepted residence document
- Land records such as Khasra, Khatauni or Jamabandi, wherever applicable
- Recent passport-size photographs
- Bank account details
- Information about the crop or agricultural activity
- Documents supporting tenancy, fisheries, dairy or animal-husbandry activities, if relevant
- A declaration regarding existing agricultural loans or outstanding KCC dues
Tenant farmers and sharecroppers may not possess land documents in their own names. Such applicants should ask the bank which alternative records or group-based arrangements it accepts.
How to Apply for a KCC Online
Several banks provide an online or partially digital KCC application facility. The availability and process differ from one lender to another.
Applicants can generally follow these steps:
- Open the official website of the bank where they maintain an account or wish to apply.
- Find the agriculture loans, Kisan Credit Card or KCC application section.
- Enter personal, banking and agricultural activity details.
- Upload the documents requested by the bank.
- Review the information carefully and submit the application.
- Save the application or reference number for future tracking.
After submission, the bank may contact the applicant for document verification, land or activity assessment and additional information. A card or credit facility is issued only after the application is approved.
Eligible PM-Kisan beneficiaries may also obtain the prescribed simplified KCC form through an authorised portal or participating bank. They should confirm the current process through official sources.
How to Submit an Offline Application
Farmers who are not comfortable applying digitally can visit a nearby public-sector, private, regional rural or eligible cooperative bank.
They can request the Kisan Credit Card form, fill in the required information and attach copies of the supporting documents. The completed form should then be submitted to the designated bank official.
The bank will examine the application and may conduct verification before deciding the eligible credit limit. While applications are expected to be processed within the applicable service timeline, approval within 14 days should not be treated as guaranteed. Delays can occur if documents are incomplete or additional verification is needed.
Important Points Before Taking a KCC Loan
A Kisan Credit Card is a borrowing facility, not a government grant. The amount must be repaid according to the lender’s schedule. Farmers should understand the approved limit, interest conditions, repayment deadline, penal charges and insurance deductions before using the credit.
Applicants should use only official bank websites or recognised branches and must never share an OTP, PIN or banking password with an agent. Reading the sanction letter carefully can help borrowers avoid confusion and retain eligible interest benefits through timely repayment.
Disclaimer: This article is for general information only. Loan approval, credit limits, collateral requirements and interest concessions are subject to government rules and the lending bank’s assessment. Applicants should confirm current terms directly with an authorised bank.