
Business
Is ₹1 Crore Enough for Retirement? See How Long Your Corpus Could Last at Different Monthly Expenses
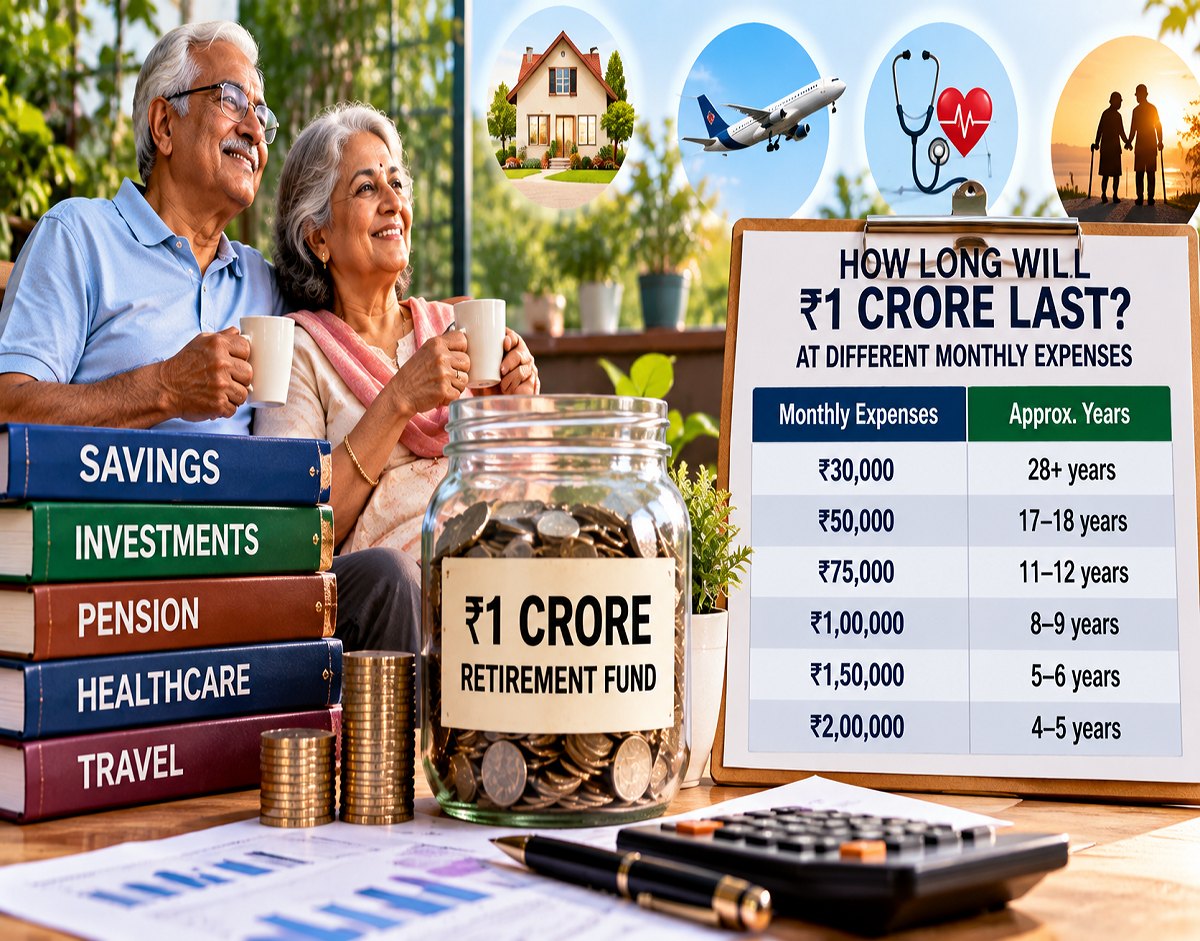
Building a retirement corpus of ₹1 crore may sound like a major financial milestone, but the bigger question begins after retirement: how long will that money actually last?
There is no single answer. The lifespan of a retirement corpus depends on how much you withdraw, how quickly your expenses rise due to inflation and what returns the remaining money generates after retirement.
For example, a retiree spending ₹30,000 per month will place far less pressure on a ₹1 crore corpus than someone who needs ₹60,000 every month. Over a retirement lasting 20, 30 or even 40 years, inflation can make this difference considerably larger.
This is why retirement planning should focus not only on building a large corpus but also on creating a sustainable withdrawal strategy.
How Long Could a ₹1 Crore Retirement Corpus Last?
Consider an illustrative scenario in which a person retires with ₹1 crore.
If the invested corpus generates an average annual return of 8%, while living expenses rise by 6% annually due to inflation, the source provides the following estimates:
| Starting Monthly Expense | Estimated Period ₹1 Crore May Last |
|---|---|
| ₹30,000 | Around 40 years |
| ₹40,000 | Around 27 years |
| ₹50,000 | Around 20 years |
| ₹60,000 | Around 16 years |
These are illustrative estimates rather than guaranteed outcomes. Actual investment returns are unlikely to remain exactly 8% every year, while inflation and household expenses can also fluctuate.
Taxes, medical expenses, investment fees and unexpected withdrawals can further affect how long the corpus survives.
Why Inflation Is a Major Retirement Risk
One of the biggest mistakes in retirement planning is calculating future requirements using only today's expenses.
Suppose a household currently requires ₹40,000 per month to maintain its lifestyle.
If inflation averages 6% annually, maintaining approximately the same purchasing power 10 years later could require roughly ₹71,600 per month.
In other words, an expense that looks manageable at the beginning of retirement can become significantly larger over time.
This effect becomes even more important for people retiring relatively early because their savings may need to support them for several decades.
₹40,000 Today Could Become ₹71,600 in 10 Years
The impact of inflation can be understood through a simple example.
At 6% annual inflation, ₹40,000 of monthly expenditure would rise approximately as follows:
Current monthly expense: ₹40,000
Assumed inflation: 6% annually
Estimated monthly requirement after 10 years: About ₹71,600
The calculation illustrates why simply dividing ₹1 crore by today's annual expenditure does not provide a realistic estimate of how long retirement savings might last.
Expenses themselves are likely to rise.
Healthcare can be especially important because medical costs may become a larger part of household expenditure as retirees grow older.
Should You Keep the Entire ₹1 Crore in Fixed Deposits?
Keeping a retirement corpus entirely in fixed deposits may provide stability and predictable interest income, but it also creates another consideration: inflation.
If the post-tax return from an investment consistently fails to keep pace with inflation, the purchasing power of the retirement corpus can gradually decline.
For example, receiving the same amount of interest every year does not mean that the money will continue to purchase the same quantity of goods and services.
This is why some retirement strategies spread money across different asset classes rather than depending entirely on a single investment.
The appropriate mix, however, depends on factors such as age, risk tolerance, income requirements, taxes and other financial resources.
Putting Everything in Equities Has Risks Too
Moving to the opposite extreme can also create problems.
Keeping an entire retirement corpus in equities can expose a retiree to substantial market volatility. This becomes particularly important when money has to be withdrawn during a major market correction.
If investments fall sharply and the retiree still needs to withdraw money for regular expenses, assets may have to be sold at depressed prices.
Repeated withdrawals during a prolonged downturn can reduce the amount available to participate in a subsequent market recovery.
Retirement planning therefore involves balancing the need for capital protection, liquidity, income and long-term growth.
How Does the 4% Withdrawal Rule Work?
A widely discussed retirement-planning guideline is the 4% withdrawal rule.
Under this approach, a retiree withdraws approximately 4% of the retirement portfolio during the first year. The withdrawal amount is then adjusted in subsequent years to account for inflation.
For a ₹1 crore corpus:
₹1 crore × 4% = ₹4 lakh per year
That works out to approximately:
₹4,00,000 ÷ 12 = ₹33,333 per month
So, under this simplified framework, a person retiring with ₹1 crore could begin by withdrawing around ₹33,300 per month in the first year.
If inflation is assumed at 6%, the withdrawal amount could be increased accordingly in the following year.
Does the 4% Rule Guarantee Your Money Won't Run Out?
No.
The 4% rule should be treated as a retirement-planning guideline rather than a guarantee.
Its sustainability can depend heavily on investment returns, inflation, portfolio allocation and the order in which good and bad market years occur.
For example, experiencing a severe market decline during the first few years of retirement while simultaneously making withdrawals can put greater pressure on a portfolio than experiencing the same decline much later.
Taxes, investment expenses and large unplanned withdrawals can also change the outcome.
This means retirees should periodically review their withdrawal rate instead of assuming one formula will remain appropriate throughout retirement.
Emergency and Healthcare Costs Can Change the Calculation
Regular household expenses are only one part of retirement planning.
A major medical bill, home renovation, financial support for family members or another unexpected expense could require a substantial one-time withdrawal from the corpus.
For example, withdrawing ₹10 lakh unexpectedly does more than reduce the portfolio by ₹10 lakh. It also removes the future investment returns that amount might otherwise have generated.
Maintaining adequate health insurance and a separate emergency reserve can therefore help protect the long-term retirement portfolio from some unexpected expenses.
Can ₹1 Crore Last for the Rest of Your Life?
Possibly—but not in every situation.
Under the assumptions provided in the example, ₹1 crore could potentially last around 40 years when starting expenditure is ₹30,000 per month. At ₹50,000 per month, the illustrative period falls to roughly 20 years, while ₹60,000 per month could reduce it to around 16 years.
The difference demonstrates how strongly spending affects retirement sustainability.
A person with other sources of income—such as a pension, rental income or another reliable cash flow—may need to withdraw less from the corpus. Someone who depends entirely on the ₹1 crore portfolio may need to manage withdrawals more carefully.
Ultimately, the important retirement number is not simply the size of the corpus. It is the relationship between your savings, annual expenses, inflation, investment returns and expected retirement duration.
A ₹1 crore retirement fund can provide substantial financial support, but whether it lasts 15 years, 25 years or several decades will depend largely on how it is invested and how quickly money is withdrawn.
Disclaimer: The calculations above are illustrative and based on assumed rates of return and inflation. Investment returns are not guaranteed, and actual inflation, taxes, expenses and market performance may differ significantly. This article is for general informational purposes and should not be considered investment advice. Consider consulting a qualified financial adviser before making retirement or investment decisions.



