
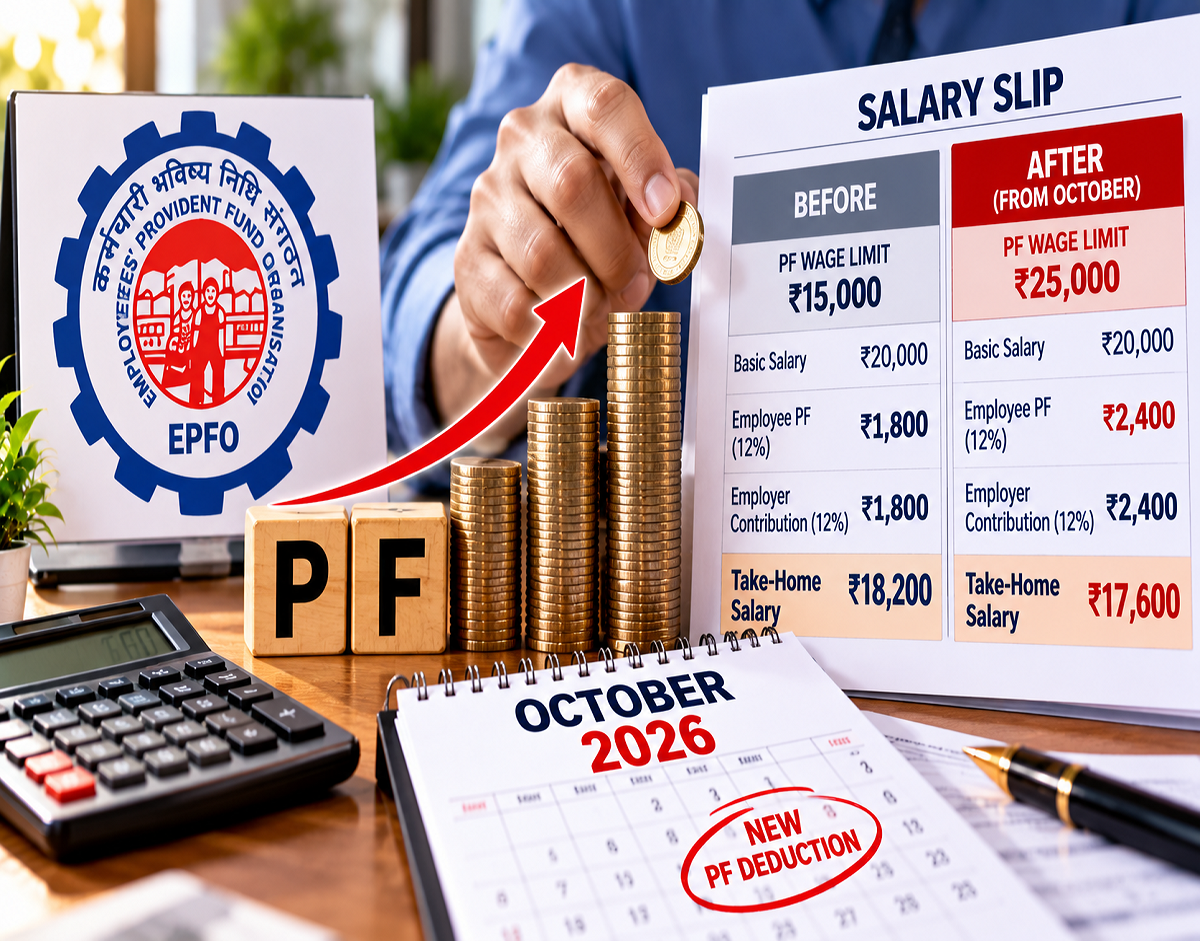
Employees whose PF wages fall between ₹15,000 and ₹25,000 could see a change in their monthly provident fund contribution from October 2026 following the increase in the wage ceiling cited in the source.
According to the report, the EPFO wage ceiling has been increased from ₹15,000 to ₹25,000, with the revised framework taking effect from September 17, 2026. Since the change came into force during September, that month's calculation may involve the old and revised rules for the respective periods. The full monthly impact would therefore become clearer from October.
For an employee with PF wages of ₹20,000, the employee-side contribution in the example rises from ₹1,800 to ₹2,400 per month.
That means an additional ₹600 per month could move from salary into the employee's provident fund contribution, subject to the employee's applicable PF arrangement and salary structure.
Here's the calculation.
₹20,000 PF Wage: How Much Could Be Deducted?
EPF contributions are generally calculated at 12% of applicable PF wages under the standard contribution structure.
Consider an employee whose PF wage is ₹20,000.
At 12%, the employee contribution works out to:
₹20,000 × 12% = ₹2,400 per month
Under the earlier ₹15,000 ceiling used in the example, the contribution was:
₹15,000 × 12% = ₹1,800 per month
The difference is therefore:
₹2,400 − ₹1,800 = ₹600
So, in this illustration, ₹600 more would go toward the employee's PF contribution every month.
Old vs New PF Contribution on ₹20,000 PF Wages
The source provides the following comparison:
| Contribution | Earlier Structure | From October 2026 Example |
|---|---|---|
| Employee EPF contribution | ₹1,800 | ₹2,400 |
| Employer EPS contribution | ₹1,250 | ₹1,666 |
| Employer EPF contribution | ₹550 | ₹734 |
| Total employer contribution | ₹1,800 | ₹2,400 |
| Employee + employer contribution | ₹3,600 | ₹4,800 |
Under this example, the combined monthly contribution from the employee and employer increases from ₹3,600 to ₹4,800.
However, the employer's contribution is divided between EPF and the Employees' Pension Scheme (EPS), subject to the applicable rules.
How Is the Employer's ₹2,400 Contribution Divided?
For the ₹20,000 PF-wage example, the employer also contributes ₹2,400.
The entire employer contribution does not necessarily go into the employee's EPF balance.
According to the calculation provided in the source:
Employer's total contribution: ₹2,400
Amount allocated to EPS: approximately ₹1,666
Amount allocated to EPF: approximately ₹734
Together:
₹1,666 + ₹734 = ₹2,400
The employee's own ₹2,400 contribution goes toward EPF under the example, while the employer contribution is divided between the provident fund and pension components according to the applicable framework.
Does This Mean ₹4,800 Will Be Deducted From Salary?
No.
This is an important distinction.
The combined ₹4,800 represents the employee and employer contributions together in the ₹20,000 example. It does not mean ₹4,800 will be deducted from the employee's salary.
The employee-side contribution in this example is ₹2,400.
The employer separately contributes another ₹2,400.
The source also states that the employer's statutory contribution cannot simply be deducted from the employee's salary as though it were the employee's PF contribution.
However, the way employer contributions interact with an employee's overall cost-to-company structure can vary, so the effect on compensation should be checked against the employment contract and salary structure.
Will Everyone's PF Be Calculated on ₹25,000?
No.
₹25,000 is the revised wage ceiling cited in the source; it does not mean every employee automatically contributes PF based on ₹25,000.
If the applicable PF wage is lower, the contribution would be calculated using that lower amount.
For example, the source provides these employee-contribution illustrations:
| PF Wage | Employee Contribution at 12% |
|---|---|
| ₹10,000 | ₹1,200 |
| ₹20,000 | ₹2,400 |
| ₹25,000 | ₹3,000 |
So an employee with PF wages of ₹10,000 would contribute ₹1,200 under a 12% calculation, not ₹3,000.
Similarly, someone with ₹20,000 in applicable PF wages would contribute ₹2,400.
PF Wage and Gross Salary Are Not Necessarily the Same
Employees should also avoid confusing PF wages with their total monthly salary.
An employee may have basic pay, dearness allowance and several other salary components. The amount considered for provident fund purposes depends on the applicable EPF rules and the employee's salary structure.
Therefore, someone earning a gross monthly salary above ₹25,000 should not automatically conclude that ₹3,000 will be deducted as PF.
The relevant PF wage needs to be identified first.
Could Existing EPF Members Also Be Affected?
According to the source, the revised ceiling may also affect some existing EPF members.
This could be particularly relevant for employees who were already covered by EPF but whose position under EPS was affected by the previous ₹15,000 wage ceiling.
The report states that, under the revised framework, an employee with PF wages of ₹20,000 in the relevant category may become an EPS member. In such a situation, the employer contribution can be divided between EPF and EPS according to the applicable rules.
The precise treatment can depend on an employee's existing membership status and other regulatory conditions.
How Much Could Take-Home Salary Fall?
Consider again the ₹20,000 PF-wage example.
Earlier employee contribution: ₹1,800
Revised employee contribution: ₹2,400
Additional monthly contribution: ₹600
If all other salary components remain unchanged and the higher contribution applies directly, the employee's immediate take-home amount could be lower by around ₹600 per month.
On an annualised basis:
₹600 × 12 = ₹7,200
That represents additional employee contributions of approximately ₹7,200 over a full 12-month period.
The actual change in take-home pay can differ depending on the salary structure, existing PF contribution method and payroll treatment.
Higher Deduction Also Means More Retirement Savings
A larger PF deduction can reduce the amount available as monthly take-home salary, but the money is not simply an expense.
The employee's contribution is being directed toward retirement savings.
For someone whose monthly employee contribution increases from ₹1,800 to ₹2,400, an additional ₹600 is being added to provident fund savings each month.
Over several years, the combination of higher contributions and applicable EPF interest can potentially result in a larger retirement corpus.
The employer's contribution can also add to the employee's provident fund and pension benefits according to the EPF/EPS allocation rules.
Why September and October Calculations Could Look Different
The source states that the revised wage ceiling became effective on September 17, 2026.
Because the change took effect in the middle of September, that month's payroll and PF calculation may not necessarily look the same as a complete month under the revised framework.
October would be the first full month in which the revised arrangement could show its complete impact, according to the report.
Employees affected by the change should therefore review their September and October payslips carefully.
Check Your October Salary Slip
Once the revised contribution appears in payroll, employees should look at their October salary slips and PF records to understand the actual impact.
Check the PF wage used for the calculation, employee contribution, employer contribution and EPS allocation.
For a ₹20,000 PF wage, the illustration provided in the source results in an employee contribution of ₹2,400 and an employer contribution of ₹2,400, taking the combined contribution to ₹4,800 per month.
Compared with the earlier ₹3,600 combined amount in the example, that represents an increase of ₹1,200 per month across the employee and employer contributions.
For the employee personally, the key figure is the ₹600 increase in the employee-side monthly contribution, subject to the revised rules applying to that employee.
Disclaimer: This article is for general informational purposes. EPF and EPS contributions can depend on membership status, applicable wage definitions, salary structure and prevailing EPFO rules. Employees should verify the contribution shown in their payroll and EPFO records or consult their employer/EPFO for clarification before making financial decisions.



