
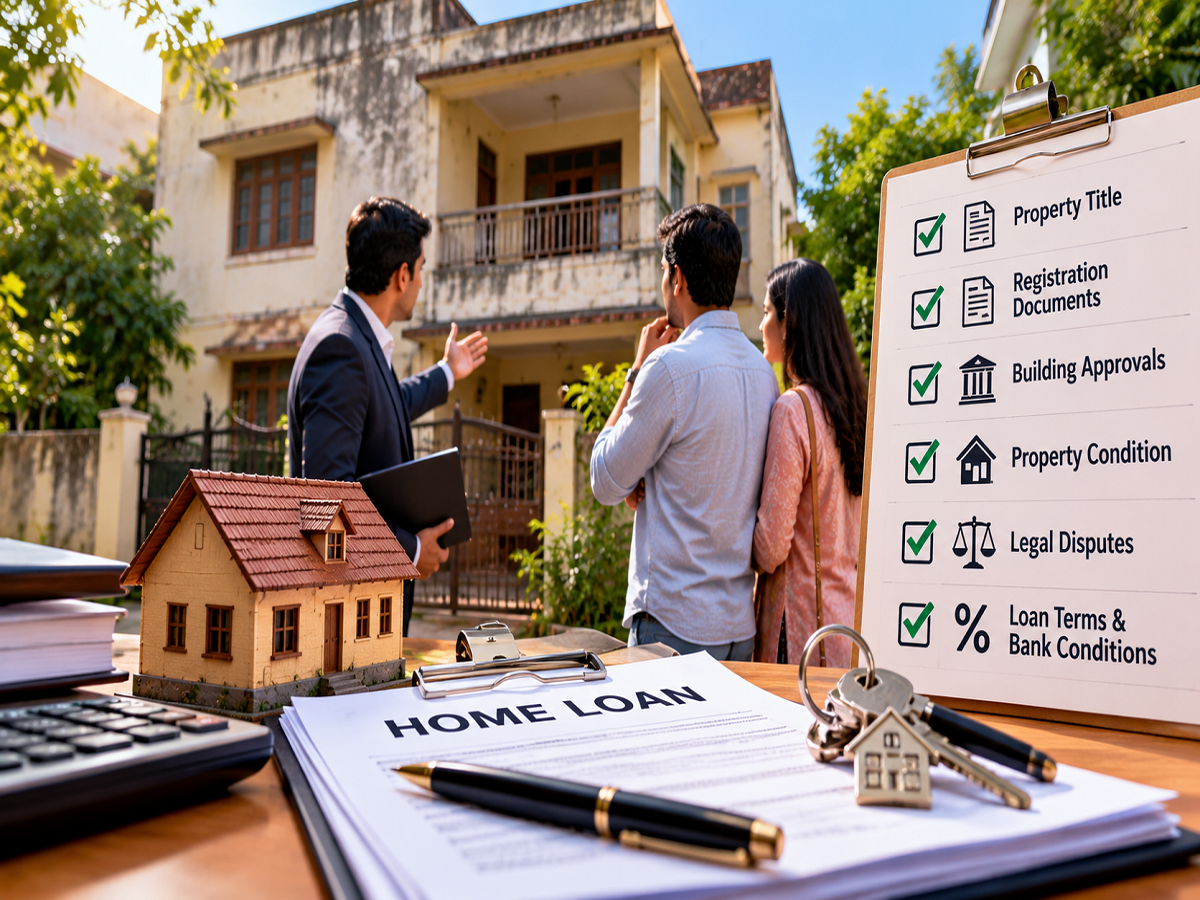
Buying a resale or older property can sometimes offer advantages over purchasing a newly built home. Established neighbourhoods often have better access to roads, markets, schools and other essential facilities. In some locations, an older house may also be available at a lower price than a new property in the same area.
However, a lower purchase price alone does not necessarily make an old house a better deal. Buyers planning to finance a resale property through a home loan need to examine its physical condition, ownership history, legal documents, construction approvals and likely repair expenses.
Banks also carry out their own checks before approving a home loan because the property usually serves as security for the loan.
According to Atul Monga, Co-founder and CEO of BASIC Home Loan, buyers should carefully evaluate the property's title, registration, approvals and structural condition before proceeding.
A Colliers Homebuying Sentiment Survey 2026 cited in the source found that 50% of prospective buyers intended to purchase a home within the next two years. The survey covered around 1,800 respondents across more than 30 residential markets.
If you are considering an older home, here are six important areas to examine.
1. Look Beyond the Property's Age
A 15-year-old house and a 40-year-old property cannot automatically be evaluated in the same way. At the same time, age by itself does not reveal whether a property is in good or bad condition.
Buyers should examine structural condition, maintenance history and any modifications carried out over the years.
For a significantly older building, getting its structural stability assessed may also be useful before committing a large amount of money.
Repair expenses should be included while calculating the property's actual acquisition cost.
For example, suppose an older house is available for ₹70 lakh but immediately requires ₹8 lakh of renovation and repair work. The effective cost becomes approximately ₹78 lakh even before considering other purchase-related expenses.
A seemingly cheaper property may therefore become considerably more expensive once essential repairs are included.
2. Check How Property Age Could Affect Loan Tenure
Buyers should not assume that a bank will offer the same home-loan tenure for every property.
The age and remaining useful life of an older house can influence a lender's assessment. Its condition, documentation and value as security may also be considered when determining loan terms.
This means comparing two properties purely on their selling prices can be misleading.
A buyer should also consider how much the lender is willing to finance, the available repayment period and the resulting EMI burden.
A shorter tenure can lead to higher monthly repayments even if the property's purchase price appears attractive.
3. Registration Alone Does Not Guarantee a Clear Property
One common mistake is assuming that a registered property automatically has a completely clean legal history.
Registration is important, but it is only one part of property due diligence.
The ownership title should be examined carefully, including the chain of previous ownership where relevant. Buyers should also check whether there are outstanding loans, legal disputes, encumbrances or unpaid property taxes connected with the property.
The physical construction should also correspond with the sanctioned building plan and applicable regulations.
The source article, referring to the RBI's housing finance framework, notes requirements concerning compliance with sanctioned plans and applicable building rules for constructed properties. Completion-related documentation may also be relevant where applicable.
A lender's legal and technical checks are valuable, but buyers should not treat them as a complete substitute for their own due diligence.
4. Check Whether Later Construction Changes Were Approved
Older houses often undergo modifications over time.
An owner may have added another floor, enclosed a balcony, extended a room or altered another part of the original structure.
Such changes can create problems if the physical property no longer matches its sanctioned plans or official documentation.
An undocumented or unauthorised extension could complicate a home-loan application and potentially create legal or regulatory issues for the new owner.
Before finalising the purchase, buyers should therefore compare the property's current physical layout with the approved building plan and other relevant records.
If substantial modifications have been made, check whether the required approvals were obtained.
5. Understand the Property's Legal Classification
Some older properties can have more complicated ownership and land records than standard residential properties.
The source article highlights Lal Dora properties as one example where buyers may need to investigate the nature of the land and ownership documentation carefully.
According to information attributed in the source to Delhi's Revenue Department, a Lal Dora Certificate relates to land or property ownership in a village's inhabited area. However, buyers should still examine the complete title chain and other applicable documents instead of relying on a single certificate.
Extra caution may also be necessary when considering a property in an unauthorised colony.
The source, referring to the RBI's housing finance framework, states that lending restrictions can apply to properties in unauthorised colonies unless the required regularisation and related conditions have been fulfilled.
The exact legal position can depend on the location and property, so professional legal verification can be particularly valuable in such cases.
6. Evaluate the House and Home Loan Together
The property and its financing should not be treated as two completely separate decisions.
The condition and documentation of a house can influence whether a lender is willing to finance it and how much funding may be available.
At the same time, the buyer's financial burden does not end with the EMI.
An older property may involve immediate renovation, structural repairs and ongoing maintenance expenses. Registration-related costs, taxes and other transaction expenses may further increase the total amount required.
Before deciding how much to borrow, calculate the complete cost of acquiring and making the property usable.
A Cheaper Old House Isn't Always the Cheaper Option
An older home can still be a worthwhile purchase. Established locations, existing infrastructure and comparatively attractive prices can make resale properties appealing to many buyers.
The key is to evaluate the entire transaction rather than focusing only on the advertised price.
Start by verifying ownership and the title chain. Check registration records and look for outstanding loans, encumbrances or disputes. Compare the existing construction with sanctioned plans and investigate any later modifications. Assess the physical condition of the building and estimate renovation expenses before approaching the financing decision.
Finally, understand how the property's age and condition could affect loan eligibility, tenure and the amount a lender is prepared to finance.
A well-maintained older house with clear documentation may be easier to finance than a cheaper property with structural problems or complicated legal records. For buyers, the real question is therefore not simply how old or inexpensive a property is, but whether its documents, construction, condition and financing make the overall purchase financially sensible.
Disclaimer: This article is intended for general informational purposes only. Property laws, lending requirements and documentation can vary according to location and individual circumstances. Buyers should consider obtaining independent legal, structural and financial advice before purchasing a property or taking a home loan.



