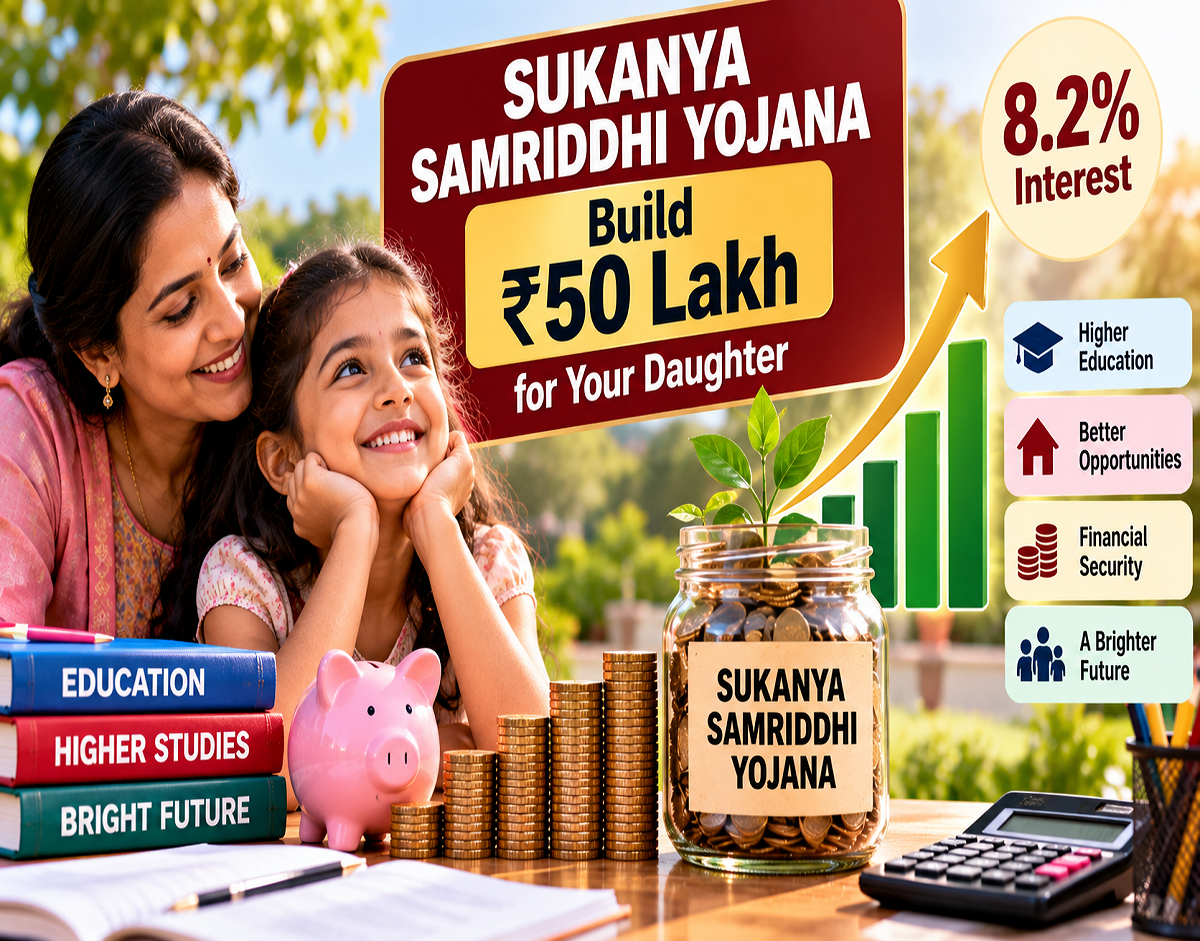
Sukanya Samriddhi Yojana Interest Rate: Parents investing for their daughter's long-term financial needs may soon get clarity on whether the Sukanya Samriddhi Yojana (SSY) interest rate will change for the October-December 2026 quarter.
The central government is expected to announce interest rates applicable to small savings schemes for the third quarter of FY 2026-27. At present, Sukanya Samriddhi Yojana offers an annual interest rate of 8.2%.
The rate was increased from 8% to 8.2% for the January-March 2024 quarter and, according to the supplied information, has remained unchanged through the subsequent reviews. If the government keeps the rate unchanged for October-December 2026 as well, SSY investors will continue earning 8.2% during the new quarter.
However, until the government announces the applicable rates, any expectation of a hike, cut or unchanged rate should be treated as an estimate rather than a confirmed decision.
Will Sukanya Samriddhi Interest Rate Increase?
The source suggests that a major increase in the SSY interest rate may not be necessary under the existing rate-setting framework.
It cites long-term government security yields of approximately 7.2% to 7.55% and argues that the current 8.2% SSY rate remains broadly consistent with the formula-based range discussed for the scheme.
According to the source, the Shyamala Gopinath Committee framework links small-savings rates with yields on government securities, with a spread applicable to individual schemes.
For SSY, the article cites a spread of 75 basis points, or 0.75 percentage point, over the relevant government bond yield.
On that basis, it estimates a range of roughly 8% to 8.3%, putting the existing 8.2% rate within that band.
This does not guarantee that the government will retain 8.2%. The final rate for the quarter depends on the government's official notification.
5 Important Sukanya Samriddhi Rules to Understand
Sukanya Samriddhi Yojana is designed specifically for the long-term financial needs of a girl child.
According to the information provided in the source, an SSY account can be opened for an eligible girl below the prescribed age limit of 10 years.
The minimum annual contribution is ₹250, while a maximum of ₹1.5 lakh can be deposited in a financial year.
The scheme also offers tax benefits subject to the applicable provisions and conditions.
Another important point is that SSY does not operate like a bank fixed deposit where the interest rate at the time of opening is necessarily locked for the entire tenure.
The government reviews small-savings interest rates quarterly, and the rate announced for SSY applies according to the scheme's applicable rules.
SSY Currently Pays More Than PPF
The source compares the current SSY interest rate with the Public Provident Fund.
At present, the rates cited are:
| Scheme | Current Annual Interest Rate |
|---|---|
| Sukanya Samriddhi Yojana | 8.2% |
| Public Provident Fund | 7.1% |
| Difference | 1.1 percentage points |
This means SSY currently offers an interest rate 1.1 percentage points higher than PPF.
However, the two schemes should not be viewed as interchangeable merely because of the interest-rate difference.
SSY is specifically designed for eligible girl children, whereas PPF has a much broader eligibility framework.
Can SSY Build a ₹50 Lakh Corpus?
Now consider the long-term calculation highlighted in the source.
Under Sukanya Samriddhi Yojana, deposits are made for the prescribed contribution period, while the account has a longer maturity period.
The source calculates how much a parent would need to invest to accumulate approximately ₹50 lakh, assuming the current 8.2% annual interest rate remains applicable throughout the illustration.
According to that calculation:
| Particular | Amount/Period |
|---|---|
| Annual investment | ₹1,04,500 |
| Approximate monthly equivalent | ₹8,708 |
| Contribution period | 15 years |
| Account tenure used | 21 years |
| Total amount deposited | ₹15,67,500 |
| Estimated interest earned | ₹34,33,371 |
| Estimated maturity amount | ₹50,00,871 |
Under these assumptions, total contributions of around ₹15.68 lakh could potentially grow to slightly more than ₹50 lakh over the full period.
The estimated interest component alone comes to approximately ₹34.33 lakh.
How Does ₹8,708 Per Month Become ₹50 Lakh?
The monthly figure can be slightly misleading because SSY contributions do not necessarily have to be made as an identical monthly SIP.
The source converts the annual investment requirement of ₹1,04,500 into a monthly equivalent:
₹1,04,500 ÷ 12 = approximately ₹8,708 per month
Over 15 years, the total contribution becomes:
₹1,04,500 × 15 = ₹15,67,500
After the contribution period ends, the money already accumulated in the account continues according to the scheme's interest and maturity rules.
Based on a constant 8.2% interest-rate assumption used in the source calculation, the estimated maturity value reaches approximately ₹50,00,871.
Therefore, the majority of the projected ₹50 lakh corpus comes from long-term compounding rather than contributions alone.
Why Starting Early Matters
SSY is designed as a long-term savings product, so compounding plays an important role.
The earlier an eligible account is opened, the more effectively the family can plan contributions around the child's future requirements.
For example, money may eventually be needed for higher education or other major financial goals.
Instead of trying to arrange a large amount shortly before the expense arises, regular contributions spread the financial burden across several years.
The ₹50 lakh example also demonstrates the difference between the amount invested and the potential maturity value.
Total deposits in the illustration are only ₹15.67 lakh, while the estimated maturity corpus is approximately ₹50 lakh.
That difference is driven by the assumed interest and long investment horizon.
But Will You Definitely Receive ₹50 Lakh?
No. The ₹50 lakh figure should be understood as an illustrative projection, not a guaranteed maturity amount based on today's rate.
The calculation assumes an 8.2% annual interest rate throughout the illustration.
SSY is subject to interest rates notified by the government from time to time. If rates change during the 21-year period, the eventual maturity amount can also change.
For example, if future rates are lower than 8.2%, the final corpus could be lower than the illustration. If rates rise, the outcome could be higher, depending on the applicable rules and duration of those rates.
This distinction is particularly important when planning for a financial goal that may be more than a decade away.
What Happens if the Government Changes the Rate?
SSY interest rates are reviewed periodically rather than being permanently fixed when an account is opened.
Therefore, someone opening an account while the rate is 8.2% should not assume that the same rate will necessarily continue for the entire tenure.
The source describes SSY as having a floating-rate structure, meaning newly notified rates affect the account in accordance with the scheme's rules.
For this reason, long-term financial planning should include some flexibility rather than relying on a single interest rate for 21 years.
Is an Interest-Rate Cut Expected This Quarter?
The source argues that recent strength in longer-term government bond yields provides support for keeping the SSY rate at 8.2%.
However, that is an assessment based on the rate-setting framework and prevailing yields—not an official confirmation.
The government may keep the rate unchanged, raise it or reduce it when it announces the rates applicable for the October-December 2026 quarter.
Investors should therefore wait for the official small-savings notification before treating any new rate as final.
Key Takeaway for Parents
At the currently cited 8.2% annual interest rate, Sukanya Samriddhi Yojana remains an important government-backed long-term savings option designed specifically for a girl child.
The supplied calculation suggests that an annual contribution of around ₹1,04,500, equivalent to roughly ₹8,708 per month, could potentially build a corpus of approximately ₹50 lakh over the full period if an 8.2% rate were assumed throughout.
The illustration consists of approximately ₹15.67 lakh in total deposits and ₹34.33 lakh in estimated interest, producing a projected maturity amount of ₹50,00,871.
The actual maturity amount, however, can differ because SSY interest rates are reviewed periodically. Parents planning around a specific target such as ₹50 lakh should revisit their contribution strategy whenever rates change.
Disclaimer: This article is for general informational purposes only. The ₹50 lakh calculation is an illustration based on the assumptions and figures provided in the source, including an 8.2% interest rate. Actual returns can vary if government-notified SSY rates change during the account tenure. Tax treatment and scheme rules are also subject to applicable laws and amendments. Check the latest official rules or consult a qualified financial professional before making financial decisions.