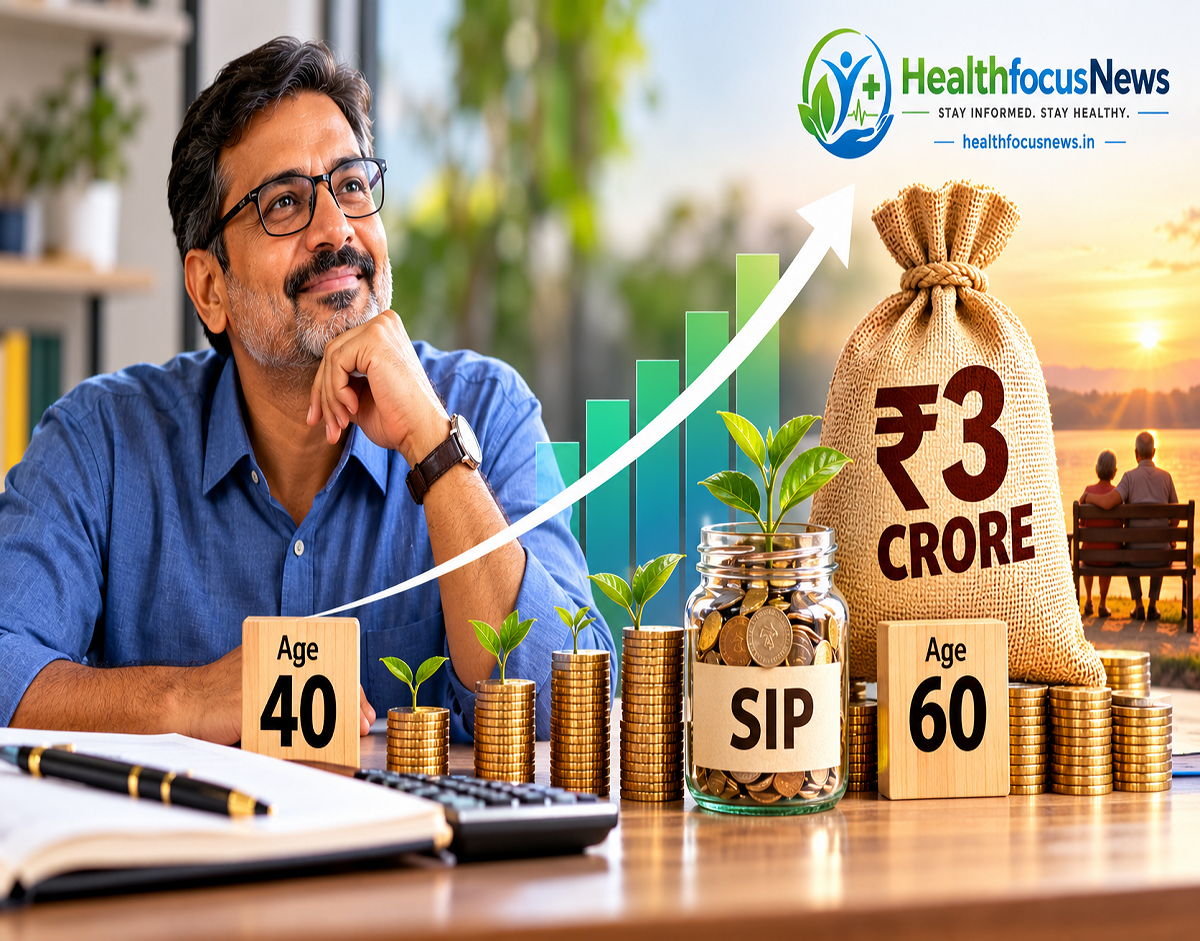
SIP Investment Plan for Retirement: Reaching the age of 40 without significant retirement savings can be concerning, especially when household expenses, children's education and other financial responsibilities are increasing. However, starting late does not necessarily mean that building a substantial retirement fund is impossible.
With disciplined investing, careful financial planning and a suitable Systematic Investment Plan (SIP), a person beginning at 40 can still work towards creating a sizeable retirement corpus by the age of 60.
The biggest challenge is time. Someone starting at 25 has approximately 35 years until retirement at 60, while a 40-year-old has only 20 years. Consequently, investors starting later generally need to contribute more money each month to pursue the same financial target.
For example, a retirement goal of approximately ₹3 crore may be achievable under certain assumed investment returns and contribution levels. However, actual mutual fund returns are market-linked and cannot be guaranteed.
Here is how monthly SIP contributions, annual investment increases and other retirement savings options could help investors plan for the next two decades.
Can You Build a Retirement Fund After Starting at 40?
Many people delay retirement planning because of financial commitments during their younger years.
Home loan repayments, education expenses, family responsibilities and unexpected medical bills can make long-term investing difficult.
By the time they reach their 40s, some individuals realise they have accumulated little money specifically for retirement.
Although beginning early provides a significant advantage through compounding, a 20-year investment period can still offer meaningful opportunities for wealth accumulation.
The key is to create a realistic savings target and invest consistently.
A person who starts at 40 may need to allocate a larger percentage of monthly income towards retirement compared with someone who began investing much earlier.
However, the appropriate amount will depend on income, existing assets, debt obligations and tolerance for investment risk.
How Much Money Will You Need After Retirement?
Before deciding on a monthly SIP amount, it is important to estimate future living expenses.
Inflation gradually reduces the purchasing power of money, meaning the same lifestyle may become considerably more expensive over time.
Suppose a household currently spends ₹30,000 every month.
If annual inflation averages 6%, those monthly expenses could rise to approximately ₹96,000 after 20 years.
This means a family spending ₹30,000 today may need almost ₹1 lakh per month in 2046 to maintain a comparable standard of living.
How Inflation Could Increase Monthly Expenses
| Current Monthly Expenses | Estimated Monthly Expenses After 20 Years at 6% Inflation |
|---|---|
| ₹20,000 | ₹64,143 |
| ₹30,000 | ₹96,214 |
| ₹40,000 | ₹1,28,285 |
| ₹50,000 | ₹1,60,357 |
| ₹60,000 | ₹1,92,428 |
These figures are illustrative and assume a constant annual inflation rate of 6%.
Actual inflation may differ, and healthcare expenses could rise at a different pace.
Why Might You Need Around ₹3 Crore for Retirement?
One commonly used retirement planning guideline is to consider a corpus equivalent to approximately 25 to 30 times annual retirement expenses.
For someone expecting monthly expenses of around ₹96,000 at retirement, the estimated annual requirement would be approximately ₹11.5 lakh.
Multiplying this annual amount by 25 gives a retirement corpus of roughly ₹2.9 crore.
This explains why ₹3 crore can be a useful illustrative target for someone currently spending ₹30,000 per month.
However, the 25-times rule is only a starting point.
The actual retirement requirement depends on life expectancy, inflation, healthcare costs, post-retirement investment returns, taxes and other sources of income.
What Can a ₹15,000 Monthly SIP Generate in 20 Years?
Consider a 40-year-old investor who begins investing ₹15,000 every month through mutual fund SIPs.
Over 20 years, the total contribution would be:
₹15,000 × 12 × 20 = ₹36,00,000
The final investment value would depend on the returns earned over the investment period.
At an assumed annualised return of 10%, the corpus could grow to approximately ₹1.14 crore.
At an assumed annualised return of 12%, the estimated value could reach approximately ₹1.48 crore.
These calculations use an illustrative monthly compounding convention with investments at the end of each month.
SIP Returns: ₹15,000 Monthly Investment for 20 Years
| Assumed Annual Return | Total Investment | Estimated Maturity Value |
|---|---|---|
| 8% | ₹36 lakh | ₹88.4 lakh |
| 10% | ₹36 lakh | ₹1.14 crore |
| 12% | ₹36 lakh | ₹1.48 crore |
The table demonstrates how assumed returns influence long-term investment outcomes.
However, mutual fund returns are not fixed, and the actual corpus could be higher or lower than these estimates.
How Much Monthly SIP Is Needed to Build ₹3 Crore?
If an investor wants to accumulate approximately ₹3 crore over 20 years, the required monthly contribution depends heavily on the assumed rate of return.
Under an illustrative 12% annualised return, a monthly SIP of approximately ₹30,300 would be needed to approach ₹3 crore.
For a slightly lower target of ₹2.9 crore, the monthly contribution would be approximately ₹29,300.
These estimates assume a constant monthly contribution throughout the investment period.
A lower return would require a higher SIP amount, while a higher return could reduce the required monthly contribution.
The difficulty is that actual market returns cannot be predicted reliably over a 20-year period.
Step-Up SIP: Start With ₹15,000 and Increase Your Investment Every Year
For many people in their 40s, immediately investing ₹30,000 or more each month may be difficult.
A step-up SIP provides an alternative approach.
Under this strategy, investors begin with a manageable monthly contribution and increase it periodically as their income grows.
For example, someone could start with a ₹15,000 monthly SIP and increase the contribution by 10% every year.
The investment amount would gradually rise over time.
Example: Annual SIP Increase of 10%
| Investment Year | Monthly SIP |
|---|---|
| Year 1 | ₹15,000 |
| Year 2 | ₹16,500 |
| Year 3 | ₹18,150 |
| Year 4 | ₹19,965 |
| Year 5 | ₹21,962 |
| Year 10 | ₹35,369 |
| Year 15 | ₹56,962 |
| Year 20 | ₹91,739 |
The annual increases require the investor to have sufficient income growth and available savings.
A step-up SIP can potentially help build a larger retirement corpus than a fixed monthly investment, but the final outcome still depends on market performance.
Can a 10% Annual SIP Increase Help You Reach ₹3 Crore?
Under the illustrated step-up strategy, the investor starts with ₹15,000 per month and raises the SIP amount by 10% every year.
Assuming a 12% annualised return, calculated using a 1% monthly rate, the investment could grow to approximately ₹2.95 crore over 20 years.
The total amount invested would be around ₹1.03 crore, while the remaining ₹1.92 crore would represent estimated investment gains.
This shows how increasing contributions over time can significantly influence retirement savings.
However, the strategy requires considerable financial discipline. By the twentieth year, the monthly SIP would exceed ₹91,000.
Investors should therefore assess whether their future income is likely to support such increases.
EPF Can Provide Additional Retirement Savings
Salaried employees covered by the Employees' Provident Fund (EPF) may already be accumulating retirement savings through regular contributions.
Both employee and employer contributions, subject to applicable rules, can help create a long-term retirement fund.
Before setting a new SIP target, employees should review their existing EPF balance and estimate its potential value at retirement.
For example, someone who already has a substantial EPF corpus may not need to accumulate the entire ₹3 crore through mutual funds alone.
The combined value of EPF, mutual funds, other investments and pension savings should be considered when calculating retirement readiness.
PPF: Another Option for Long-Term Retirement Planning
The Public Provident Fund (PPF) is another savings instrument that can form part of a retirement strategy.
PPF has an initial maturity period of 15 years and offers interest at rates notified by the government.
The scheme is generally considered suitable for investors seeking a government-backed savings option with tax benefits under applicable rules.
The supplied report mentions a PPF interest rate of 7.1% for the relevant period. Investors should verify the officially notified rate before investing, as small-savings interest rates are reviewed periodically.
PPF also has annual deposit limits and withdrawal restrictions.
Therefore, it may be used as one component of retirement savings rather than as a complete substitute for other investments.
NPS: Consider Pension Planning Alongside SIPs
The National Pension System (NPS) is another option for individuals building a retirement corpus.
It allows subscribers to invest in a combination of market-linked assets according to the applicable investment choices and regulatory framework.
NPS may provide opportunities for long-term wealth accumulation and retirement income planning.
However, withdrawal and annuity requirements depend on the subscriber category, accumulated corpus and rules applicable at the time of exit.
The supplied article refers to changes allowing certain subscribers to withdraw a larger proportion of their NPS corpus. Such provisions should be checked against the latest official PFRDA regulations before making retirement decisions.
Investors should also consider taxation, liquidity restrictions and annuity arrangements.
Should You Invest Everything in Equity Mutual Funds?
Equity mutual funds can provide long-term growth opportunities, but they also involve significant market risk.
A person beginning retirement investments at 40 may consider diversified equity funds, such as broad-market index funds or suitable flexi-cap funds, depending on their financial circumstances.
However, allocating most retirement savings to equity is not appropriate for everyone.
Investors with unstable income, substantial debt or limited emergency savings may need a more conservative approach.
As retirement approaches, gradually shifting a portion of investments towards suitable lower-volatility assets may help reduce the impact of a major market decline shortly before withdrawals begin.
This process is often called de-risking or adjusting asset allocation.
Five Important Steps for Investors Starting at 40
Starting retirement planning later requires a practical and consistent strategy.
- Estimate retirement expenses: Calculate how much your household may need after accounting for inflation.
- Review existing savings: Include EPF, PPF, NPS, bank deposits and other investments when estimating your retirement corpus.
- Choose an affordable SIP: Begin with an amount that does not compromise essential household expenses.
- Increase contributions when possible: Use salary increments or additional income to gradually raise retirement savings.
- Review investments regularly: Reassess your portfolio, risk exposure and retirement target at least once a year.
Investors should also maintain emergency savings and adequate health insurance to avoid withdrawing long-term investments during unexpected financial difficulties.
Final Thoughts: Starting at 40 Is Still an Opportunity
Building a substantial retirement corpus after turning 40 may require higher monthly contributions, but disciplined investing over 20 years can still make a meaningful difference.
A fixed ₹15,000 monthly SIP could potentially accumulate around ₹1.48 crore at an assumed annualised return of 12%, while a 10% annual step-up strategy could produce approximately ₹2.95 crore under the same return assumption.
These figures demonstrate the potential effect of consistent investing and increasing contributions over time.
The key lesson is that retirement planning should begin as soon as possible, even if substantial savings have not been accumulated by age 40.
However, ₹3 crore is not a guaranteed outcome, and its adequacy at retirement will depend on future living costs, investment performance and personal circumstances.
Disclaimer: This article is intended for educational purposes only. SIP calculations are illustrative, use simplified return assumptions and do not account for all taxes, fees or market fluctuations. Mutual fund investments are subject to market risks. Consult a SEBI-registered investment adviser before making major investment decisions.