Business
SIP Calculator 2026: Invest ₹2,000 Monthly for Your Child and See How Much You Could Save in 18 Years

SIP Investment Plan for Children: Planning for a child's education and future financial needs is one of the biggest responsibilities for parents. From school fees to higher education and professional courses, expenses can increase significantly over time. Starting an investment early can help families prepare for these financial commitments without having to arrange a large amount of money at once.
A Systematic Investment Plan (SIP) offers a way to invest a fixed amount in mutual funds every month. Even a monthly investment of ₹2,000, started when a child is born, can potentially grow into a substantial fund over 18 years.
According to the illustrative calculations in the supplied report, a ₹2,000 monthly SIP could grow to approximately ₹11.53 lakh at a 10% annual return, ₹14.23 lakh at 12%, or ₹19.65 lakh at 15%.
However, these figures are estimates rather than guaranteed returns. Actual mutual fund performance depends on market conditions, investment selection, and the returns earned over time.
Why Starting an SIP at Your Child's Birth Can Make a Difference
When parents begin investing shortly after their child's birth, they have approximately 18 years to build a fund before the child reaches adulthood.
This long investment period provides an opportunity to benefit from compounding, where returns generated on an investment can themselves contribute to future growth.
For example, a monthly investment of ₹2,000 may appear relatively small compared with the cost of higher education. However, investing consistently for many years can gradually create a meaningful financial reserve.
The biggest advantage of beginning early is that parents do not necessarily need to invest a large amount every month to pursue a long-term goal.
Starting later may require significantly higher monthly contributions to target the same future amount.
SIP Calculation: How Much Will You Invest in 18 Years?
Consider a family that starts investing ₹2,000 every month through a mutual fund SIP.
Basic SIP investment calculation
Monthly SIP
₹2,000
Investment period
18 years
Total instalments
216
Total amount invested
₹4,32,000
Over 18 years, the family would contribute ₹4.32 lakh from its own savings.
The eventual value of the investment would depend on the returns generated by the selected mutual fund.
What Could ₹2,000 Monthly Become at 10%, 12% and 15% Returns?
The following figures illustrate three possible growth scenarios using the estimates provided in the original report.
| Assumed Annual Return | Total Investment | Estimated Maturity Value | Estimated Gain |
|---|---|---|---|
| 10% | ₹4.32 lakh | ₹11.53 lakh | ₹7.21 lakh |
| 12% | ₹4.32 lakh | ₹14.23 lakh | ₹9.91 lakh |
| 15% | ₹4.32 lakh | ₹19.65 lakh | ₹15.33 lakh |
These are illustrative figures from the source article. SIP calculator results vary according to the compounding convention, contribution timing, and return assumptions.
Illustrative SIP value after 18 years
Monthly investment of ₹2,000; amounts in ₹ lakh
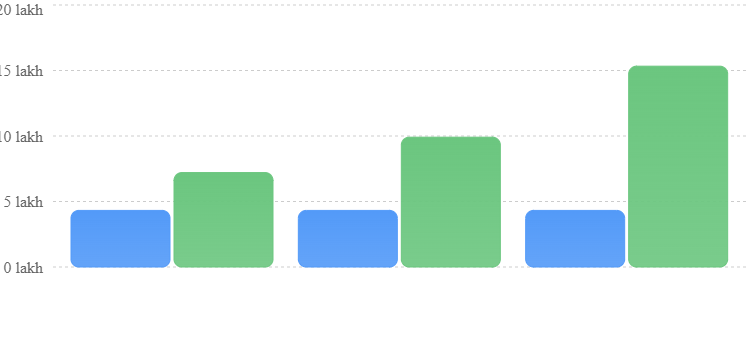
■ Amount invested
■ Estimated gains
SIP at 10% Annual Return: Potential Fund of ₹11.53 Lakh
If the investment earns an assumed average annual return of 10%, the original report estimates that the monthly SIP could accumulate approximately ₹11.53 lakh over 18 years.
Of this amount, ₹4.32 lakh would represent the family's contributions, while approximately ₹7.21 lakh would come from investment growth.
This example demonstrates how the time available for investing can make a difference to long-term savings.
However, a 10% return should not be considered assured. Equity-oriented mutual funds can experience periods of both positive and negative performance.
SIP at 12% Annual Return: Estimated Corpus Above ₹14 Lakh
Under the second scenario, the assumed annual return increases to 12%.
The report estimates that a ₹2,000 monthly SIP could grow to approximately ₹14.23 lakh over 18 years.
Since the total contribution remains ₹4.32 lakh, the estimated investment gain would be ₹9.91 lakh.
The difference between the 10% and 12% scenarios highlights how changes in long-term returns can substantially influence the final amount.
Still, investors should avoid treating a 12% return as a fixed expectation. Mutual fund returns are market-linked and can vary significantly.
SIP at 15% Annual Return: Could the Fund Approach ₹20 Lakh?
A higher assumed annual return of 15% produces a substantially larger projected amount.
According to the supplied estimates, the SIP could accumulate approximately ₹19.65 lakh over 18 years.
The family's total contribution would remain ₹4.32 lakh, while the estimated investment gain would increase to ₹15.33 lakh.
Although this scenario demonstrates the potential benefits of long-term growth, maintaining a 15% annualized return over 18 years is an ambitious assumption.
It should be viewed as an optimistic illustration rather than a reliable forecast.
Calculate Your Own SIP Investment
Use this interactive calculator to explore how changing the monthly contribution, investment period, or assumed annual return affects the projected fund value.
Monthly investment
₹2,000
Investment period
18 years
Assumed annual return
12%
Estimated future value
₹15,15,721
Invested
₹4,32,000
Estimated gains
₹10,83,721
Uses monthly compounding and end-of-month contributions. Assumes a constant annualized rate for illustration, before taxes and other costs. Actual returns will vary.Reset calculator
Step-Up SIP: How Increasing Monthly Contributions Can Help
Parents do not have to continue investing the same amount throughout the entire period.
A step-up SIP allows investors to increase their monthly contributions periodically, often in line with salary increments or growing household income.
For example, a family might begin with ₹2,000 per month and gradually raise the contribution to ₹3,000 or ₹5,000 as its financial position improves.
This approach can help build a larger education fund without requiring a high initial investment.
A step-up strategy should nevertheless be planned around household expenses, emergency savings, and other financial commitments.
What Should Parents Consider Before Starting an SIP?
Choosing a mutual fund solely on the basis of past returns may not be appropriate for a long-term goal such as a child's education.
Parents should consider the investment horizon, their ability to tolerate market fluctuations, fund expenses, and the amount they expect to need when the child reaches college age.
As the education goal approaches, it may be sensible to review the portfolio's risk exposure rather than remain entirely dependent on market performance.
Inflation is another important consideration. A college course that costs ₹10 lakh today could be considerably more expensive after 18 years.
Therefore, the target investment amount should reflect future education expenses rather than current prices alone.
Is a ₹2,000 Monthly SIP Enough for Your Child's Future?
A ₹2,000 SIP can be a useful starting point, but whether it will be sufficient depends on the family's financial goals.
Parents planning for domestic undergraduate education may have different funding requirements from those considering professional courses or overseas studies.
The investment should ideally be reviewed periodically and adjusted as expected education costs, family income, and financial priorities change.
Starting early, investing consistently, and increasing contributions when affordable can help families work toward long-term savings goals.
Conclusion
Starting a ₹2,000 monthly SIP when a child is born can provide an opportunity to accumulate a meaningful fund over 18 years.
The supplied illustrations estimate a maturity value of ₹11.53 lakh at a 10% annual return, ₹14.23 lakh at 12%, and ₹19.65 lakh at 15%, against a total investment of ₹4.32 lakh.
The central lesson is that beginning early and maintaining consistent contributions can be valuable for long-term financial planning. However, actual returns are uncertain, and parents should build their investment strategy around realistic assumptions and their family's financial circumstances.
Disclaimer: SIP investments in mutual funds are subject to market risks. The calculations are illustrative and do not represent guaranteed returns or investment recommendations. Consult a qualified financial adviser before making investment decisions.