Business
Personal Loan EMI Calculator 2026: ₹5 Lakh Loan at 12% Interest, Compare Monthly EMIs for 2 to 5 Years
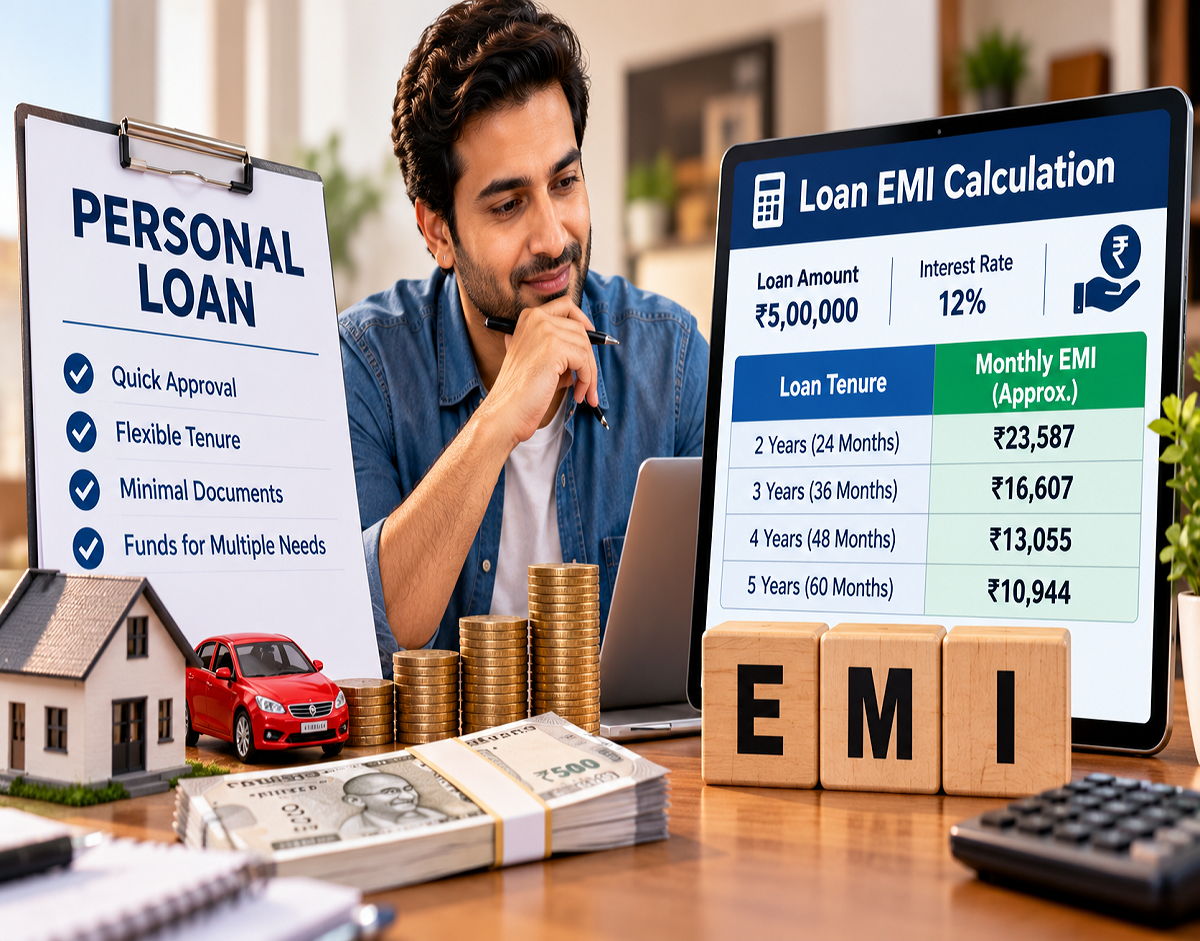
Personal Loan EMI Calculation 2026: Planning to borrow ₹5 lakh from a bank or non-banking financial company (NBFC)? Before applying, it is important to understand how much you will repay every month and how much extra money will go towards interest. While personal loans offer quick access to funds without requiring collateral, choosing the wrong repayment period can significantly increase your overall borrowing costs.
For example, a ₹5 lakh personal loan at an annual interest rate of 12% can have very different monthly instalments depending on whether you choose a repayment period of two, three, four, or five years.
A shorter repayment period generally means higher EMIs but lower overall interest expenses. Meanwhile, extending the loan tenure can reduce the monthly financial burden, although the total interest paid to the lender increases.
Here is a detailed comparison of personal loan EMIs, total repayment amounts, and interest costs across different repayment periods.
Why Is Personal Loan EMI Calculation Important?
Personal loans have become a popular financing option for individuals who need money for medical emergencies, education, weddings, home renovations, travel, or other personal expenses.
Unlike secured loans, personal loans generally do not require borrowers to pledge property, gold, or other assets as collateral.
However, because lenders take on greater credit risk, interest rates on unsecured personal loans are often higher than those on secured loans.
The interest rate offered to a borrower can depend on several factors, including credit score, monthly income, employment stability, existing debt obligations, and the lender's internal eligibility criteria.
For this comparison, we will assume:
- Loan amount: ₹5,00,000
- Annual interest rate: 12%
- Repayment options: 2, 3, 4, and 5 years
- Interest calculation: Monthly reducing-balance method
- EMI type: Fixed monthly instalment
The calculations exclude processing fees, insurance premiums, late-payment penalties, and other additional charges.
₹5 Lakh Personal Loan for 2 Years: Higher EMI but Lower Interest
If you choose to repay a ₹5 lakh personal loan over two years at 12% annual interest, your monthly EMI will be approximately ₹23,537.
You will make 24 monthly payments during the repayment period.
The estimated financial breakdown is:
- Monthly EMI: ₹23,537
- Total repayment: ₹5,64,882
- Total interest: ₹64,882
This option has the highest monthly instalment among the four repayment periods. However, it also results in the lowest total interest cost.
Borrowers with stable incomes and sufficient monthly savings may prefer this option because it allows them to become debt-free sooner.
₹5 Lakh Loan for 3 Years: A Balance Between EMI and Interest
Extending the repayment period to three years reduces the monthly instalment considerably.
At an annual interest rate of 12%, the estimated EMI becomes ₹16,607.
Over 36 months, the total repayment amount will be approximately ₹5,97,858, including interest of ₹97,858.
Compared with the two-year option, the monthly EMI decreases by approximately ₹6,930.
However, the borrower pays nearly ₹32,976 more in total interest.
For borrowers who cannot comfortably manage a monthly payment above ₹23,000, a three-year tenure may provide a more manageable repayment schedule.
₹5 Lakh Personal Loan for 4 Years: How Much Will You Pay?
Choosing a four-year repayment period further reduces the monthly financial commitment.
For a ₹5 lakh loan at 12% annual interest, the estimated EMI will be ₹13,167.
The borrower will repay approximately ₹6,32,012 over 48 months.
Of this amount, around ₹1,32,012 represents interest.
Although the EMI is substantially lower than the two-year option, the overall interest burden is more than twice as high.
This illustrates why borrowers should not select a loan solely based on the lowest available EMI.
₹5 Lakh Personal Loan for 5 Years: Lowest EMI, Highest Interest Cost
A five-year tenure offers the smallest monthly instalment among the repayment options considered.
At 12% annual interest, the estimated monthly EMI is ₹11,122.
Over 60 months, the total repayment amount will be approximately ₹6,67,333.
This includes around ₹1,67,333 in interest alone.
The monthly instalment may look affordable, particularly for salaried borrowers managing several household expenses.
However, choosing five years instead of two years increases the total interest expense by approximately ₹1,02,452.
In other words, reducing the EMI by extending the repayment period comes with a significant additional cost.
Personal Loan EMI Comparison: ₹5 Lakh at 12% Interest
The table below compares the estimated repayment costs across different loan tenures.
| Loan tenure | Monthly EMI | Total repayment | Total interest |
|---|---|---|---|
| 2 years | ₹23,537 | ₹5,64,882 | ₹64,882 |
| 3 years | ₹16,607 | ₹5,97,858 | ₹97,858 |
| 4 years | ₹13,167 | ₹6,32,012 | ₹1,32,012 |
| 5 years | ₹11,122 | ₹6,67,333 | ₹1,67,333 |
How total interest increases with loan tenure
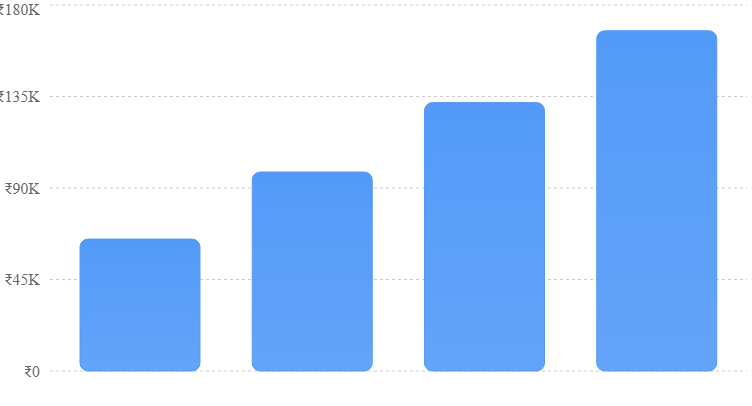
Illustrative calculation for a ₹5 lakh loan at 12% annual interest.
The comparison clearly demonstrates that longer repayment periods reduce monthly EMIs but increase the total amount paid to the lender.
Calculate Your Personal Loan EMI
You can use the calculator below to estimate the monthly instalment and total interest for a different loan amount, interest rate, or repayment period.
Loan amount
₹5,00,000
Annual interest rate
12.0%
Repayment period
3 years
Monthly EMI
₹16,607
Total interest
₹97,858
Principal
Interest
Total repayment
₹5,97,858
Estimates use a fixed rate and monthly reducing balance. Fees and other charges are excluded.
How Much Interest Can You Save by Choosing a Shorter Loan Tenure?
One of the biggest advantages of selecting a shorter repayment period is the reduction in interest expenses.
Consider the difference between a three-year and five-year personal loan.
For a three-year loan, the total interest is approximately ₹97,858.
For a five-year loan, the interest increases to around ₹1,67,333.
By choosing three years instead of five years, a borrower could save approximately ₹69,476 in interest.
Similarly, choosing two years instead of five years could save more than ₹1 lakh.
However, shorter repayment periods also require higher monthly payments. Borrowers should therefore consider whether they can comfortably manage the EMI without compromising essential household expenses.
Should You Use Your Savings to Repay a Personal Loan Early?
Repaying a personal loan ahead of schedule can help reduce interest expenses, particularly when the outstanding principal is substantial.
However, using all available savings to close a loan may create financial difficulties during emergencies.
Borrowers should ideally maintain sufficient funds for essential expenses, medical emergencies, and unexpected income disruptions.
Before making a large prepayment, it is also important to review the lender's foreclosure and part-payment conditions.
Depending on the loan type and applicable regulations, certain charges may apply. These charges can reduce the actual savings from early repayment.
For some floating-rate loans, regulatory restrictions may prevent lenders from charging prepayment penalties, so borrowers should check the specific terms rather than assume that a fee always applies.
How Can You Reduce the Cost of a Personal Loan?
A few practical steps can help borrowers manage their personal loan expenses more effectively.
Maintain a strong credit score: A healthy credit history may improve your chances of obtaining a competitive interest rate.
Compare multiple lenders: Banks and NBFCs may offer different interest rates, processing charges, and repayment conditions.
Choose a manageable tenure: Select the shortest repayment period that allows you to pay your EMIs comfortably.
Avoid unnecessary borrowing: Borrow only the amount required rather than taking a larger loan simply because you qualify for it.
Consider prepayments: If your financial position improves, partial repayment may help reduce interest costs, subject to the lender's terms.
Conclusion
A ₹5 lakh personal loan at 12% annual interest can cost approximately ₹64,882 in interest when repaid over two years. However, extending the repayment period to five years can increase the interest burden to around ₹1.67 lakh.
Although a longer tenure offers lower monthly instalments, it also increases the total borrowing cost.
The most suitable loan tenure is one that balances affordable EMIs with reasonable interest expenses. Before applying, borrowers should compare loan offers, review all additional charges, and ensure they have enough income to meet their repayment obligations.
Disclaimer: These figures are illustrative calculations based on a fixed 12% annual interest rate and the monthly reducing-balance method. Actual EMI amounts, interest rates, processing fees, and repayment conditions may vary by lender. Consult your bank or financial adviser before making a borrowing decision.