Business
LIC Pension Plan: Invest ₹10 Lakh Once and Get Up to ₹7,175 Monthly for Life—See the Calculation
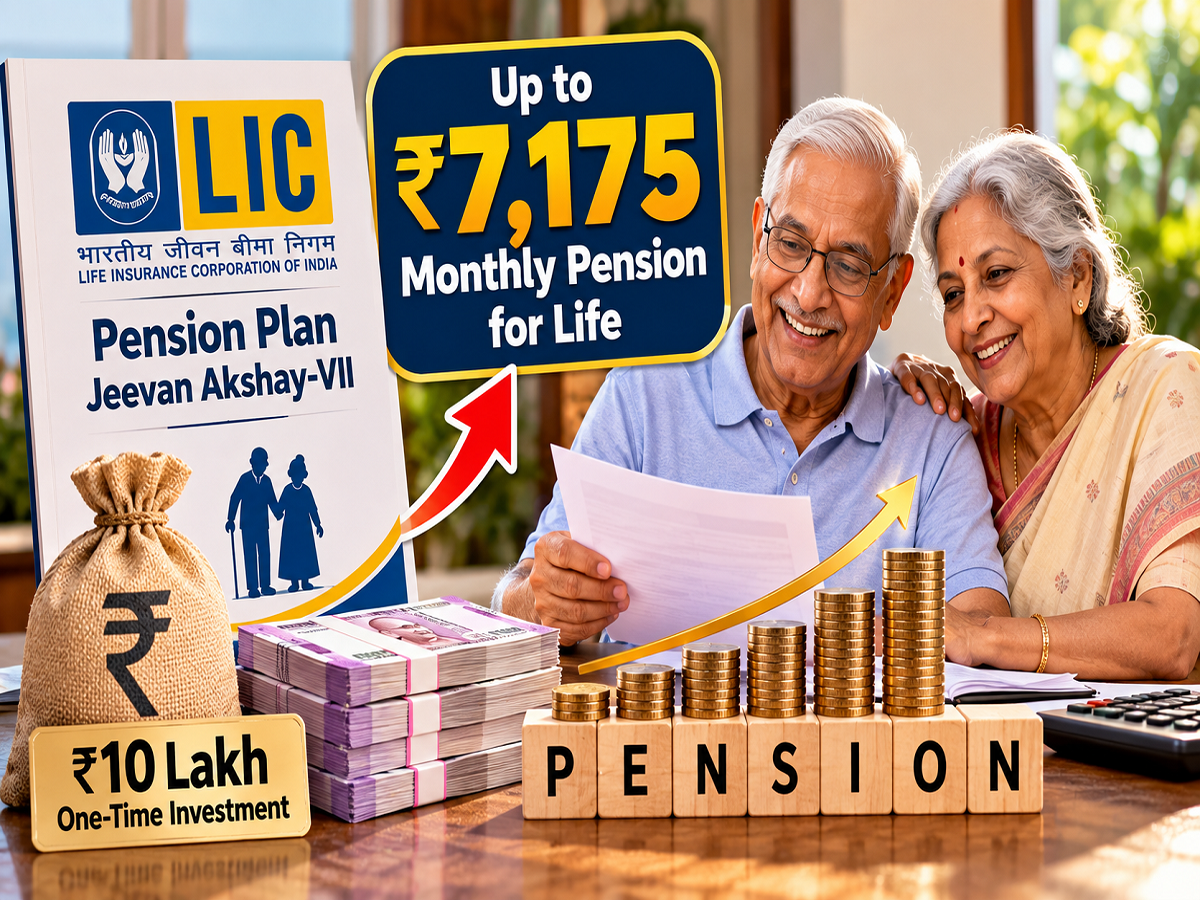
Building a reliable income stream after retirement is an important part of financial planning. For people who want a predetermined pension without making regular premium payments, LIC Jeevan Akshay-VII offers an immediate annuity option where a lump-sum investment can generate income for life.
Instead of paying premiums every month or every year, the policyholder makes a single purchase payment. The annuity then becomes payable according to the option and payment frequency selected at the beginning of the policy.
For example, based on the illustration provided in LIC's V07 brochure, a person aged 60 years investing ₹10 lakh could receive an annual annuity ranging from around ₹64,000 to ₹86,100 under Options A to G, depending on the benefits attached to the selected annuity option.
The amount should not be viewed as a uniform guaranteed return across every option. The actual annuity depends on factors including age, purchase price, annuity option and payment frequency.
₹10 Lakh Investment: How Much Pension Could You Receive?
Consider an investor who is 60 years old and purchases the plan with a lump sum of ₹10 lakh.
Under Option A, the annual annuity in the cited LIC illustration is ₹86,100. Dividing this annual figure by 12 works out to approximately ₹7,175 per month.
Option F, which includes a provision for returning the purchase price after the annuitant's death, provides a lower annual annuity of ₹64,000 in the same illustration. This is equivalent to roughly ₹5,333 a month when the annual figure is divided by 12.
Here is the comparison:
| Annuity Option | Annual Annuity on ₹10 Lakh | Approx. Monthly Equivalent |
|---|---|---|
| Option A | ₹86,100 | ₹7,175 |
| Option B | ₹85,500 | ₹7,125 |
| Option C | ₹84,000 | ₹7,000 |
| Option D | ₹81,800 | ₹6,817 |
| Option E | ₹79,200 | ₹6,600 |
| Option F | ₹64,000 | ₹5,333 |
| Option G | ₹68,700 | ₹5,725 |
These figures are based on the cited illustration for a 60-year-old purchasing a ₹10 lakh annuity with annual payments. The monthly amounts shown above are simple monthly equivalents of the annual figures and should not be treated as the exact monthly-mode annuity quotation, which can differ depending on LIC's applicable terms and rates.
What Is LIC Jeevan Akshay-VII?
Jeevan Akshay-VII is an immediate annuity plan. Unlike a pension product where investors accumulate money for several years before receiving income, an immediate annuity is designed to start annuity payments after the required purchase process, subject to the selected payment mode and policy terms.
The annuity rate is determined at the start based on the selected option and applicable terms. The policyholder can choose how frequently the annuity is received.
LIC provides payment modes including monthly, quarterly, half-yearly and annually.
The plan offers 10 annuity options, allowing buyers to select a structure according to their retirement income and family requirements.
Option A Provides Lifetime Annuity
Under Option A, the annuitant receives a fixed annuity for life.
This is the option that generates ₹86,100 annually in the cited ₹10 lakh, age-60 illustration. Since the structure primarily focuses on providing lifetime income to the annuitant, its initial payout is higher than several options carrying additional guarantees or death-related benefits.
However, choosing an annuity should not be based only on which option shows the highest initial payment. Benefits available after death and other conditions vary significantly between options.
Options B to E Come With Guaranteed Periods
Options B, C, D and E combine lifetime annuity payments with different guaranteed periods.
Depending on the option, the annuity is guaranteed for 5, 10, 15 or 20 years and thereafter continues for as long as the annuitant remains alive.
The additional guarantee explains why the annuity amounts vary across these choices.
For example, the cited illustration shows ₹85,500 annually under Option B, ₹84,000 under Option C, ₹81,800 under Option D and ₹79,200 under Option E.
Option F Can Return the Purchase Price After Death
Option F works differently from a basic lifetime annuity.
The annuitant receives pension payments for life, while the plan also provides for the return of the purchase price after the annuitant's death, subject to the policy terms.
Because this option includes the purchase-price return benefit, its annuity is lower than Option A in the cited example.
For a ₹10 lakh purchase at age 60, the annual annuity shown for Option F is ₹64,000, equivalent to around ₹5,333 per month when simply divided by 12.
For retirees, this illustrates an important trade-off: a higher immediate annuity is not necessarily the only consideration. Some buyers may place greater importance on what happens to the purchase price after their death.
Option G Increases the Annuity by 3% Every Year
Those concerned about receiving the same pension amount throughout retirement can consider the structure offered under Option G.
Under this option, the annuity increases by 3% each year on a simple basis.
The initial pension is consequently lower than under several fixed-annuity choices. In the ₹10 lakh example, Option G starts with an annual amount of ₹68,700, or an approximate monthly equivalent of ₹5,725.
Over time, however, the annuity increases according to the option's terms.
Joint-Life Options Can Cover a Spouse
Jeevan Akshay-VII also includes joint-life choices for people who want pension benefits to continue for their spouse or another eligible joint annuitant according to the policy conditions.
Under the plan's Options H and I, annuity benefits can continue for the second person according to the selected structure.
Option J additionally includes a provision for returning the purchase price after the death of the last surviving annuitant, subject to the policy terms.
For joint-life policies, the annuity amount depends on factors such as the ages of both individuals, the purchase amount and the chosen annuity option.
Is the Annuity Tax-Free?
Receiving a pension from an annuity plan does not automatically make that income tax-free.
Annuity income may be taxable according to the policyholder's applicable income-tax position and prevailing tax rules. Investors should therefore compare post-tax income rather than considering only the headline annuity figure.
Tax rules can also change, making it important to check the provisions applicable during the relevant financial year.
Understand the Liquidity Limitation Before Investing
One of the biggest considerations with an immediate annuity is liquidity.
Once a substantial lump sum has been used to purchase an annuity, accessing that capital may be restricted and will depend on the specific policy provisions. It should therefore not be treated like a normal savings account or fixed deposit where money can necessarily be withdrawn whenever required.
Retirees may need funds for healthcare, emergencies and other unexpected expenses. For that reason, liquidity needs, emergency savings, other sources of income and family requirements should all be considered before committing a large portion of retirement savings to an annuity.
What Should Investors Compare Before Choosing an Option?
The key attraction of Jeevan Akshay-VII is the ability to convert a lump-sum amount into a predetermined annuity stream. However, the option with the highest starting payout may not necessarily suit every retiree.
Someone focused primarily on lifetime income may evaluate the basic lifetime annuity structure differently from someone who wants the purchase price returned after death. Similarly, a married retiree may give greater importance to a joint-life option so that income can continue for the surviving spouse.
For a 60-year-old investing ₹10 lakh, the cited illustration shows how widely payouts can vary—from ₹64,000 to ₹86,100 annually across Options A to G. The difference largely reflects the different guarantees and benefits attached to each choice.
Before purchasing the plan, investors should check LIC's latest official brochure, current annuity quotation, eligibility requirements, surrender provisions, death benefits and tax implications.
Disclaimer: This article is intended for general information and educational purposes only. The figures are based on the illustration cited in the source material and should not be considered a personalised pension quotation or investment recommendation. Actual annuity payments can depend on age, purchase price, payment mode, selected option and LIC's applicable terms. Consider professional financial and tax advice before making a retirement or insurance decision.