Business
LIC Jeevan Umang: Get Annual Survival Benefits, Life Cover and Bonus With This Whole-Life Plan
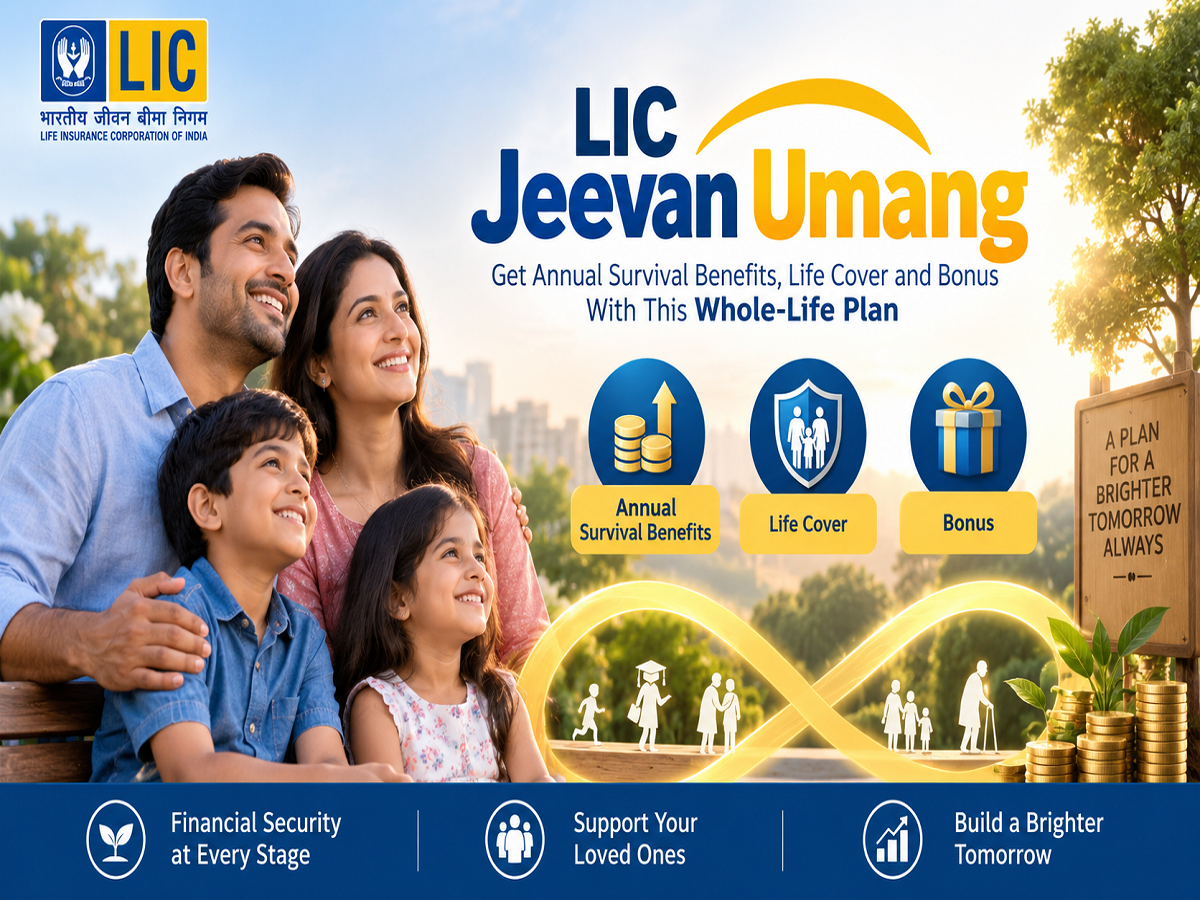
Life Insurance Corporation of India (LIC) offers policies designed for different financial needs, including term insurance, endowment, money-back and long-term savings plans. Among these, LIC Jeevan Umang combines whole-life insurance protection with savings, annual survival benefits and participation in LIC's profits through eligible bonuses.
Jeevan Umang is a non-linked, participating, whole-life insurance plan. One of its key features is that after the premium-paying term is completed, the policyholder can receive an annual survival benefit equal to 8% of the Basic Sum Assured, subject to the policy's terms and conditions.
The policy also provides life insurance protection and may earn Simple Reversionary Bonuses and a Final Additional Bonus, if declared and applicable.
Here is a closer look at how LIC Jeevan Umang works, its eligibility conditions, premium-paying options and benefits.
What Is LIC Jeevan Umang?
Jeevan Umang is designed to combine insurance protection with long-term savings. Unlike a market-linked insurance product, the plan is non-linked, which means its benefits are not directly tied to movements in the stock market.
It is also a participating policy. This allows an eligible policy to participate in LIC's profits and potentially receive bonuses declared by the insurer.
The policy can provide protection over a very long period, with maturity linked to the insured person reaching the specified maturity age under the plan.
Entry Age and Minimum Sum Assured
According to the plan details cited, Jeevan Umang can be purchased for an individual from as young as 30 days old, while the maximum entry age can extend to 55 years, depending on the chosen premium-paying term.
The Basic Sum Assured starts from ₹2 lakh. The available sum assured and other conditions are subject to LIC's applicable policy rules.
The maturity age under the plan is 100 years.
Choose From Different Premium-Paying Terms
Jeevan Umang offers premium-paying terms of 15, 20, 25 or 30 years, but the available option depends on the age of the person entering the policy.
For very young children, certain shorter premium-paying options may not be available. Similarly, people entering the plan at a higher age have fewer premium-paying term choices.
For example, the article states that people aged 51 to 55 can opt for a 15-year premium-paying term. Those entering between 46 and 50 may have 15- and 20-year options, while entry between ages 41 and 45 may allow 15-, 20- and 25-year premium-paying terms.
How Does the 8% Annual Survival Benefit Work?
A major feature of Jeevan Umang is the annual survival benefit that starts after the premium-paying term is completed, subject to the policy remaining eligible for benefits.
The annual benefit is equivalent to 8% of the Basic Sum Assured.
For example, if the Basic Sum Assured is ₹10 lakh, 8% works out to:
₹10,00,000 × 8% = ₹80,000 per year
Therefore, the annual survival benefit would be ₹80,000 under this example.
It is important to describe this benefit correctly. Although it may function as a regular annual income stream, it should not be confused with a conventional pension or annuity product. Jeevan Umang is fundamentally a participating whole-life insurance and savings plan.
What Happens at Maturity?
If the life assured survives until the specified maturity age, the maturity benefit is payable according to the policy conditions.
This generally includes the applicable Sum Assured on Maturity along with vested Simple Reversionary Bonuses and any Final Additional Bonus, if declared and applicable.
Since bonuses depend on LIC's declarations and the policy's eligibility, future bonus amounts should not be treated as guaranteed returns.
Death Benefit Provides Financial Protection
Jeevan Umang also provides a death benefit if the life assured dies while the policy is in force.
The amount payable depends on the policy terms, the stage at which the death occurs and other applicable conditions. Eligible vested bonuses and a Final Additional Bonus, where applicable, may also form part of the benefit.
Special rules apply when the policy is purchased for a young child.
According to the details cited, where the life assured is below eight years of age at entry, risk commencement is subject to specific conditions linked to the policy commencement date and the policy anniversary around the child's eighth birthday.
If death occurs before the commencement of risk, the benefit is determined under the special provisions applicable to such policies rather than the regular death-cover calculation.
Example of a ₹10 Lakh Policy for a Child
Consider an illustrative case where a policy with a ₹10 lakh Basic Sum Assured is purchased for a two-year-old child with a 20-year premium-paying term.
The example cited in the source assumes the guardian is 35 years old and includes Accidental Death and Disability Benefit (ADDB) and Premium Waiver Benefit (PWB) riders.
Under those assumptions, the quoted annual premium is approximately ₹55,765, equivalent to roughly ₹153 per day when divided across the year. Without the PWB rider, the illustrative annual premium is given as approximately ₹53,535.
After completing the 20-year premium-paying term, when the child reaches around 22 years of age, an annual survival benefit of ₹80,000 would correspond to 8% of the ₹10 lakh Basic Sum Assured.
Actual premiums depend on LIC's prevailing rates, rider selection, taxes, underwriting and other policy conditions.
How Can the Premium Waiver Benefit Help?
A Premium Waiver Benefit rider can be particularly relevant when insurance is purchased for a child.
Subject to the rider's conditions, if the person responsible for paying premiums dies during the applicable period, future premiums may be waived while the underlying policy continues.
This feature can help ensure that the child's insurance and savings plan does not automatically end merely because