Business
Home Loan EMI Calculator: Save ₹12.41 Lakh in Interest by Repaying Your 20-Year Loan 5 Years Early
Home Loan EMI Calculator 2026: Buying a house is one of the biggest financial commitments for most families. While a home loan makes property ownership more accessible, the interest paid over 15 or 20 years can significantly increase the total cost of purchasing a home.
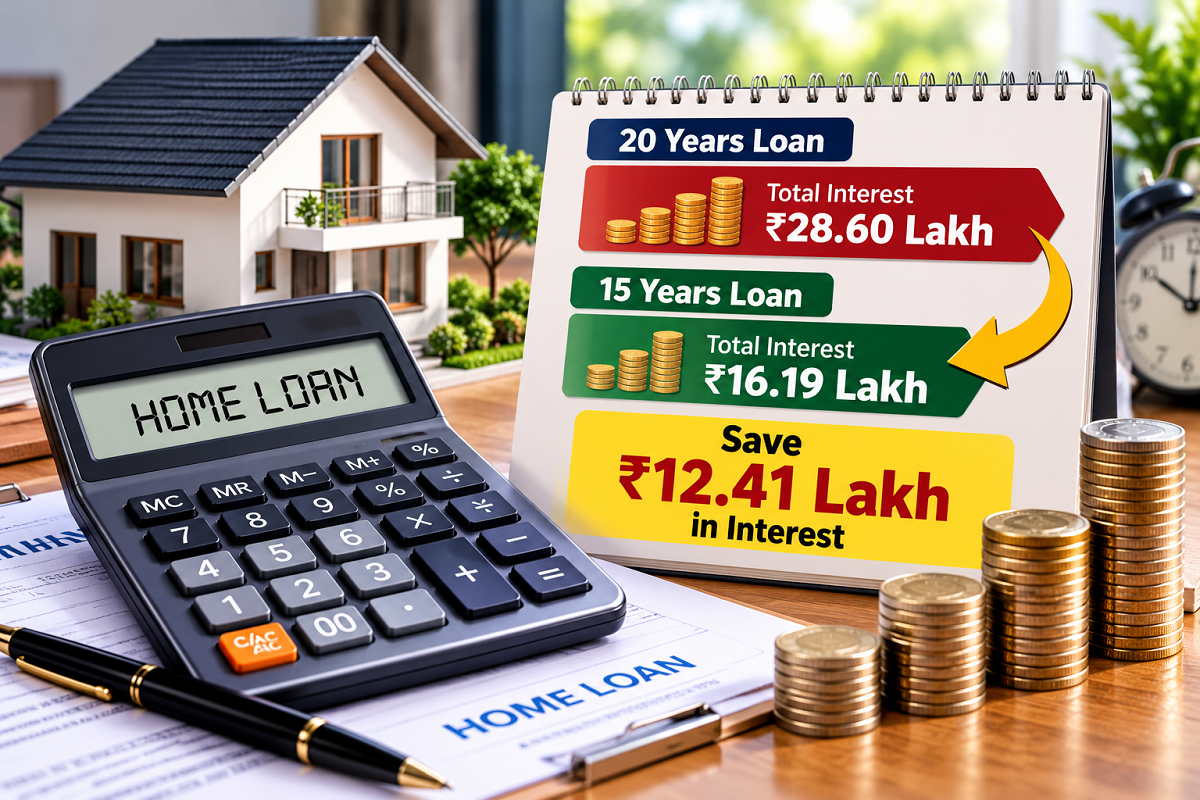
However, a simple change in your repayment strategy could help you save lakhs of rupees. For example, if you have a ₹40 lakh home loan at an annual interest rate of 8.5%, reducing the repayment period from 20 years to 15 years could save you approximately ₹12.41 lakh in interest.
The most interesting part is that you do not need to make a massive additional payment every month. Increasing your EMI by around ₹4,677 could help you become debt-free five years earlier.
Let's understand the complete calculation and explore another practical way to repay your housing loan faster without permanently increasing your monthly EMI.
Home Loan EMI Calculator: ₹40 Lakh Loan at 8.5% Interest
Suppose you borrow ₹40 lakh from a bank to purchase a residential property.
The bank offers an annual interest rate of 8.5%, and you select a repayment tenure of 20 years.
Under a standard monthly reducing-balance calculation, your monthly EMI would be approximately ₹34,713.
Over the entire 20-year period, you would repay around ₹83.31 lakh to the bank.
Of this amount, ₹40 lakh represents the original loan principal, while approximately ₹43.31 lakh is the interest paid.
This means the total interest over 20 years would exceed the amount originally borrowed.
The calculation demonstrates why choosing the right loan tenure is important when planning long-term household finances.
What Happens if You Repay the Same Loan in 15 Years?
Now consider the same ₹40 lakh loan at the same annual interest rate of 8.5%, but with a repayment period of 15 years instead of 20 years.
Your monthly EMI would increase to approximately ₹39,390.
This is around ₹4,677 more than the EMI for the 20-year loan.
However, the total amount repaid over 15 years would fall to approximately ₹70.90 lakh.
The total interest expense would also decrease substantially, from around ₹43.31 lakh to ₹30.90 lakh.
As a result, you could save approximately ₹12.41 lakh in interest while completing the loan repayment five years earlier.
20-Year vs 15-Year Home Loan: Complete EMI Comparison
Here is a detailed comparison of both repayment options.
| Loan Details | 20-Year Home Loan | 15-Year Home Loan |
|---|---|---|
| Loan amount | ₹40,00,000 | ₹40,00,000 |
| Annual interest rate | 8.50% | 8.50% |
| Loan tenure | 20 years | 15 years |
| Number of EMIs | 240 | 180 |
| Monthly EMI | ₹34,713 | ₹39,390 |
| Total repayment | ₹83.31 lakh | ₹70.90 lakh |
| Total interest | ₹43.31 lakh | ₹30.90 lakh |
<text preserveWhitespace={true}>Additional monthly EMI: Approximately ₹4,677
Loan tenure reduced by: 5 years
Total estimated interest savings: ₹12.41 lakh</text>
These calculations assume that the interest rate remains constant at 8.5% throughout the repayment period and that all EMIs are paid on schedule.
Actual savings may differ if the interest rate changes, the lender recalculates the EMI, or additional fees apply.
Why Does a Shorter Loan Tenure Reduce Interest?
Home loan interest is generally calculated on the outstanding principal balance.
During the initial years of a long-term housing loan, a relatively large portion of each EMI goes towards interest.
As the principal gradually decreases, the interest component becomes smaller and more of the EMI goes towards reducing the outstanding loan.
When you choose a shorter repayment period, your monthly EMI increases, allowing the principal to decline faster.
Because the outstanding principal reduces more quickly, the bank charges interest on a smaller balance over time.
This is why a five-year reduction in tenure can produce substantial savings even when the increase in monthly EMI appears relatively modest.
Can You Repay a Home Loan Early Without Increasing Your EMI?
Yes. Increasing the monthly EMI is not the only way to reduce your home loan interest burden.
Another option is to make periodic partial prepayments.
A home loan prepayment involves paying an additional amount towards the outstanding principal, over and above your regular EMI.
For example, suppose you receive an annual performance bonus, a salary increment, or additional income from another source.
Instead of spending the entire amount, you could use a portion of it to reduce your home loan balance.
This decreases the principal on which future interest is calculated.
Over time, regular prepayments can help shorten the loan tenure and reduce the overall interest expense.
How Does Home Loan Prepayment Work?
Consider a borrower who has an outstanding home loan balance of ₹30 lakh.
If the borrower makes an additional principal repayment of ₹2 lakh, the outstanding balance could fall to ₹28 lakh, assuming the payment is applied entirely towards principal.
Future interest would then be calculated on the reduced outstanding amount.
The actual benefit depends on when the prepayment is made, the prevailing interest rate, and how the lender adjusts the repayment schedule.
Prepayments made during the earlier years of a long-term loan can often produce greater interest savings because more of the original repayment period remains.
However, borrowers should first confirm the lender's prepayment conditions and any applicable charges.
Reduce EMI or Reduce Loan Tenure: Which Saves More Interest?
After making a partial home loan prepayment, some lenders may allow borrowers to choose between reducing their monthly EMI and shortening the remaining loan tenure.
Both options can provide financial benefits, but they serve different purposes.
Reducing the EMI: This option lowers the monthly repayment burden and may be useful for borrowers who want more flexibility in their household budget.
Reducing the tenure: This option generally maintains the existing EMI while shortening the repayment period, potentially producing greater total interest savings.
For borrowers who can comfortably afford their existing EMI, reducing the tenure may be an effective way to lower the overall cost of borrowing.
However, the final choice should depend on income stability, emergency savings, and other financial obligations.
What if Your Salary Increases During the Loan Period?
Annual salary increments can create an opportunity to accelerate home loan repayment.
For example, an employee paying ₹34,713 per month towards a home loan may find it easier to increase the EMI after receiving a salary hike.
Even a gradual increase in monthly repayments can reduce the outstanding principal faster.
Borrowers can also consider directing part of their annual bonus towards loan prepayment.
However, increasing the EMI should not come at the cost of essential household expenses, insurance coverage, or emergency savings.
A repayment strategy should remain manageable even if unexpected financial difficulties arise.
Important Things to Check Before Prepaying a Home Loan
Before making additional repayments, borrowers should review their loan agreement and lender policies.
Several factors can influence the benefits of early repayment.
1. Prepayment Charges
For eligible floating-rate home loans to individual borrowers, regulatory restrictions generally prevent lenders from charging foreclosure or prepayment penalties, subject to the applicable rules.
However, fixed-rate loans and other loan arrangements may have different conditions.
Always confirm the terms applicable to your particular loan.
2. Interest Rate Type
Floating-rate home loans may experience changes in interest rates over time.
If rates increase, the EMI or loan tenure may also change depending on the lender's policy and the borrower's selected repayment arrangement.
3. Emergency Fund
Using all available savings to repay a home loan may create difficulties during medical emergencies, job loss, or other unexpected expenses.
Maintaining an adequate emergency fund should remain an important part of financial planning.
4. Tax Benefits
Eligible home loan borrowers may qualify for certain income tax deductions, depending on the applicable tax regime and statutory conditions.
Early repayment can affect the amount of interest paid and consequently the deductions available.
Borrowers should assess the overall financial impact rather than focusing exclusively on interest savings.
Is a 15-Year Home Loan Better Than a 20-Year Loan?
A shorter loan tenure can reduce total interest expenses, but it also requires a higher monthly repayment.
A 15-year loan may be suitable for borrowers who have stable income and sufficient room in their monthly budget.
A 20-year loan may offer greater affordability because of the lower EMI.
For example, the difference between ₹34,713 and ₹39,390 per month may be manageable for some households but significant for others.
The most suitable tenure depends on income, existing liabilities, household expenses, financial goals, and the ability to manage unexpected costs.
Borrowers should avoid selecting an EMI that places excessive pressure on their monthly finances.
Home Loan EMI Calculation Formula
Banks commonly use the following formula to calculate EMIs for reducing-balance loans:
[
EMI = \frac{P \times r \times (1+r)^n}{(1+r)^n-1}
]
Where:
- P represents the principal loan amount.
- r represents the monthly interest rate.
- n represents the total number of monthly instalments.
For an annual interest rate of 8.5%, the monthly rate used in this illustration is 8.5% divided by 12.
Using this formula, the EMI for a ₹40 lakh loan over 20 years is approximately ₹34,713, while the EMI for 15 years is approximately ₹39,390.
These values are rounded for simplicity.
Home Loan Repayment: How to Save More Interest
Repaying a home loan early can provide significant long-term financial benefits.
For a ₹40 lakh housing loan at 8.5% annual interest, reducing the tenure from 20 years to 15 years increases the EMI by approximately ₹4,677.
However, the total interest expense falls by around ₹12.41 lakh, and the borrower becomes debt-free five years earlier.
Those who do not want to commit to a permanently higher EMI can explore occasional principal prepayments using bonuses, salary increments, or other surplus income.
The key is to balance faster debt repayment with monthly affordability, emergency savings, and other financial priorities.
Disclaimer: The calculations are illustrative and assume a constant annual interest rate of 8.5%, monthly reducing-balance interest calculation, and timely EMI payments. Actual loan costs and savings may vary depending on lender policies, interest rate changes, fees, and repayment terms. Consult a qualified financial adviser or your lender before making major repayment decisions.